

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: GKRS (Gamma Knife Radiosurgery) Market Surges to USD 482.5 Million in 2025, Study Shows

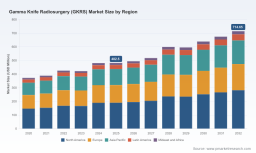
Gamma Knife Radiosurgery (GKRS) Market: Strategic Intelligence for 2026 Decision-Makers
PW Consulting’s latest market research briefing on the Gamma Knife Radiosurgery (GKRS) market distills actionable intelligence for executives, hospital system strategists, medtech investors, and industry partners preparing strategic moves in 2026. Built on a comprehensive baseline (2020–2025) and a forward-looking forecast through 2032, this briefing surfaces the commercial and clinical inflection points that will shape capital allocation, clinical program design, and competitive positioning over the next investment cycle.
Gamma Knife Radiosurgery Gkrs Market Research
Market Snapshot: A Compact, Growing, and Concentrated Market
Our analysis identifies the GKRS market as a high-value, growth-oriented niche. The market expanded through the first half of the decade and reached an estimated USD 482.5 million in 2025. Under current structural drivers and adoption patterns, PW Consulting projects a mid-single-digit compound annual growth rate (CAGR) of approximately 5.76% over the 2026–2032 forecast window, with a trajectory that points to continued expansion into the early 2030s.
Gamma Knife Radiosurgery Gkrs Market Research
While the market is relatively compact in absolute terms compared with broader radiation oncology equipment segments, its clinical specificity and capital intensity give it outsized strategic importance for institutions that prioritize neurosurgical excellence and specialty program differentiation. Importantly, the market has shown resilient growth despite episodic headwinds and periodic year-to-year variability—evidence of durable clinical demand anchored in unique therapeutic value propositions for intracranial disease management.
Gamma Knife Radiosurgery Gkrs Market Research
Key Dynamics Shaping 2026 Decisions
-
Clinical Indication Expansion: Regulatory progress—most notably an expanded indication clearance in mid-2025 for refractory, drug-resistant mesial temporal lobe epilepsy—highlights how non-oncologic indications can materially broaden clinical utilization beyond traditional tumor-focused use. Clinical-label extensions and new evidence will be critical levers for volume growth and payer negotiation in 2026.
-
Reimbursement and Procedural Economics: The procedural economics for single-fraction radiosurgery remain robust relative to some alternative platforms. Observed charge benchmarks underscore favorable revenue-per-case dynamics at established centers, creating meaningful margin opportunity for well-structured programs—but they also invite payer scrutiny and will necessitate proactive commercial and health-economics engagement.
-
Capital Intensity and Service Lifecycles: GKRS platforms are high-ticket, single-purpose capital investments with long clinical lifespans. Source management for cobalt-60 and the regulatory requirements tied to installation and decommissioning impose unique lifecycle costs that organizations must model explicitly when comparing GKRS to multi-purpose linac-based solutions.
-
Concentration and Competitive Dynamics: The market exhibits high concentration among a small number of established OEMs. This concentration creates both stability and strategic friction: longtime centers benefit from deep clinical experience and service ecosystems, while new entrants and alternatives create targeted competitive pressure in selected geographies and price segments.
Competitive Landscape — Who Matters and Why
Competition in GKRS is dominated by proven OEMs and a set of regional alternatives. PW Consulting’s competitive review focuses on providers that materially influence buying patterns, service levels, and clinical differentiation:
-
Elekta AB (Stockholm, Sweden): The primary manufacturer of Leksell Gamma Knife systems, including platform variants that span legacy to modern configurations. Elekta’s installed base, clinical partnerships, and consumable ecosystem create a durable commercial moat. Their July 2025 regulatory clearance to expand indications into specific epilepsy applications is a watershed event—one that will shift clinical conversation and capital planning among tertiary neurocenters.
-
MASEP Medical Science & Technology Development Co., Ltd. (China): A producer of rotary gamma ray neurosurgery options that represents a regional alternative to incumbent designs. MASEP’s positioning underscores the strategic interplay between cost, regional regulatory frameworks, and hospital procurement preferences.
-
American Radiosurgery Inc. (United States): Offers rotating gamma systems for radiosurgery applications and exemplifies the innovation and competitive diversity in non-linear accelerator-based intracranial radiosurgery technologies.
Together, these providers shape procurement choice sets, service-model expectations, and upgrade cycles. The market’s concentrated nature elevates the importance of supplier negotiation, service-level contracting, and strategic partnerships—particularly in service, source management, and training.
Strategic Imperatives for 2026
-
Reassess Clinical Program Positioning: Health systems should revisit the role of GKRS in their neuro-oncology and functional neurosurgery portfolios. The expanded clinical indications and robust per-case economics mean that a new generation of GKRS programs can be justified not only on tumor control metrics but also on service-line diversification and referral-base capture.
-
Model Full Lifecycle Economics: Procurement decisions must move beyond acquisition price to full lifecycle analysis: radioactive source logistics, regulatory compliance, periodic source replacement, decommissioning liabilities, and long-term service agreements materially affect total cost of ownership. Our clients must incorporate scenario-based sensitivity analyses into capital planning for 2026–2028.
-
Design Payer and Value Demonstration Strategies: Given current charge benchmarks and payer scrutiny, centers should prepare bundled-care narratives, real-world outcomes data, and cost-offset analyses to defend reimbursement levels and justify premium pricing where appropriate. Early engagement with payers on new indications—especially non-oncologic—will be a differentiator.
-
Prioritize Strategic Service Contracts and Talent: With a concentrated vendor landscape, service response times, training programs, and clinical onboarding matter. Health systems should negotiate service-level agreements tied to uptime guarantees, source management, and outcome-based KPIs, and should plan talent pipelines for specialized neurosurgical and radiation oncology teams.
-
Consider Flexible Investment Pathways: For systems weighing GKRS acquisition, hybrid approaches—shared regional programs, joint ventures with specialty centers, or phased investments aligned to clinical volume triggers—can optimize capital deployment while enabling programmatic growth.
What PW Consulting’s Report Delivers (Practical, Executable Intelligence)
Our full GKRS market study is organized to support decision-making across commercial, clinical, and capital functions. Key practical deliverables include:
-
Dynamic financial models that capture purchase, service, source-replacement, and decommissioning scenarios for multi-year ROI analysis.
-
Clinical pathway assessments and go-to-market playbooks to support program launch or label-expansion commercialization.
-
Buyer’s checklists and procurement negotiation templates tuned to service-level and life-cycle risk factors.
-
Payer engagement frameworks and health-economic evidence templates to defend clinical value and pricing for both oncologic and emerging non-oncologic indications.
-
Competitive supplier scorecards and partnership assessment matrices to inform M&A and strategic sourcing decisions.
-
Regulatory and operational risk maps that highlight radiation safety, source logistics, and compliance milestones across installation, ongoing operation, and end-of-life decommissioning.
To preserve commercial value for clients and catalyze direct engagement, the report purposely refrains from publishing detailed segmentation line-items in preview materials. The full datasets, including granular regional, indication, and component splits, are available through the PW Consulting portal and are presented with downloadable financial models and sensitivity tools.
How Executives Should Use This Intelligence in 2026
-
CEOs and CFOs: Use our lifecycle financial scenarios to stress-test CapEx approvals and to structure financing or sharing arrangements that mitigate decommissioning and replacement risks.
-
Chief Medical Officers and Program Directors: Leverage the clinical playbooks and payer-engagement templates to accelerate service-line launches for expanded indications and to secure predictable referral volumes from regional networks.
-
Corporate Development and Investors: Target acquisitions where clinical pipelines, installed base service revenue, and regional payer dynamics align; be attentive to consolidation among dominant OEMs and the implications for aftermarket economics.
-
Purchasing and Operational Leaders: Negotiate service agreements that convert uptime into measurable clinical throughput and tie vendor compensation to outcomes and availability.
Why This Matters Now
2026 represents an inflection year: regulatory shifts have opened new clinical opportunities, economic signals favor centers able to demonstrate differentiated value, and concentrated vendor dynamics create both negotiation leverage and supply-side risks. PW Consulting’s GKRS intelligence synthesizes these forces into a structured, executable agenda—helping organizations convert market growth into sustainable, risk-balanced programs.
For executives who require the full analytical and financial toolkit, PW Consulting provides the complete report package—comprehensive datasets, scenario models, and bespoke advisory engagements to operationalize the insights described in this briefing. Access to the full segmentation, provider-level benchmarking, and downloadable financial models is available through our report page and client services team.
Contact PW Consulting to reserve a briefing and to receive the detailed datasets and model license that institutional decision-makers need to act confidently in 2026.
For detailed analysis of this topic, please visit the official page: Gamma Knife Radiosurgery Gkrs Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com