

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 10.51% CAGR for Built‑In Electric Curtains Market (2026–2032), Signaling Rapid Global Adoption

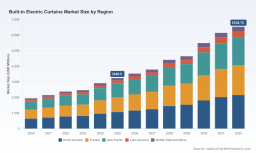
Built-In Electric Curtains Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s new market study on the Built-In Electric Curtains market delivers a practitioner-oriented intelligence pack designed to influence executive decisions in 2026. The market is entering a phase of accelerated consolidation and technology-driven differentiation: with a base-year market size of USD 3,248.5 Million (2025) and a forecast path that builds on a 10.51% CAGR into the 2026–2032 horizon, stakeholders must reconcile product, channel, and supply-chain strategies now to capture the next wave of growth.
Built In Electric Curtains Market
Why this report matters for 2026 decision-makers
- Translate growth into profitable scale: the market’s healthy CAGR signals opportunity, but capture requires alignment across engineering, procurement, and commercial functions.
- Navigate supply‑chain and regulatory headwinds: tariff exposure on motors, fabrics and aluminum extrusions, plus safety standards, are already reshaping cost and design trade-offs.
- Differentiate via systems integration: interoperability, silent operation and aesthetic integration are table stakes; software ecosystems and installation economics are the new battleground.
- Prioritize capital allocation: the report converts market projections into actionable ROI scenarios for R&D, channel investments, and M&A through 2032.
Top-line market dynamics — a synthesis
Built-in electric curtains are shifting from niche luxury to a mainstream specification for both high-end residential projects and targeted commercial segments. Over the 2020–2025 historical window the category expanded materially, culminating in a 2025 market size of USD 3,248.5 Million. Our base-case extrapolation—anchored in observed adoption curves, product lifecycles, and deployment economics—projects continued expansion through 2032, with the market more than doubling by the end of the forecast period under current assumptions.
Built In Electric Curtains Market
Drivers: smart-home adoption, rising demand for energy-efficient fenestration solutions, growth in specification-driven commercial fit-outs, and an increase in integrated new-build requirements. Offsetting factors include regulatory/tariff volatility and rising input costs for key components.
Built In Electric Curtains Market
What the full report delivers (practical, decision-ready tools)
- Market sizing and forecasting framework — transparent methodology, sensitivity bands and scenario outputs for 2026–2032 so executives can stress-test assumptions.
- Go-to-market playbooks — differentiated approaches for OEMs, systems integrators, construction specifiers and retrofit installers, including channel economics and margin models.
- Supplier and component risk maps — supplier concentration analysis, alternative sourcing strategies and actionable mitigation plans for tariff and duty exposures.
- Product roadmap templates — checklist-driven requirements for motors, quiet-track systems, power options (AC/battery/solar), sensors and fail-safes consistent with current safety standards.
- Commercial models — pricing, warranty, and service economics for built-in installations vs retrofits; break-even and payback calculators tailored to typical project archetypes.
- Regulatory compliance playbook — design implications of safety standards and import classifications, with practical steps for product redesign and labeling to reduce trade friction and liability.
- Implementation assets — sample RFPs, installation SOPs, training curricula and a partner evaluation scorecard to accelerate program rollout.
Competitive landscape — who matters and why
The market shows meaningful, but not overwhelming, concentration: the top three players account for roughly 42% of market activity, and the top five approach about 57%. This structure creates room for category leaders to protect premium positions while offering opportunity windows for focused challengers and component specialists.
- Somfy (Cluses, France) — a global leader in motorized window treatments. Somfy’s strength lies in proprietary motor and systems integration (TaHoma, RTS, Zigbee) and its ability to offer recessed and track-based solutions that appeal to both residential and commercial channels.
- Hunter Douglas (Rotterdam, Netherlands) — leverages premium brand equity and the PowerView motorization suite to win design-led projects and specifications, particularly where brand and aesthetics are prioritized.
- Lutron Electronics (Coopersburg, PA, USA) — brings shading and lighting control expertise to complex integrated systems; premium positioning and deep integration capabilities make Lutron a go-to for high-end centralized control projects.
- Silent Gliss (Bern/Broadstairs) — specialist in motorized tracks emphasizing quiet operation and architectural integration. Appeals to design-conscious segments and projects where acoustics are material to the specification.
- Coulisse / Motionblinds (Enter, Netherlands) — B2B manufacturer focusing on smart, modular systems. Recent product initiatives (Motionblinds Matter Bridge and a smart showroom experience launched April 2025) demonstrate how interoperability and demonstrable install experience are being used to accelerate specification wins.
- Dooya (Ningbo, China) — a leading supplier of tubular and curtain motors; plays a critical role in global OEM and ODM supply chains, enabling cost-efficient motor and integration options for many manufacturers and installers.
Collectively, incumbents and component specialists establish a landscape where brand-led control systems, design-driven track solutions, and low-cost motor supply coexist. Strategic partnerships and selective vertical integration are common responses to this mixed-structure market.
Regulatory, trade and materials headwinds
- Tariff exposure: US import tariffs on motors, fabrics and related components (commonly in ranges that can materially affect landed costs) are a live issue for procurement teams and merit active tariff classification reviews and alternative sourcing plans.
- Safety standard impact: adoption of ANSI/WCMA A100.1-2022 and comparable norms has accelerated motorization as manufacturers phase out free-hanging cords; this transition requires re-engineering of manual-to-motor conversions and influences retrofit offerings.
- Raw material pressures: aluminum extrusions and tubular elements—critical to quiet and integrated track systems—face additional import duties in some jurisdictions, pushing manufacturers to reassess local extrusion sourcing, design-for-cost, and modular track architectures.
Strategic actions to prioritize in 2026
- Adopt a modular product architecture: design motor and track modules that support multiple installation modes (recessed, surface, track) and power options to reduce SKUs and simplify installation economics.
- Invest in interoperability: prioritize Matter/Thread, Zigbee, and mainstream smart-home integrations to lower friction with specifiers and to win bundled smart-building deals.
- Dual-source critical components: mitigate tariff volatility and supply disruptions by qualifying alternate motor and extrusion suppliers across geographies and by building inventory buffers tied to project pipelines.
- Design for compliance: make ANSI/WCMA alignment a product development principle to smooth retailer and specification acceptance and to reduce liability risk in retrofit channels.
- Pilot end-to-end installation services: capture higher lifetime value by combining product sales with certified installation and maintenance packages; use pilot programs to quantify install time savings and service economics.
- Refine channel segmentation: deploy different commercial models for custom-specification channels (architects, MEP contractors), trade installers, and direct-to-consumer projects, each with tailored margin incentives and training resources.
- Leverage sustainability as a differentiator: use material disclosures, energy-saving narratives and end-of-life programs to distinguish offerings in commercial and premium residential bids.
- Prepare M&A and alliance playbooks: use a disciplined checklist to evaluate tuck-ins that close capability gaps (quiet-track tech, local extrusion capacity, smart-home middleware).
Conclusion — how PW Consulting helps you act
This preview outlines the structural forces shaping the Built-In Electric Curtains market in 2026—but the precise commercial levers and district-level segmentation that drive tactical choices are intentionally withheld from this summary. PW Consulting’s full report provides the granular segment analytics, regional demand curves, supplier scorecards and financial models necessary to operationalize the strategies summarized here.
For product teams, procurement leads, channel strategists and corporate development executives preparing 2026 budgets and roadmaps, this study is designed to be directly actionable: not just market context, but concrete templates, scenario outputs and vendor engagement strategies you can apply immediately. Access the full report and the downloadable implementation toolset at PW Consulting to convert the market’s growth trajectory into defendable market share and margin gains.
For detailed analysis of this topic, please visit the official page: Built In Electric Curtains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com