

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Orthodontic Aids Market Poised for Robust 8.45% CAGR Through 2026–2032

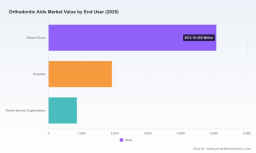
Orthodontic Aids Market 2026: Strategic Playbook for Navigating Acceleration and Regulation
Executive preview
PW Consulting’s latest Orthodontic Aids Market report synthesizes commercial, clinical, regulatory and technology signals to give healthcare leaders a tactical edge entering 2026. The global market has moved from a post‑pandemic recovery into a structurally higher growth phase — rising from roughly USD 5.1 billion in 2020 to about USD 7.85 billion in 2025, and is expected to exceed USD 8.9 billion in 2026 as the sector accelerates toward an approximately 8.45% CAGR across the 2026–2032 forecast window. That macro trajectory creates both opportunity and complexity: stronger topline expansion is paired with tightening regulatory scrutiny, evolving reimbursement codes and new digital entrants reshaping clinical workflows.
Orthodontic Aids Market
Why this report matters for 2026 decision makers
-
Actionable market sizing that informs resource allocation: Our consolidated top‑line and forecast allow executives to size near‑term revenue pools and test scenario sensitivities for new product launches, channel investments and manufacturing scale‑up.
Orthodontic Aids Market -
Regulatory and reimbursement navigation: The report maps the most consequential compliance inflection points — including Class II device pathways, European MDR obligations and the 2026 CDT procedural code updates — and translates them into go/no‑go timelines for market entry and product claims.
Orthodontic Aids Market -
Commercial playbooks for 2026–2028: We provide segmented GTM options that align to clinic, hospital and DSO purchasing behaviours as the market modernizes around digital diagnostics and remote care models.
-
M&A and portfolio-prioritisation screening: With market concentration metrics indicating a mid‑high degree of consolidation among the leading players, the report contains an M&A framework to assess tuck‑ins, technology partnerships and asset divestitures that are most likely to drive rapid scale or margin uplift.
Key dynamics shaping strategy
The orthodontic aids landscape is being rewritten along four vectors that demand immediate strategic responses:
-
Digital workflow adoption: Integration of intraoral scanning, AI‑driven diagnostics and clear aligner manufacturing is compressing treatment cycles and increasing supplier capture at the workflow level. Recent regulatory clearances for AI‑enabled 3D diagnostic tools highlight the practical arrival of automated planning into the clinician’s toolkit.
-
Regulatory tightening and regional divergence: Class II device expectations, European MDR compliance and tightened oversight of direct‑to‑consumer models are elevating product development costs and time‑to‑market. Firms must operationalize a regulatory roadmap that treats certification as a strategic milestone rather than an administrative checkbox.
-
Reimbursement and coding shifts: The American Dental Association’s 2026 CDT update introduces coding and billing changes that alter practice economics for orthodontic services. Early alignment with payer and DSO stakeholders can translate coding changes into competitive advantage for innovative service models.
-
Channel and competitive consolidation: Our market concentration analysis shows a market where the top three and top five players account for a meaningful portion of the market, creating both barriers and partnership opportunities for mid‑market vendors and new entrants.
What the report contains — practical deliverables
This is not an academic overview. The report is built for executives who need decision‑grade outputs in 30–90 days. Core deliverables include:
-
Top‑line market model with scenario capability — base, conservative and aggressive demand curves aligned to policy and technology adoption assumptions.
-
Regulatory navigator — a country‑by‑country checklist and timeline for Class II pathways, CE/MDR obligations, and common 510(k) predicates; includes a playbook for post‑approval surveillance and labeling strategy.
-
Commercial playbooks per end‑user archetype — targeted value propositions, pricing approaches and channel mixes for dental clinics, hospitals and DSOs (without disclosing granular market share tables in this preview).
-
M&A screening toolkit — size‑and‑fit matrices, synergy levers and break‑even horizon simulations to prioritize inorganic moves in 2026.
-
Competitive heat maps and capability matrices — R&D posture, manufacturing footprint, digital capabilities, and regulatory maturity for the leading suppliers to help identify partner‑or‑target lists quickly.
-
Clinical adoption index and ROI calculators — quantifies clinician adoption friction and models time‑to‑payback for investments in scanners, aligner workflows and adjunctive devices.
Competitive landscape — strategic implications for incumbents and challengers
The market is led by a mix of digitally native aligner specialists and established OEMs with broad orthodontic portfolios. Each archetype faces different strategic inflection points:
-
Digital aligner leaders: Firms that own the scanner‑to‑aligner value chain are well positioned to capture higher per‑case economics and recurring consumable revenue. Their near‑term priorities must be to defend IP and expand clinical indications while meeting rising regulatory expectations for treatment claims and software validation.
-
Legacy orthodontic OEMs: Companies with deep bracket, wire and appliance portfolios can leverage distribution scale and clinician relationships, but must invest aggressively in digital integration and aesthetic product lines to avoid margin erosion.
-
Component specialists and consumable suppliers: High‑performance archwire and accessory makers should pursue precision manufacturing partnerships and service bundles as device makers integrate more in‑house production.
Representative players and the strategic takeaways we profile in the report include:
-
Align Technology — continues to extend its aligner leadership through product clearances and adjacent attachments that increase clinical applicability; strategic focus should be on broadening indications and protecting software and manufacturing IP.
-
DENTSPLY SIRONA — leveraging both digital diagnostic assets and traditional product lines; recent partnerships in cleft care and the pause of certain DTC activities illustrate the trade‑offs between scale and regulatory exposure.
-
Envista, Institut Straumann and other established OEMs — competing on integrated solutions and channel reach; must balance investments between bracket/wire enhancements and digital treatment planning to maintain share.
-
Regional specialists and component makers — competitive edge lies in precision manufacturing and clinician support services; consolidation may accelerate as larger players seek supply chain resilience.
Recent developments that change the playbook
-
Regulatory milestones: FDA 510(k) clearances for new aligner attachments and AI‑enabled 3D diagnostic tools indicate regulators are increasingly comfortable with digital ecosystems — but expect stricter evidence requirements for new clinical claims.
-
Product innovations: New aesthetic bracket systems and adjunctive devices are narrowing the clinical gap between fixed and removable approaches, challenging the binary market segmentation that defined earlier strategic assumptions.
-
Reimbursement updates: CDT code revisions effective in 2026 will materially affect practice economics for complex orthodontic cases; early adopters who optimize coding capture incremental revenue and competitive pricing flexibility.
-
Direct‑to‑consumer dynamics: Recent suspensions and operational limits in DTC models underscore the regulatory and brand risk of bypassing clinical channels; companies must evaluate channel strategies that prioritize compliance and long‑term clinician partnerships.
Strategic recommendations for 2026
-
Prioritize regulatory readiness as a competitive moat: Integrate regulatory strategy into product roadmaps, clinical trials and marketing timelines to avoid launch delays and unanticipated label restrictions.
-
Invest in modular digital platforms: Interoperability with scanners, planning software and manufacturing partners reduces lock‑in risk and accelerates adoption among DSOs and hospital systems.
-
Design channel‑specific value propositions: Tailor pricing, financing and training programs to dental clinics versus DSOs and hospital networks; a single go‑to‑market approach will leave share on the table.
-
Conduct proactive reimbursement engagement: Map the 2026 CDT changes to product offerings and operational workflows, then pilot coding and billing flows with a subset of provider partners before full rollout.
-
Use M&A selectively to buy capability, not just revenue: Prioritize tuck‑ins that fill digital gaps, secure supply chains for critical components, or bring regulatory dossiers that shorten time‑to‑market.
How to use this report
Leaders should treat this report as both a strategic roadmap and a tactical toolkit. Use the scenario model to stress‑test product investments and the regulatory navigator to sequence clinical evidence generation. The M&A toolkit and competitive heat maps will expedite target identification and due diligence prioritization. For strategy teams preparing budgets, the ROI calculators quantify the trade‑off between CAPEX for digital enablement and expected lifetime revenue uplift.
Next steps
This preview highlights the depth of analysis and the judgment required to act confidently in 2026. To access the full segmentation tables, regional and application breakdowns, granular competitive models and downloadable spreadsheets that underpin the forecasts and playbooks, please visit the PW Consulting Orthodontic Aids Market report landing page.
For detailed analysis of this topic, please visit the official page: Orthodontic Aids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com