

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: CPE Antenna Market to Grow at 8.27% CAGR, Reaching USD 2,755.6 Million by 2032 as Asia‑Pacific and 5G FWA Lead Demand

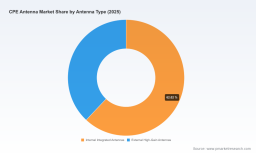
CPE Antenna Market 2026: Strategic Briefing for Executive Decision-Making
PW Consulting’s latest Cpe Antenna Market report is released as companies face a pivotal moment for fixed wireless access (FWA) and broadband gateway strategy. The global CPE antenna market — measured in USD million — expands from an estimated market base in 2025 to a materially larger industry by 2032, growing at a compound annual growth rate of 8.27% over the forecast window. This trajectory reflects both accelerated deployment of 5G FWA and iterative platform upgrades in Wi‑Fi and satellite broadband terminals. For leaders planning capital allocation, product roadmaps, or M&A activity in 2026, the report provides the context and practical tools to convert macro growth into defensible advantage.
Cpe Antenna Market
Why 2026 is a Strategic Inflection Point
The industry’s growth profile is clear: after a steady expansion through the early 2020s, the CPE antenna market scales meaningfully through the late 2020s as mid‑band spectrum densification and next‑generation Wi‑Fi upgrades converge with operators’ FWA rollouts. In dollar terms the market shows a significant uplift from our 2025 base and nearly doubles by the end of the forecast period — a dynamic that reshapes supplier economics, component supply chains, and product differentiation strategies.
Cpe Antenna Market
But growth alone is not the strategic story. Three concurrent forces make 2026 a decision year:
Cpe Antenna Market
- Spectrum reallocation and regulatory flux are redefining usable mid‑band capacity and the commercial incentives for deploying FWA at scale.
- Advanced antenna architectures — from embedded multi‑element indoor arrays to ruggedized outdoor high‑gain panels — are enabling new form factors and integration models that change unit economics and customer selection criteria.
- Competitive consolidation and expanded design wins by specialist antenna suppliers are altering the OEM playbook for outsourcing versus insourcing critical RF competencies.
Market Structure and Competitive Concentration
Market concentration metrics show a moderately concentrated landscape at the global level, with the top three players commanding a meaningful share and the top five extending that position. This concentration level signals that category leadership will continue to accrue to firms that pair antenna IP and system integration with scale manufacturing, channel reach, and service platforms. For potential entrants and incumbents alike, understanding supplier mix, cost-to-performance tradeoffs, and design‑win pipelines is essential to capture the projected CAGR without sacrificing margin.
Competitive Landscape: Who to Watch and Why
The competitive set spans integrated consumer gateway vendors, traditional RF and antenna specialists, and agile OEM/ODM manufacturers. PW Consulting’s qualitative benchmarking highlights the strategic positions of named market participants:
- Vantiva (France) — Pushing indoor performance with a proprietary multi‑element Indoor5G™ antenna family that integrates mid‑band boosters. Their approach targets spectrum efficiency and dense urban FWA use cases where indoor reception and carrier aggregation matter to end‑user QoS.
- ZTE Corporation (China) — Leveraging vertical integration and advanced AI-enabled antenna solutions across indoor and outdoor form factors. ZTE’s next‑gen FWA lineup demonstrates how operator partnerships and end‑to‑end system design accelerate time‑to‑market for 5G‑A CPE.
- Poynting (South Africa) — A specialist in high-performance outdoor enclosures and wideband coverage. Poynting’s IP and ruggedized designs are positioned for service providers deploying long‑reach FWA in challenging RF environments.
- TP‑Link (China) — A well‑established channel brand with focused high‑gain directional products for point‑to‑point and point‑to‑multipoint bridging, benefiting from distribution scale and well‑known consumer trust.
- Huawei (China) — Offering integrated CPE with flexible antenna options; leverages ecosystem depth to provide turnkey WTTx and FWA solutions in markets where regulatory and carrier relationships permit broad deployment.
- China-based OEMs (Kenbotong, Shenzhen Keesun, Ameison, VLG Tech, M.gear) — These suppliers form a competitive supply layer, offering a wide range of cost-optimized antenna designs and rapid OEM/ODM capabilities that support volume scaling for established brands.
- Airgain (USA) and Antenna Products Corporation (USA) — Focused on embedded antenna IP, gateway-centric solutions and higher‑performance commercial antennas; Airgain’s recent design wins for Wi‑Fi 7 gateways highlight the premium placed on advanced embedded designs in fiber‑broadband rollouts.
Recent market moves reinforce these positions: marquee product launches by tier‑one system integrators and design victories by embedded antenna specialists are shifting where value is created — toward early antenna design partnerships and multi‑year supply commitments.
Regulatory and Spectrum Dynamics: Roadmaps and Risks
Regulatory developments in major markets are a source of both opportunity and uncertainty. Policymaking around spectrum allocation and the regulatory classification of broadband services has accelerated, producing a mixed signal set that companies must navigate strategically.
- Spectrum repurposing initiatives that expand mid‑band availability materially change FWA economics by improving link budgets and enabling higher throughput per CPE — a direct enabler for higher‑performance antenna designs.
- At the same time, legal and administrative shifts in how broadband is regulated — including decisions that affect classification and oversight — introduce timing and compliance uncertainty for providers that rely heavily on CPE-based access models.
- For manufacturers and operators, this regulatory volatility means product windows, certification timelines, and procurement cycles may compress or lengthen unpredictably; scenario planning and regulatory engagement are therefore core to 2026 strategy.
What the PW Consulting Report Delivers: Practical, Actionable Intelligence
Our report is built to be operational. It is not a collection of passive market figures: it is a toolkit for teams charged with making 2026 investment choices. Key deliverables include:
- Comprehensive market sizing and a seven‑year forecast model (base year 2025), calibrated to macro deployments and technology adoption curves.
- Scenario analysis for alternative spectrum outcomes, with revenue and unit‑demand implications under conservative, baseline, and accelerated allocations.
- Competitive heat maps and supplier capability matrices that go beyond company names to assess technology readiness, manufacturing flexibility, and design‑win momentum.
- Procurement playbooks and supplier selection frameworks for OEMs and operators, including negotiation levers, volume‑price modelling, and risk mitigation strategies.
- Technical decision guides for product managers covering antenna architecture choices (embedded vs. external, high‑gain directional vs. wideband MIMO), testing protocols, and integration cost drivers.
- M&A and partnership scouting lists with quantified strategic fits, integration risks, and suggested diligence checklists.
- Regulatory impact matrices and engagement roadmaps tailored to North America, EMEA, and APAC decision-makers (sensitive to local legal conditions and spectrum timelines).
In keeping with the “trailer” principle, the report surface describes the directional impacts of subsegments and regional dynamics without publishing the full proprietary cross‑tabulations in this release. Clients receive the full dataset, interactive models, and scenario tools on the report portal.
How Executives Should Use This Intelligence in 2026
PW Consulting recommends a three‑track decision process for 2026 that links strategy to execution:
- Invest in antenna differentiation where it affects end‑user economics. Targeted R&D and key design‑in wins for mid‑band and multi‑band antenna systems generate stickiness with operators deploying FWA and premium broadband services.
- Secure multi‑year supply and design partnerships. Given concentration among top suppliers and the premium for validated antenna IP, locking in partnership agreements reduces time to market and hedges against component shortages.
- Adopt regulatory scenario planning as a board‑level discipline. Maintain a dynamic plan for certification, spectrum auction outcomes, and compliance pathways — and align procurement cadence to anticipated policy windows rather than optimistic deployment timetables.
For investors, the path to capture upside is to prioritize firms that demonstrate both technical antenna leadership and the ability to scale manufacturing without margin erosion. For operators, the priority is to favor suppliers that offer system‑level integration and measurable throughput improvements per CPE; these suppliers will shorten deployment schedules and improve customer economics.
Closing: Why This Report Matters for 2026 Decisions
The CPE antenna market’s projected expansion and the 8.27% CAGR are not abstract statistics — they are a roadmap for where capital, talent, and regulatory effort should flow in 2026. This is the year to convert roadmap into execution: secure spectrum‑aligned product platforms, elect strategic supplier partners, and lock in regulatory strategies that preserve deployment optionality.
PW Consulting’s Cpe Antenna Market report gives leaders the foresight and the operational instruments to make those choices with confidence. To access the full data tables, interactive forecast model, supplier scorecards, and the strategic playbooks described here, visit our report portal and download the executive package.
For detailed analysis of this topic, please visit the official page: Cpe Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com