

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Industrial Smart Helmet Market Poised to Surge to USD 2,058.16 Million by 2032, Backed by a 14.25% CAGR

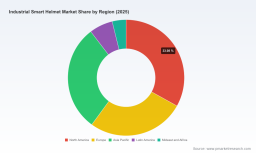
Industrial Smart Helmet Market: Strategic Imperatives for 2026
PW Consulting’s latest Industrial Smart Helmet Market Research (base year 2025) arrives at a pivotal inflection point for safety, productivity and digital infrastructure investments. The global market reached approximately USD 810.0 Million in 2025 and is forecast to expand at a 14.25% CAGR through the 2026–2032 horizon, exceeding USD 2.05 Billion by 2032. For executives preparing capital plans, vendor roadmaps and safety programs for 2026, this report serves as an operational playbook — synthesizing technology trajectories, supplier positioning, certification constraints, supply‑chain dynamics and the commercial levers that separate pilots from scale deployments.
Industrial Smart Helmet Market Research
Why this market matters to corporate decision-makers in 2026
-
Convergence of safety and operations: Smart helmets are no longer purely PPE. They act as edge nodes for situational awareness — streaming environmental sensors, biometric telemetry, real‑time location and media to centralized operations platforms. That convergence accelerates ROI calculations for safety investments and operational digitalization.
Industrial Smart Helmet Market Research -
Regulatory and insurance pressure: Enforcement trends (e.g., OSHA and equivalent bodies internationally) and insurer interest in demonstrable risk reduction are creating procurement pull — not just capex aesthetics but measurable incident reduction and compliance evidence.
Industrial Smart Helmet Market Research -
Technology arbitrage window: Rapid progress in 5G/edge AI, integrated AR, and intrinsically safe communications is reducing the technical barriers to enterprise adoption. First‑mover procurement decisions in 2026 will determine integration pathways for the next decade.
-
Supply‑chain and cost pragmatics: Volatility in raw material pricing (ABS, polycarbonate, EPS foam have risen materially since 2021) and the need for certified components makes sourcing and specification choices strategically important to control unit economics and long‑term TCO.
What PW Consulting’s report delivers — applied and action‑oriented
-
Board‑level summary and procurement playbook: executive highlights, ROI scenarios across common industrial use cases, and procurement timelines that translate market growth and technology maturity into capital budgeting guidance for 2026.
-
Vendor due‑diligence toolkit: standardized scorecards for technical compliance (intrinsic safety, ATEX/IECEx, ANSI/ISEA Z89.1), interoperability (APIs, RTLS compatibility) and enterprise integration readiness (cloud connectors, identity and device management).
-
Pilot‑to‑scale implementation guides: configuration patterns for mixed fleets (retrofit + integrated devices), data flows for incident management, and KPIs for safety, productivity and cost recovery that buyers must require in statements of work.
-
Risk and supply mapping: near‑term supply risks tied to raw material cost swings and certification lead times, plus mitigation options including dual sourcing, local inventory buffering and modular design choices that shorten replacement cycles.
-
Commercial frameworks: contracting templates and pricing models (hardware, software subscriptions, professional services) to align incentives between buyers and vendors and reduce hidden lifecycle costs.
Competitive landscape — patterns, not prescriptions
The market is structurally fragmented but moving toward platform consolidation: the three largest vendors together control a meaningful minority share while the top five approach near‑majority concentration, indicating both scale advantages and persistent niche innovation. Against that backdrop, corporate procurement strategies must balance scale vendors with specialist innovators that provide differentiated sensor suites or vertical deployments.
-
Guardio (Båstadgruppen) — Sweden: The Armet PRO illustrates a vendor strategy centered on deep safety validation. Integrated impact/fall detection, automatic emergency alerts, and brain‑protection features signal a product design that prioritizes life‑safety credentials for construction and heavy industry customers.
-
iSmarch (collaboration with VCT InSite) — China/UAE region: Emphasizes highly configurable IoT platforms and has demonstrated capability on large, complex sites. Their solar‑assisted options and localized deployments reflect a vendor play that caters to energy‑intensive projects and environments with constrained power logistics.
-
Grandtime Tech — China: With a 5G‑first helmet (GH01), Grandtime is betting on ultra‑low latency connectivity and AI processing at the edge. This firm represents suppliers that are pushing advanced connectivity to unlock AR/remote expert and high‑bandwidth telemetry use cases.
-
Henan Zhong An — China: Focused on gas detection and intrinsically industrial sensor suites, illustrating the enduring need for application‑specific helmets in mining and petrochemical operations where atmospheric monitoring is mission‑critical.
-
viAct.ai — Hong Kong/global: A pure‑software plus sensor integrator that demonstrates the shift toward AI analytics for proactive alerts, pattern detection and compliance scoring across distributed worksites.
-
Guardhat (Aatmunn platform), MSA Safety, RealWear, Trimble — US and global players: These firms map to different strategic plays — platform (Guardhat/Aatmunn), legacy head‑protection leaders moving into connected devices (MSA), hands‑free AR compute OEMs (RealWear) and enterprise mixed‑reality integrators (Trimble). Their product introductions and certifications create interoperability pressures and procurement choices for large enterprises.
Recent market momentum and its implications
-
Product cadence: Between late 2024 and 2025, several suppliers launched new models or announced platform upgrades, accelerating feature parity around impact detection, brain‑protection technologies and high‑availability communications. Buyers should anticipate faster obsolescence of entry‑level devices and plan upgrade windows accordingly.
-
Certification as a market entry barrier: A growing number of models carry hazardous‑location certifications (ATEX/IECEx/CSA), making certified device supply an important gating factor for deployments in oil & gas, mining and chemical sectors.
-
Cost pressure from materials: Raw material cost increases since 2021 have tightened margins and pushed some vendors to revisit material choices and modular design to control price volatility. Procurement conversations in 2026 must include material clauses and acceptable substitution bands.
Strategic recommendations for 2026 decision cycles
-
Run targeted pilots that mirror scale conditions: Design pilots with mixed environmental stresses (radio occlusion, explosive atmospheres, prolonged wear), and measure not just uptake but integration metrics — API reliability, latency under load, and operations staff workflows.
-
Prioritize certified platforms where safety liability is highest: For hazardous industries, insist on intrinsic safety and recognized certifications as contractual minimums. Certification reduces downstream compliance risk and accelerates insurer engagement.
-
Insist on open APIs and lifecycle roadmaps: Locking into proprietary stacks reduces optionality. Require device management, OTA update provisions and data export abilities in RFPs so IT can integrate helmet streams into EAM, HSE and ERP systems.
-
Model total cost of ownership across three horizons: procurement, one‑year operating, and three‑to‑five‑year lifecycle costs, including consumables, certification renewals, and firmware maintenance. High short‑term discounts may hide longer amortized costs.
-
Mitigate raw material exposure: Negotiate fixed windows, dual sourcing and supplier roadmaps for material substitution. Consider longer‑lead buys where certification lead times are significant.
-
Establish data governance and privacy guardrails early: Helmet telemetry is sensitive (location, health signals). Define ownership, retention and access policies before roll‑out to avoid operational and regulatory friction.
-
Plan for consolidation and partner thoughtfully: Expect M&A and platform consolidation to accelerate. Evaluate partners not only for product fit but for platform openness and build/partner ecosystems you can leverage if your supplier is acquired.
Intended audience and next steps
This analysis is designed for C‑level decision makers, head of operations, HSE leaders, procurement chiefs and enterprise architects tasked with translating growth forecasts into executable 2026 plans. The report’s granular modules — including regional deployment playbooks, vertical use‑case templates, vendor scorecards and a buyer’s checklist — are intentionally consolidated in the full study to preserve competitive value for subscribers.
For organizations preparing capital allocations and vendor engagements in 2026, the PW Consulting report provides the empirical basis and pragmatic templates to make defensible choices. To access the full segmentation, supplier benchmarking, pricing matrices and downloadable RFP appendices, visit the Industrial Smart Helmet Market Research page on our website.
For detailed analysis of this topic, please visit the official page: Industrial Smart Helmet Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com