

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Robust 5.28% CAGR for Global Oil & Gas Storage & Transportation Market (2026–2032)

PW Consulting: Strategic Preview — Oil & Gas Storage and Transportation Market Outlook 2026
Executive preview
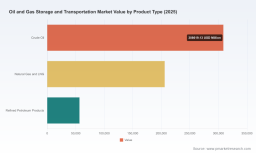
As energy market volatility enters a new phase in 2026, decisions taken this year will disproportionately shape corporate performance across the next business cycle. PW Consulting’s latest Oil and Gas Storage and Transportation Market report—anchored on 2025 as the base year—provides a practice-oriented strategic compass for executives, investors, and policy teams. The global market reached approximately USD 571.25 billion in 2025 and is on a path to expand at a compound annual growth rate (CAGR) of roughly 5.3% across the 2026–2032 forecast window. This growth trajectory masks significant strategic inflection points: reserve management, infrastructure resiliency, regulatory transitions, and the gradual convergence of hydrocarbon logistics with low‑carbon transport and storage needs.
Oil And Gas Storage And Transportation Market
Why 2026 is a pivotal decision year
-
Inventory and supply dynamics have reset. Global observed oil stocks climbed to their highest levels since early 2021, while episodic draws and floating storage shifts underline the need for adaptive storage strategies. Tactical portfolio adjustments in 2026—whether to expand commercial buffer capacity, repurpose assets for refined product flows, or prioritize strategic reserve contracts—will alter revenue and risk profiles into the next decade.
Oil And Gas Storage And Transportation Market -
Capital allocation trade-offs are acute. With the sector growing at ~5.3% CAGR, greener LNG and CCUS-linked transport options are increasingly competitive against brownfield storage upgrades. Boards must weigh near-term throughput gains against longer-term asset optionality.
Oil And Gas Storage And Transportation Market -
Regulatory and infrastructure signals are converging. Large-scale new-build pipeline and export projects approaching operation, alongside public-sector strategic exchanges of reserves, create timing windows for off-take agreements, tolling contracts, and terminal reconfiguration.
What the report delivers — an operator’s playbook
PW Consulting’s report is structured for use in boardrooms and deal teams, not just for reading. Key operational and strategic deliverables include:
-
Scenario-based demand and utilization models that stress-test capacity under differing geopolitical, macroeconomic, and climate-policy assumptions—each model accompanied by sensitivity matrices you can apply to your own asset portfolio.
-
Investment decision frameworks and prioritization tools that translate market growth assumptions into CAPEX vs. OPEX trade-offs, break‑even throughput thresholds, and staged expansion pathways.
-
Practical due‑diligence checklists for terminal acquisitions, pipeline tie-ins, and storage retrofits—covering regulatory approvals, environmental permits, berth and pipeline compatibility, and HSE standards.
-
Commercial negotiation playbooks: standardized contract clauses, risk allocation templates for exchange and emergency‑draw agreements with governments and national oil companies, and guidance on structuring tolling arrangements that preserve optionality.
-
Decarbonization and asset repurposing roadmaps, including technical and policy considerations for converting hydrocarbon corridors to CO2 transport and storage networks—an increasingly material optionality for mid- and late-life assets.
Market dynamics and risk vectors
Our analysis integrates the latest market signals. In early 2026, global observed oil inventories rose to multi-year highs, while subsequent monthly draws and shifts into floating storage highlight how supply shocks and shipping constraints can rapidly reallocate value across terminals and transit routes. Government actions—such as emergency exchanges of strategic reserves—create both short-term throughput volatility and medium-term contractual opportunities for storage operators. In parallel, projected declines in on-road transportation energy demand under more aggressive vehicle emissions standards raise structural questions for refined-products logistics over the 2030s, intensifying the need for diversification.
Geopolitical and infrastructure developments add another layer of complexity. New offshore pipeline systems and LNG export pathways coming online around 2026 will both alleviate regional bottlenecks and reconfigure competitive corridors. For firms with flexible storage and intermodal capabilities, these shifts present upside; for operators with single-purpose assets, they increase exposure to throughput declines.
Investment themes and corporate responses
-
Flexible, convertible capacity wins. Investment programs that prioritize modular tanks, multiproduct berths, and interoperable pipeline connections score higher on scenario value because they can be repurposed for changing cargo mixes and carbon transport applications.
-
Strategic partnerships accelerate access. Joint ventures with national oil companies and pipeline operators, and commercial anchor agreements with trading houses, mitigate utilization risk while preserving upside from market recoveries.
-
Digital operations and predictive maintenance drive margin expansion. The report quantifies efficiency levers from digital twin deployment, automated leak detection, and condition-based tank maintenance that materially lower OPEX and environmental risk exposure.
-
Decarbonization optionality is a value driver. Existing transport and storage corridors can form the backbone of carbon transport networks; our modelling maps the pathway from hydrocarbon logistics to co‑located CO2 transport and storage that could serve both industrial emitters and regional climate objectives.
Competitive landscape — strategic profiles and implications
The market remains fragmented, with a mix of global independent operators, integrated midstream majors, national oil companies, and specialized terminal owners. Our competitive analysis synthesizes organizational positioning, growth intent, and likely tactical moves through 2026.
-
Royal Vopak N.V. — As the world’s largest independent tank storage operator, Vopak’s global terminal footprint positions it to capture arbitrage and trading-related storage demand. Strategic implication: partnerships with trading houses and digital inventory services will extend trading-linked revenue streams beyond traditional lease models.
-
Kinder Morgan, Inc. — With a dense North American pipeline and storage network, Kinder Morgan is optimized for mid-continent throughput. Strategic implication: portfolio optimization will likely focus on hydrogen-ready repurposing and NGL handling to offset refined-products structural decline.
-
Enbridge Inc. — Operating one of the longest liquids transport systems, Enbridge’s integrated model supports scale advantages in long-haul logistics. Strategic implication: expect contractual plays tying pipeline tariffs to terminal capacity, with careful regulatory engagement on tolling reforms.
-
Enterprise Products Partners L.P. and Energy Transfer LP — Gulf Coast integration of storage and export infrastructure provides optionality into global markets. Strategic implication: these players are well placed to monetize export arbitrage and midstream services for petrochemical feedstocks.
-
National champions (e.g., Saudi Aramco, CNPC, ADNOC Terminals) — Their control of large tank farms and port-linked storage creates state-backed flexibility in both domestic security and export strategy. Strategic implication: international partners may seek capacity floor agreements and capacity-as-a-service structures to access strategic volumes.
-
Independent terminal specialists (e.g., Oiltanking, VTTI, Buckeye Partners) — Focused on niche product mixes and strategic locations, they can react more quickly to regional demand shifts. Strategic implication: M&A activity and bolt-on transactions are likely to remain a key consolidation vector.
Recent developments shaping near-term strategy
Our report contextualizes three recent developments with direct implications for 2026 strategy: (1) government‑level strategic petroleum reserve exchanges that temporarily alter demand patterns and create short-duration storage opportunities; (2) major contract awards for field development and pipeline construction that expand export and domestic flows; and (3) sizable investment programs in unconventional gas and NGL fractionation that will require integrated storage and export capacity. Together, these events compress windows for deal structuring and highlight the premium on readiness—commercial teams that can offer rapid capacity, flexible terms, and integrated logistics will capture disproportionate value.
Operational resilience and regulatory watchlist
Operational resilience remains a differentiator. The report provides a regulatory and compliance tracker that maps known and emerging requirements across major jurisdictions, and quantifies potential cost impacts of tighter emissions and safety standards. It also outlines operational playbooks for managing inventory swings, from accelerated turn strategies during draws to capacity-stacking approaches when inventories accumulate. For 2026 planning, firms should prioritize regulatory engagement, stress-test contract provisions for force majeure and emergency exchanges, and invest in visibility systems that lower response times.
How executives should use this report in 2026
-
Use the scenario toolset to test 2026 CAPEX allocations against downside throughput cases and upside export scenarios.
-
Apply the contractual playbooks to renegotiate term sheets with counterparties, anchoring on quantifiable service tiers and outage compensations.
-
Map your assets against the decarbonization and CO2‑transport optionality overlays to identify candidate corridors for repurposing or co‑investment.
-
Prioritize a short list of partnership targets drawn from the competitive landscape analysis to secure offtake, throughput, or financing advantages within defined timing windows.
Next steps and where to find the full intelligence
This article is an executive preview designed to demonstrate the report’s strategic value while preserving proprietary segmentation analytics and granular forecasts. For transaction-ready data tables, regional and product‑level projections, and the full suite of decision tools (including model templates and contract clause libraries), please consult the PW Consulting report landing page. Our team is available to run tailored workshops, portfolio stress tests, and M&A screening sessions to translate the findings into executable plans for your organization.
PW Consulting remains committed to equipping leaders with the operational foresight and market intelligence required to convert 2026 disruption into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Oil And Gas Storage And Transportation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com