

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electronic Grade Adhesives Market to Hit USD 9.8 Billion by 2032 at 6.32% CAGR, Led by Asia Pacific’s USD 3.52 Billion Share

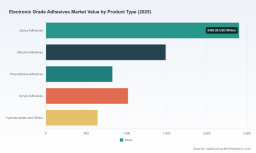
Electronic Grade Adhesives Market: Strategic Outlook for 2026 — A PW Consulting Preview
Executive Summary
As the electronics ecosystem accelerates into a new wave of miniaturization, electrification and system-level thermal challenges, electronic grade adhesives have moved from a supporting role to a strategic enabler. PW Consulting’s latest market study — covering historical performance from 2020–2025 and a forecast window through 2032 — projects a steady expansion driven by advanced semiconductor packaging, higher-reliability consumer devices, and automotive electrification. The market that stood at approximately USD 6.4 billion in 2025 is modeled to grow at a compound annual growth rate (CAGR) of 6.32% across the 2026–2032 forecasting horizon, approaching roughly USD 9.8 billion by 2032. This release is intended to arm executives with the directional intelligence needed for decisive 2026 planning while reserving the granular, segment-specific detail for the full report.
Electronic Grade Adhesives Market
Why This Matters for 2026 Decision-Makers
-
Budget allocation and capex timing — With a multi-year structural upswing, procurement and manufacturing leaders must align capacity investments and raw-material contracts to absorb cyclical and secular demand without overpaying for volatility-driven supply.
Electronic Grade Adhesives Market -
Product roadmap prioritization — Adhesive chemistries now materially influence product differentiation: thermal interface performance, low-outgassing for optical subsystems, and reliability under harsh thermal cycling are product attributes that hinge on formulation choices.
Electronic Grade Adhesives Market -
Supply-chain resilience — The convergence of feedstock volatility, regulatory reclassifications, and trade-policy developments requires a more active hedging and supplier diversification stance in 2026.
Market Trajectory — What the Macros Tell Us
Our model tracks a rebound and steady expansion after the mid-decade recalibration: the market rose from the low‑mid‑billions during the early 2020s into the mid‑2020s and continues on a solid growth path through 2032 under base-case assumptions. The CAGR of 6.32% reflects sustained demand across semiconductor packaging, PCB assembly, and a widening set of thermal and structural use-cases in automotive and industrial electronics. Importantly, market concentration remains meaningful — the top three suppliers account for a little over one-third of the market, while the top five approach roughly half — creating a competitive environment in which scale and application expertise both confer advantage.
Segment Dynamics (High-Level)
PW Consulting’s full analysis drills into product-chemistry and application vectors — epoxy systems, silicone-based solutions, light-curable adhesives, and advanced thermal interface materials — and how each maps to packaging trends such as fine-pitch die attach, underfill innovations, and potting for harsh environments. Rather than enumerating segment shares here, we summarize the directional drivers you must consider:
-
Technology pull: Advanced packaging (including fan-out, 2.5D/3D integration) is increasing demand for high‑reliability, low-impurity underfills and die-attach systems.
-
Thermal & electrical management: Higher power densities are pushing adoption of thermally conductive adhesives and integrated gap fillers as system-level thermal strategies.
-
Process and throughput: Light‑curable and fast‑cure chemistries are gaining traction where cycle time and localized cure control reduce total cost of ownership on high-volume lines.
-
Compliance-driven formulation change: Regulatory pressure and REACH-driven classifications are accelerating migration toward halogen‑free and low‑BPA epoxy alternatives in electronic-grade formulations.
Supply-Chain and Cost Pressures
Raw-material dynamics are the single most important near-term margin risk for adhesive manufacturers and their OEM customers. Feedstock volatility — notably in epoxy precursors — has produced mixed but generally firmer pricing trends, influenced by geopolitical supply constraints and shifts in demand from adjacent industries (e.g., electrical laminates). In parallel, regulatory classification changes in key regions are prompting reformulation efforts that can add near-term substitution cost and require requalification cycles. For procurement and finance leaders, this translates into three practical risks to manage in 2026: price shocks, qualification lead-times for alternative formulations, and concentration in critical feedstock suppliers.
Competitive Landscape — What We Found
The competitive map is a mix of global chemical majors, specialty adhesive companies, and fast‑growing niche suppliers focused on semiconductor packaging materials. Our benchmarking examines product breadth, application engineering capabilities, geographic manufacturing footprint, and recent strategic moves. Highlights include:
-
Established majors with breadth (e.g., Henkel, 3M, Dow): These players combine global manufacturing scale with deep application engineering centres, positioning them to serve broad electronics OEM portfolios and capitalize on rising thermal management demand.
-
Specialty innovators (e.g., Dymax, DELO, YINCAE): Light‑curable adhesives, precision dispensed systems, and packaging-focused underfills are areas where specialist technology providers are outpacing generalists in performance-per-cost for select applications.
-
Silicone and thermal specialists (e.g., Momentive, Shin‑Etsu, Wacker): Firms with advanced silicone chemistries and thermally conductive systems are capturing requirements tied to displays, sensors, and power electronics that require primerless adhesion and low volatile content.
-
M&A and capacity plays: Recent facility investments and regional technical center expansions point to an industry consolidating around application engineering and local production to meet speed-to-market and qualification demands.
Notable Industry Developments (Recent)
-
Facility and technical-centre investments by leading suppliers to accelerate materials characterization and shorten customer qualification cycles.
-
Strategic partnerships and distribution agreements to expand product availability for high-demand one‑part epoxies and fast‑cure formulations.
-
Trade- and regulation-related rulings that have marginally altered regional supply flows and incentivized some manufacturers to accelerate local sourcing or alternative feedstock strategies.
Risks, Uncertainties, and Scenario Considerations
Our scenario work identifies three near-term states that materially change strategy in 2026:
-
Base case — steady growth with episodic feedstock volatility: Continue investment in process efficiency and application engineering; focus on supplier diversification for critical feedstocks.
-
Upside case — accelerated packaging adoption and rapid EV electronics content growth: Prioritize capacity expansion and form strategic OEM partnerships for qualification exclusivity.
-
Downside case — sharper feedstock price shocks or protectionist trade measures: Deploy hedging strategies, increase inventory of validated alternative formulations, and revisit contractual pass-through mechanisms.
Practical Recommendations for 2026
-
Procurement: Implement a two-tier hedging and dual-sourcing program for critical resin feedstocks; renegotiate long-term offtake where appropriate to lock favorable economics.
-
R&D/Product: Accelerate low‑impurity and halogen‑free epoxy initiatives, and prioritize light‑curable systems for high‑throughput lines to reduce cycle time and scrap risk.
-
Manufacturing & Capex: Favor modular, scalable production cells that can switch between chemistries with minimal requalification risk; prioritize local technical support hubs to shorten OEM approval timelines.
-
Commercial: Market differentiation should shift from commodity price to system‑level performance guarantees — e.g., thermal resistance over lifecycle, validated drop performance, and cross‑platform reliability data.
-
M&A & Partnerships: Seek bolt-on acquisitions for niche chemistries and consider co‑development agreements with semiconductor packaging consortiums to secure early access to next‑generation packages.
What PW Consulting’s Full Report Contains (Practical Deliverables)
The complete market report provides actionable tools designed for immediate executive use, including but not limited to:
-
Differentiated demand models by adhesive family and application, with sensitivity testing for raw‑material and policy shocks.
-
Supplier scorecards that evaluate engineering depth, qualification velocity, geographic resilience, and cost-to-serve.
-
Commercial playbooks for OEMs and CMs detailing negotiation levers, sample contractual clauses for pass‑through, and qualification timeline templates.
-
Technology roadmaps linking packaging trends to adhesive requirements and recommended R&D investment sequencing.
-
Deal pipeline and M&A heatmap highlighting targets and valuation comps for strategic and financial buyers.
Conclusion — The Strategic Imperative for 2026
In 2026, electronic-grade adhesives will no longer be an inert line item on the BOM: they will be recognized as a lever for thermal management, reliability, and form-factor innovation. PW Consulting’s topline forecasts and concentration analysis show an industry growing predictably, but with enough structural risk (feedstock, regulation, and supply concentration) to mandate proactive strategy. Leaders who align procurement, R&D, and commercial strategies now — and who leverage supplier engineering partnerships — will convert the market’s predictable expansion into a sustainable competitive edge.
Next Steps
For procurement directors, R&D heads, and corporate strategists preparing budgets and roadmaps for 2026, PW Consulting’s full Electronic Grade Adhesives Market report contains the validated scenarios, supplier assessments, and actionable playbooks to inform immediate decisions. To access the complete dataset, segmentation detail, and supplier benchmarking tools referenced in this preview, please visit our report page.
For detailed analysis of this topic, please visit the official page: Electronic Grade Adhesives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com