

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 25G Optical Chip Market Poised for Strong Growth — 7.5% CAGR Through 2032

PW Consulting: Strategic Outlook — 25G Optical Chip Market Report (2026 Guidance)
Executive summary
As organizations plan capital and product decisions for 2026, the 25G optical chip market presents a clear but nuanced growth path. Our new market model — anchored on a 2025 base year and spanning historical performance from 2020–2025 with forecasts through 2026–2032 — shows a sustained compound annual growth rate (CAGR) of 7.5%. Measured in USD (Million), the market moves from a firm base in 2025 to a materially larger opportunity by the end of the forecast window. This briefing summarizes the strategic implications that PW Consulting believes senior executives must weigh when shaping product roadmaps, sourcing strategies, and partnership models for the coming 18–36 months.
25G Optical Chip Market
Why 25G matters now: growth drivers and tempo
25G optical chips are at the intersection of several structural shifts: accelerated cloud and edge infrastructure expansion, 5G fronthaul/midhaul upgrades, and an ongoing refresh cycle in enterprise and carrier networks seeking higher port density and energy efficiency. These secular drivers underpin the steady growth reflected in our model, which projects notable expansion from the 2025 baseline over the 2026–2032 horizon at a 7.5% CAGR.
25G Optical Chip Market
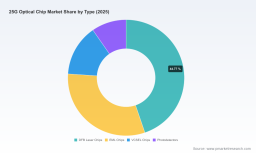
Importantly, this is not a one-dimensional upgrade story. The market’s momentum is being modulated by technology choices (DFB, EML, VCSEL, photodetector variants), module architectures, and ecosystem adoption curves. These dynamics create differentiated pockets of margin and capacity constraints that will determine winners and laggards through 2026 and beyond.
25G Optical Chip Market
Market trajectory: a strategic snapshot
- Base and trajectory: Using 2025 as the base year, our model projects clear expansion through 2032, with the aggregate market measured in USD (Million) increasing materially by the end of the forecast period. This macro view establishes the size and growth runway firms should use when allocating R&D, capex, and commercial resources for 2026 decisions.
- Concentration and competitive tension: The market is moderately concentrated — a handful of suppliers command outsized influence, but there remains substantive room for regional and technology-specialist entrants. That balance favors strategic collaboration, selective vertical integration, and targeted M&A as practical near-term levers.
- Technology mix evolution: While multiple device types co-exist, adoption patterns are being shaped by cost, power, reach, and integration complexity. Suppliers that can simultaneously address performance and total cost of ownership will win design slots in next-generation modules.
Competitive landscape — implications for 2026 strategy
Our competitive scan synthesizes public profiles, product roadmaps, and recent commercial activity to map where competitive advantage is forming:
- MACOM (Lowell, Massachusetts) — Strong positioning with 25G DFB laser diodes optimized for direct modulation and uncooled operation, targeting 5G fronthaul and data center applications. MACOM’s emphasis on field-ready component robustness makes it a candidate supplier for operators prioritizing reliability and thermal simplicity.
- Lumentum Operations LLC (San Jose) — Focused on InP EMLs and DFB lasers with integrated wafer-foundry capabilities. Their vertical manufacturing footprint reduces supply-chain friction for high-performance parts and supports rapid qualification cycles for hyperscalers and telecom OEMs.
- Broadcom Inc. (San Jose) — A major systems-ecosystem player providing both VCSEL and other laser technologies for high-speed optical links. Broadcom’s channel strength and integration into networking platforms represent a high barrier for component-only suppliers seeking system-level adoption.
- Coherent Corp. (Saxonburg, Pennsylvania) — With legacy strengths in transceivers and lasers, Coherent’s portfolio is oriented toward telco and datacom applications that require mature manufacturability and lifecycle support.
- NEC Corporation (Tokyo) — Active product launches in 2025 (notably extended-reach and BiDi 25G SFP28 transceivers) signal a strategy to address upgrade paths from 10G while minimizing power and fiber rework for carriers.
- China-based suppliers (Accelink, InnoLight, GLSUN) — These players provide competitive cost structures and fast-turn transceiver capability. Their presence is especially relevant for large-volume data center and regional carrier markets where total landed cost and supply proximity matter.
Recent visible activity — from NEC’s 2025 extended-reach SFP launches to MACOM’s OFC showcase — underscores the competitive emphasis on enabling upgrades with minimal systems disruption. For buyers, this means more design alternatives but also a need for tighter qualification discipline.
Supply chain realities and systemic risks
Two supply-side realities will materially affect commercial decisions in 2026:
- Capacity utilization and backlog: Leading factories producing 25G EML and continuous-wave lasers are operating at high utilization; some suppliers report multi-year backlogs for specific device classes. This reduces buyers’ flexibility and elevates the value of secure supply agreements, dual-sourcing, and co-investment in capacity.
- Bottlenecks beyond chips: High-speed module production is constrained not only by die supply but by precision optical subcomponents and substrate availability. These non-chip bottlenecks can create asymmetric lead times that make nominal chip availability irrelevant without coordinated module-level planning.
Overlaying these operational constraints are geopolitical and regulatory pressures. Heightened export controls and regional trade frictions are increasing sourcing complexity and premiumizing localized assembly and advanced packaging capabilities. At the same time, standardization work (including OIF interoperability efforts) is reducing integration risk for buyers but accelerating the obsolescence cycle for legacy parts.
What PW Consulting’s report delivers — practical elements for 2026 action
The full PW Consulting report is designed as a decision-grade toolkit for executives and strategy teams. Key deliverables include:
- Actionable market model: A consolidated top-line model (USD, reporting in Millions) with historical context (2020–2025) and a detailed forecast through 2032, reflecting the 7.5% CAGR scenario and alternate demand scenarios for sensitivity testing.
- Supplier scorecards: Qualitative and operational KPIs covering capacity, lead times, technology maturity, and qualification risk to support sourcing and partner selection without needing to re-run time-consuming vendor audits.
- Technology roadmaps and migration matrices: Comparative analysis of DFB, EML, VCSEL and photodetector trajectories, highlighting where performance, cost, and power trade-offs favor incremental upgrades versus platform shifts.
- Commercial playbooks: Negotiation levers, contract structures, and inventory strategies tailored to the current supply tightness and to protect margins in 2026 procurement cycles.
- Scenario-based investment cases: Short-form and extended investment memos for capex, JV, or M&A options tied to realistic payback and integration timelines in the 2026–2028 window.
The report is intentionally structured to be operational: downloadable templates, checklist-driven supplier due diligence, and a short-list of strategic experiments that procurement and product leaders can implement quickly to reduce execution risk.
Strategic recommendations for executives planning 2026 actions
- Lock in supply where it matters: Prioritize long-lead components and secure multi-year offtake or capacity carve-outs with key suppliers. Use staged commitments to balance flexibility and allocation priority.
- Adopt a hybrid sourcing posture: Combine global tier-1 suppliers for performance-critical parts with regional low-cost producers for volume, but enforce common qualification standards to avoid field reliability variance.
- Invest selectively in packaging and test capability: Given bottlenecks at the module level, consider co-investment or partner-based approaches to secure advanced packaging capacity rather than relying on spot market access.
- Engage in standards and interoperability efforts: Participation in industry forums reduces integration risk, shortens qualification cycles, and positions firms to influence interface choices that can lower system cost.
- Pursue targeted M&A or JV opportunities: Market concentration means acquisitions can quickly expand capability and customer access, but focus on deals that close meaningful supply or technology gaps without protracted integration costs.
- Stress-test product roadmaps against supply constraints: Scenario plan for lead-time shocks and create modular line cards that allow component substitution without extensive requalification.
How to use the report in 2026 planning
Use our report as the factual backbone for three central 2026 activities: (1) Capex prioritization and supplier contracting cycles; (2) Product roadmap deltas tied to supply and cost scenarios; and (3) M&A/JV option screening calibrated to market concentration and capacity dynamics. The combination of the top-line market model (USD, Millions) and the operational playbooks enables rapid, evidence-based decisions while preserving optionality and risk controls.
Closing note — a preview, not the full map
Packed with proprietary market modeling, supplier benchmarking, and ready-to-execute commercial templates, PW Consulting’s 25G Optical Chip Market Report is tailored to executives who must make high-stakes decisions in 2026. This briefing intentionally omits granular segment tables and certain proprietary splits to preserve the analytical integrity of the full report — and to invite deeper engagement from teams that need the complete dataset and executable appendices.
To obtain the full report, including the detailed market tables, sensitivity scenarios, and vendor KPI sheets needed to operationalize the recommendations above, visit PW Consulting’s report access page or contact your assigned engagement lead to schedule a briefing and license the dataset.
For detailed analysis of this topic, please visit the official page: 25G Optical Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com