

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 5.51% CAGR for Special Electronic Chemicals in the Photoresist Market Through 2032

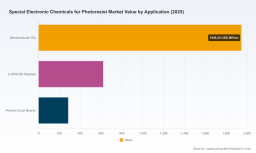
Special Electronic Chemicals for Photoresist Market — Strategic Preview for 2026 Decision-Makers
As semiconductor roadmaps accelerate toward denser nodes and more complex packaging, the market for special electronic chemicals used in photoresists has evolved from a niche materials sector into a strategic bottleneck for advanced manufacturing. PW Consulting’s new Special Electronic Chemicals For Photoresist Market report (base year 2025) synthesizes multi-year historical performance and forward-looking forecasts to provide executives with the decision-grade intelligence needed for 2026 planning. The global market grew materially during the last half-decade and, with a compounded annual growth rate of 5.51% in our forecast horizon, is positioned to exceed the USD mid-single-thousand million mark by the early 2030s. This briefing outlines the report’s strategic value while leaving the granular subsegment datasets gated for subscribers.
Special Electronic Chemicals For Photoresist Market
Why this market matters in 2026
- Photoresist chemistries and the supporting high-purity electronic chemicals (solvents, photoacid generators, additives and resins) sit at the intersection of process control, yield, and node enablement. Small formulation or purity differences can translate into outsized yield impacts at advanced nodes.
- Supply-side concentration and recent capacity moves by major incumbents mean procurement and capacity-planning choices across 2026 will have immediate operational consequences.
- Regulatory shifts — particularly evolving PFAS oversight at federal and state levels — are introducing compliance and reformulation risk that affects sourcing, cost, and time-to-qualified supply.
High-level market context (what the headline numbers mean)
From 2020 through 2025 the market demonstrated steady expansion, reflecting investments in semiconductor and advanced display capacity worldwide. Our base-year assessment (2025) places the market at approximately USD 2.85 billion, with a modeled progression to more than USD 4.1 billion by 2032 under the central-case forecast. The underlying CAGR of 5.51% captures continued demand from semiconductors and displays, incremental adoption of next-generation lithography chemistries, and periodic inflections from capacity expansions and supply rebalancing. These totals represent the aggregated market for specialty photoresist chemistries and their associated high-purity electronic chemicals — the numbers that CFOs and strategy leaders will use to size capex, inventory, and partnership decisions in 2026.
Special Electronic Chemicals For Photoresist Market
Market dynamics and supply-side pressure points
- Technology-driven purity requirements: Advanced lithography and sub-10 nm processes impose extremely tight impurity ceilings. Buyers must qualify solvents, polymer resins, and PAGs to sub-ppm impurity levels. This tough technical bar increases switching costs and raises the commercial value of qualified suppliers.
- Upstream raw material volatility: Specialty monomers, fluorochemicals, and high-grade solvents are often produced in limited geographic pockets. Even modest disruptions can cascade into allocation and pricing stress for fabs ramping new node programs.
- Concentration and capacity plays: The market exhibits significant concentration among a handful of global suppliers. Recent strategic moves — greenfield land acquisitions, JV formations, and completed capacity expansions — indicate incumbents are positioning for multi-year demand growth while seeking to protect margin and limit technology leakage.
- Regulatory complexity as a commercial variable: PFAS-related rulemaking and state-level restrictions are not theoretical — they change product roadmaps, trigger reformulation programs, and can alter supplier eligibility for certain customers. Compliance readiness is a procurement imperative in 2026.
Competitive landscape — what the shortlist of leaders signals
The sector is dominated by a mix of legacy specialty chemical conglomerates and focused photoresist specialists. Market leadership combines deep materials know-how, proprietary polymer chemistry, and long qualification cycles with premier OEMs. Key strategic behaviors observed across leading players include: accelerated capacity build-outs in lower-risk jurisdictions, localized production partnerships to shorten qualification timelines, and expanded investments in fluorine-free and sustainability-oriented chemistries to mitigate regulatory exposure.
Special Electronic Chemicals For Photoresist Market
- Tokyo Ohka Kogyo (TOK): Demonstrates continued commitment to capacity scale and long-cycle strategic planning through new site acquisitions and multi-year vision planning. Their capital footprint is a signal to customers and competitors that supply stability is a priority.
- JSR Corporation: Moving toward regionalized, advanced-photoresist production via joint ventures reflects a playbook centered on speed-to-qualification for hyperscalers and foundries; localization reduces logistical and lead-time friction for key customers.
- Shin-Etsu, FUJIFILM, DuPont, Merck, and Sumitomo: These incumbents combine broad portfolios with targeted R&D bets (EUV, ArF immersion, non-fluorinated chemistries), creating a layered competitive set where technology differentiation and supply reliability jointly determine commercial wins.
- Specialized and regional players: A cohort of small- and mid-cap suppliers continue to serve niche applications and PCB/display markets; they can be acquisition targets for larger firms seeking specific IP or flexible capacity.
Collectively, the top-tier firms capture a significant share of the market — a structural reality that shapes negotiation leverage, qualification timelines, and M&A opportunities. Our concentration analysis indicates that three- to five-firm clusters command a majority of market volumes, reinforcing the oligopolistic characteristics of the sector.
Regulation and risk: a strategic priority, not a compliance footnote
- PFAS evaluation and potential restrictions are actively shaping product roadmaps. Procurement and R&D leaders must align on a dual-track approach: defend existing formulations where permissible while accelerating alternative chemistries to hedge regulatory outcomes.
- State-level reporting and phased bans create a patchwork compliance landscape for multinational suppliers. Contract terms, audit clauses, and liability allocations require retooling to avoid downstream supply disruptions.
- Environmental, social and governance (ESG) expectations are tightening. Buyers increasingly demand supplier transparency on emissions, waste, and lifecycle footprints — a factor impacting supplier selection and investor communications.
Strategic implications for 2026 planning
For executives allocating capital or negotiating supplier relationships in 2026, the report emphasizes pragmatic moves that balance near-term continuity with medium-term strategic optionality:
- Secure dual-qualified suppliers for critical chemistries. Where long qualification cycles exist, parallel-qualification reduces single-source risk and shortens recovery time from interruptions.
- Prioritize regionalization for mission-critical lines. Joint ventures and localized production (or inventory buffers in-region) meaningfully reduce lead time, import risk, and compliance friction.
- Invest in collaborative reformulation programs. Co-funded development for PFAS-alternative chemistries or non-fluorinated photoresists accelerates vendor commitment and spreads technical risk.
- Use concentration metrics to inform negotiation strategy. High CR metrics imply that suppliers hold leverage; procurement should redesign contracting to include volume flexibilty, price collars, and escrowed IP clauses where appropriate.
- Include regulatory scenario modeling in CAPEX and sourcing decisions. Build contingency budgets for reformulation costs, qualification runs, and potential supply requalification cycles over the next 18–36 months.
- Evaluate M&A and minority investments as extension strategies. Acquiring small, specialized material houses or forming minority JVs can accelerate access to niche chemistries, proprietary resins, or regional capacity.
What PW Consulting’s report delivers (practical, actionable contents)
- Proprietary market-size model with historical series and scenario-based forecasts to 2032, enabling sensitivity testing for demand shocks and policy shifts.
- Supplier benchmarking that combines technical readiness, financial health, and capacity roadmaps — built to inform sourcing scorecards and supplier development plans.
- Supply-chain stress maps and mitigation playbooks that identify pinch-points by raw material family and qualification lead time.
- Regulatory impact matrix and reformulation cost estimator for PFAS and related restrictions, designed to support budget requests and compliance programs.
- Deal and partnership playbooks (JV templates, licensing approaches, and acquisition due-diligence checklists) for in-market expansion or vertical integration.
- Commercial tactics: pricing levers, contractual protections, and inventory strategies tuned to the sector’s concentration profile and qualification realities.
Recent developments that matter now
Key capacity and localization announcements among the major suppliers underscore the strategic cadence of the industry: new site acquisitions, completed capacity expansions, and production joint ventures are reshaping the short-term supply picture. Those actions reduce lead-time risk for some buyers but raise the prospect of competitive supply discipline and tighter qualification windows for others. The net effect is that early engagement with suppliers and proactive contractual design will be decisive in 2026 negotiations.
How to use the report in your 2026 playbook
- Board-level briefings: Use the top-line forecasts and concentration diagnostics to quantify strategic exposure and to justify capex or M&A initiatives.
- Procurement strategy: Implement the supplier benchmarking module to reprioritize dual-sourcing, negotiate price/volume agreements, and codify environmental clauses relevant to PFAS dynamics.
- R&D and product management: Align reformulation timelines to regulatory scenarios outlined in the report and adopt the co-development templates for risk-sharing with suppliers.
- Investor communications and risk disclosures: Leverage scenario analyses to communicate resilience plans and regulatory positioning to stakeholders.
Next steps — where to get the full intelligence
PW Consulting’s full Special Electronic Chemicals For Photoresist Market report contains the granular segment-level forecasts, regional demand heatmaps, supplier scorecards, and raw-material consumption tables behind the high-level takeaways presented here. For 2026 procurement, R&D, and corporate development teams, the report converts market signals into executable programs. Visit the report landing page to access the complete dataset, methodological notes, and bespoke consulting options tailored to your organization’s exposure and strategic ambition.
For detailed analysis of this topic, please visit the official page: Special Electronic Chemicals For Photoresist Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com