

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Optical Circuit Switches (OCS) Market to Expand at 20.5% CAGR During 2026–2032

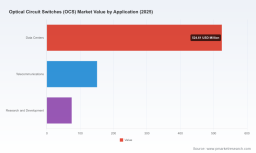
PW Consulting: Optical Circuit Switches (OCS) Market — Strategic Imperatives for Enterprise Decision-Making in 2026
PW Consulting today publishes its definitive market study on Optical Circuit Switches (OCS), delivering a practical intelligence suite for CIOs, infrastructure architects, procurement leads, and strategy teams preparing capital and operational plans for 2026 and beyond. The OCS market has transitioned from early experimentation to enterprise-grade deployment readiness: our base-year model shows growth from approximately USD 295.21 million in 2020 to USD 750.0 million in 2025, with a compound annual growth rate (CAGR) of 20.5% projected through the 2026–2032 forecast window. By 2032 we model a market north of USD 2.7 billion — a scale that converts experimental advantages into strategic imperatives for hyperscale and enterprise operators alike.
Optical Circuit Switches Ocs Market
Why 2026 is a Pivotal Decision Year
-
AI-driven traffic patterns are changing the architectural calculus for data fabrics. High-bandwidth east–west flows and GPU cluster scaling make low-loss, protocol-agnostic optical switching an attractive lever to reduce electrical I/O bottlenecks and power draw.
Optical Circuit Switches Ocs Market -
Energy and infrastructure economics are forcing timely choices. Electricity can represent roughly 40% of a large data center’s operating budget, and U.S. data centers consumed about 176 TWh in 2023 — figures that emphasize the immediate ROI potential of any technology that meaningfully lowers power or cooling demand.
Optical Circuit Switches Ocs Market -
Standards and interoperability are moving from concept to implementation: the Open Compute Project established an OCS sub-project in 2025, a development that materially lowers the barrier for multi-vendor deployments and accelerates procurement cycles for operators who demand vendor-neutral ecosystems.
-
Regulatory and grid constraints — for example, jurisdictional renewables mandates for new data centers — are raising the cost of delay. Where jurisdictions require high shares of fresh renewables or place limits on new grid connections, the ability to improve utilization and reduce peak electrical consumption through optical architectures becomes a procurement and siting advantage.
What the PW Consulting OCS Market Report Delivers (Practical Contents)
-
Quantified market model: historical 2020–2025 data and granular forecasts across 2026–2032, calibrated to multiple adoption scenarios (base, accelerated, conservative).
-
Technology taxonomy and roadmaps: MEMS, liquid-crystal (LCoS), silicon photonics, robotic all-fiber and hybrid approaches — performance envelopes, maturity checkpoints, and integration complexity assessments.
-
Vendor benchmarking and scorecards: comparative assessments of technical capabilities, scalability trajectories, commercial readiness, and supply-chain resilience for leading and emerging suppliers.
-
TCO and deployment playbooks: build-versus-buy models, power/cooling delta analyses, port-count economics, and staged adoption templates (pilot → rack-level → pod → campus).
-
Procurement and integration checklist: test-lab scripts, performance SLAs to negotiate, integration milestones for orchestration stacks, and interoperability test cases aligned to OCP workstreams.
-
Risk matrix and mitigation strategies: failure modes, availability engineering for optical layers, repair/replace cadence, and secondary-path electrical fallbacks.
-
Executive one-pagers and board-ready recommendations tailored to capital planning and sustainability targets for 2026 budget cycles.
High-Level Strategic Findings (Non-Segmented)
-
Market momentum is measurable and commercial: the sector’s CAGR of approximately 20.5% reflects a transition from niche lab deployments to production pilots and early hyperscale adoption. Total market value is forecast to roughly triple from the mid‑2020s to 2032 under our base case.
-
Consolidation and competitive density coexist. Our concentration metrics indicate a clustered vendor landscape: leading vendors hold a majority share of commercial deployments while a healthy set of challengers advances differentiated technology vectors (high radix MEMS, silicon photonics, and robotic all-fiber solutions).
-
Technology plurality will persist through 2026. MEMS and LCoS solutions dominate early commercial adoption due to maturity and port-scale roadmaps, but silicon-photonic PICs and robotic patching systems are achieving important manufacturing and automation milestones that will change cost and power trade-offs across multi-year plans.
-
Interoperability, software orchestration, and standards integration are the gating items for large-scale rollout. Vendors that deliver not just hardware but robust control-plane APIs, telemetry, and integration with fabric orchestrators capture disproportionate enterprise value.
-
Energy-led economics shorten payback horizons. Where optical switching reduces the aggregated power and cooling footprint in AI fabrics, we see materially different total-cost-of-ownership (TCO) outcomes versus traditional electrical switching architectures — enough to justify pilots in 2026 for many operators.
Competitive Landscape Snapshot: Who to Watch
-
Lumentum Holdings Inc. — offers high-radix MEMS OCS platforms tailored to AI and cloud fabrics; notable for integrated rack-level demonstrations with ecosystem optics partners.
-
Coherent Corp. — advancing LCoS-based OCS with a focus on low latency and reliability for AI architectures; positioning emphasizes predictable performance at scale.
-
Molex — accelerating high-radix MEMS platforms and roadmaps toward 1,000+ port ambitions; their March 2026 platform announcement signals aggressive targeting of GPU-cluster topologies.
-
DiCon Fiberoptics — delivering value-focused MEMS solutions with product introductions in early 2026 that target mainstream AI data center deployments.
-
HUBER+SUHNER Polatis — advancing beam-steering all-optical matrices for automation and hyperscale use cases with a strong engineering pedigree.
-
Telescent Inc. — specializing in high-port-count robotic all-fiber switching and automated patching for very large deployments where minimal loss and physical fiber management matter.
-
Calient.AI / Calient Technologies — maintains broad MEMS product families for dynamic interconnection, with a proven history in test automation and protocol-agnostic interconnects.
-
iPronics — silicon photonics-based solutions offering low-power and low-latency programmable OCS approaches; notable for tight integration with PIC ecosystems.
-
Omnitron Sensors — supplies enabling MEMS mirror technology that scales channel counts and reduces insertion loss for hyperscale applications.
Recent industry moves — including high-radix launches and integrated demonstrations at trade venues — underscore two facts: product roadmaps are executing toward higher port counts and ecosystem collaboration (optics + switch + orchestration) is intensifying. We also track manufacturing partnerships that move silicon‑photonics PIC OCS toward pre‑production — a structural change for cost curves and integration models.
Actionable Playbook for Enterprise Leaders in 2026
-
Initiate a phased evaluation program now. Run a controlled pilot (60–120 days) targeting a representative workload cluster to benchmark latency, throughput, and power delta versus electrical baselines. Include automation integration tests with orchestration stacks in scope.
-
Adopt a vendor-agnostic requirements template. Require APIs, telemetry, and OCP-aligned interoperability as contract gating criteria. Demand third‑party test evidence for reliability and insertion-loss figures under full thermal and load conditions.
-
Use scenario TCO modeling. Build three-year and five-year TCOs that incorporate power, cooling, port scaling, maintenance, and the operational cost of software integration. Model sensitivity to port-count scaling and expected GPU density growth.
-
Embed sustainability and regulatory constraints into site selection. Where renewables mandates or grid constraints exist, prioritize architectures that demonstrably lower peak site power or accelerate utilization efficiencies.
-
Align procurement cadence with roadmap maturity. For operators seeking near-term gains, high‑radix MEMS or LCoS pilots may be preferred; for operators with multi-year procurement cycles, plan for PIC and robotic-fiber options as they cross cost and maturity thresholds.
-
Prepare the organization for operational change. Optical layers require updated fault‑management playbooks, spares strategies, and cross-domain runbooks for network, facilities, and platform engineering teams.
Why Access the Full PW Consulting Report
This release is a strategic preview: it outlines the frameworks, drivers, and recommended actions that will define successful OCS decisions in 2026. The full PW Consulting OCS Market Report contains the granular intelligence that operational teams need to execute — including segmented forecasts (by type, application, and geography), vendor revenue estimates and scorecards, detailed TCO models, lab-test protocols, and contract language templates. Those granular data slices and vendor-level financials are intentionally withheld in this preview to preserve the utility of the full report as an operational decisioning tool.
Enterprises planning capital and operational budgets for 2026 should treat OCS as a candidate technology with asymmetric upside: modest near-term deployment effort and clear pathways to material operational savings and performance improvements as AI workloads continue to scale. Our market model and on-the-ground vendor assessments give procurement and architecture teams the empirical footing to move from cautious interest to disciplined experimentation and staged adoption.
To request the full PW Consulting Optical Circuit Switches Market Report, contact our research desk for licensing and briefings. PW Consulting will support executive briefings, vendor selection workshops, and implementation roadmaps tailored to client architectures and timelines.
For detailed analysis of this topic, please visit the official page: Optical Circuit Switches Ocs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com