

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Floor-Standing Aircraft Weighing Scales Market to Expand at 7.0% CAGR, Surpassing USD 836.75 Million by 2032

Floor-Standing Aircraft Weighing Scales Market — 2026 Strategic Playbook
PW Consulting’s latest market research on Floor-Standing Aircraft Weighing Scales equips executives with the actionable intelligence needed to make high-stakes decisions in 2026. Built on a 2020–2025 historical analysis with 2025 as the base year and a granular forecast covering 2026–2032 (USD, revenue in Million), the report synthesizes market sizing, technology trends, regulatory constraints and competitive dynamics into a compact, implementation-focused advisory. The market has demonstrated resilient expansion—moving from roughly USD 312.5 Million in 2020 to about USD 521.1 Million in 2025—and is projected to reach approximately USD 836.8 Million by 2032, reflecting a 7.0% CAGR across the forecast window. This release explains why those headline numbers matter for 2026 strategy while preserving the report’s proprietary segmentation matrices as an incentive to obtain the full dataset.
Floor Standing Aircraft Weighing Scales Market
Why this report matters for 2026 decision-makers
-
Timing: 2026 is a pivotal year for procurement cycles across airlines, MROs and defense budgets; the report identifies windows where capital allocation can materially improve lifecycle cost and operational uptime.
Floor Standing Aircraft Weighing Scales Market -
Risk mitigation: the research maps regulatory and calibration requirements—such as FAA advisory guidance and accuracy tolerances critical to certified operations—so that buyers and suppliers can avoid costly non-compliance.
Floor Standing Aircraft Weighing Scales Market -
Investment clarity: the forecast and scenario modules translate market growth into practical KPIs for R&D, manufacturing scale-up, and M&A prioritization.
-
Commercial leverage: price architecture and service-bundling recommendations enable vendors and buyers to capture margin while reducing total cost of ownership.
What the report delivers — operational, not academic
-
Market sizing and forecast (2020–2032): transparent methodology, base-year calibration (2025), and detailed demand drivers expressed in USD (Million).
-
Segmentation framework and buyer archetypes: commercial, defense and general aviation use-cases are profiled with procurement triggers, expected buying cycles and service expectations (note: detailed segmentation tables are available in the full report).
-
Competitive benchmarking: comparative scorecards covering product breadth (platforms, low-profile pads, under-axle systems), wireless and telemetry capabilities, calibration services and global service footprint.
-
Regulatory and compliance playbook: mapping of FAA guidance and accuracy standards, calibration traceability (NIST-equivalence) and type-approval considerations for airport operators and MROs.
-
Supply-chain and raw material analysis: supplier concentration, harmonized bill-of-materials for common platforms, and a focused assessment of aircraft-grade aluminum availability and pricing exposure.
-
Go-to-market and procurement tools: RFP templates, vendor scorecards, TCO/CAPEX calculators, maintenance and calibration SLAs, and retrofit guidelines for integrating weighing systems into GSE fleets and final-assembly lines.
-
Scenario planning & investment thesis: three demand scenarios (conservative, base, accelerated) with triggers, break-even points for new product introductions and M&A integration playbooks for strategic acquirers.
Competitive landscape — strengths, trade-offs and recent moves
-
Intercomp Company (Medina, Minnesota) — positioned as a product and systems innovator with a long track record in platform scales and top-of-jack solutions for civil and military customers. Recent launches demonstrate a push into wireless telemetry and higher throughput data capture; notable customer adoption in 2025 underscores commercial acceptance of low‑profile, high‑capacity platforms.
-
General Electrodynamics Corporation (GEC) (Arlington, Texas) — differentiated by portable, wireless and low-profile platforms with patented elements and a strong global installed base. The company’s product range targets rapid-deployment use and airline/military mobility requirements.
-
Teknoscale Oy (Vantaa, Finland) — a specialist focused on high-capacity floor platforms engineered for commercial and fighter aircraft, bringing European engineering depth and niche customized solutions for OEM and MRO use.
-
Langa Industrial S.A. (Spain) — competes as a systems integrator and supplier to OEM final-assembly processes; recent homologation achievements for aerospace jacks and GSE demonstrate strategic attachment to major airframe manufacturers.
-
FEMA AIRPORT and Henk Maas Weegschalen B.V. — regional manufacturers supplying certified platforms and airport-grade equipment; they play an important role in localized service and compliance support.
-
Jackson Aircraft Weighing Systems LLC — focused on market segments requiring under-axle and platform systems for business and transport category aircraft, with an emphasis on field-serviceability.
Market concentration is meaningful: the top three and top five manufacturers account for nearly half and over sixty percent of industry revenue respectively, which creates opportunities for challengers to exploit service gaps and for incumbents to pursue bolt-on consolidation to strengthen their installed base.
Regulatory and technical imperatives shaping product roadmaps
-
Calibration traceability and accuracy: FAA advisory guidance and industry standards require precise, traceable calibration (including NIST-equivalent traceability) and stringent accuracy thresholds—this turns calibration networks and certified service partners into strategic assets, not cost centers.
-
Data and connectivity: wireless telemetry, Bluetooth and integrated weighing software are moving from differentiators to baseline expectations; interoperability with weight-and-balance systems and airline maintenance databases is increasingly decisive in procurement.
-
Materials and manufacturability: aircraft-grade aluminum and engineered alloys enable lower-profile, higher-capacity pads but introduce raw-material and fabrication dependencies that must be hedged via sourcing strategies.
Strategic implications — six recommended moves for 2026
-
Lock in service and calibration networks: prioritize partnerships or acquisitions that secure certified calibration teams and regional service centers—this reduces downtime risk and supports premium pricing.
-
Invest in telemetry-first product designs: accelerate development of wireless, secure telemetry and API-enabled reporting to integrate seamlessly into airline MRO and weight-and-balance workflows.
-
Target bolt-on consolidation to capture installed-base economics: given industry concentration, well-structured acquisitions of regional specialists can expand service footprints and accelerate cross-selling of software and SLAs.
-
Hedge raw-material exposure: create multi-sourced supply agreements for aircraft-grade aluminum and qualify alternative alloys to protect product roadmaps from price shocks and lead-time variability.
-
Differentiate on lifecycle value: move beyond product-only bids—offer subscription calibration, predictive maintenance and data services that convert one-time sales into recurring revenue.
-
Prepare bid bundles for 2026 procurement cycles: use the report’s RFP templates, scorecards and TCO calculators to win tenders by quantifying savings and compliance assurance over typical contract terms.
How PW Consulting supports execution
-
Rapid due diligence: 30–60 day validation packages for acquirers that reconcile revenue run-rates, service-attach economics and regional compliance obligations.
-
Commercial acceleration: vendor positioning workshops to reframe offerings as integrated weighing-as-a-service solutions leveraging telemetry and predictive calibration.
-
Procurement readiness: bespoke tender support, including customized RFPs, supplier shortlists and on-site evaluation protocols.
-
Operational improvement: manufacturing and supply-chain audits focused on alloy sourcing, supplier qualification and cost-to-produce modelling for low-profile platforms.
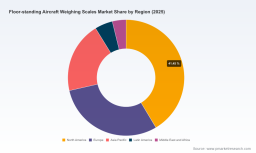
What we are intentionally not publishing in this release: the granular regional splits, individual application portfolios by dollar value, and the proprietary micro‑segmentation tables that drive vendor-level market shares. These are preserved in the full report to ensure buyers and vendors receive the decision-grade granularity they need to act with confidence.
Next steps
For executive teams planning capital allocation, product launches, or M&A in 2026, access to the full dataset and proprietary segmentation is the difference between tactical moves and strategic advantage. PW Consulting is offering limited-access briefing sessions where we walk clients through tailored scenarios drawn from the report and provide immediate answers to procurement, compliance and go‑to‑market questions. Contact our research team to schedule a briefing and obtain the full Floor-Standing Aircraft Weighing Scales Market report, which includes the complete breakdowns, source tables and vendor scorecards necessary to finalize 2026 plans.
For detailed analysis of this topic, please visit the official page: Floor Standing Aircraft Weighing Scales Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com