

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Ballistic Protection Market to Grow from USD 15.48 Billion in 2025 to USD 23.82 Billion by 2032 at a 6.35% CAGR

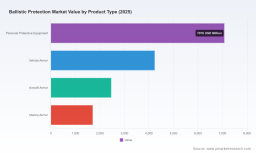
Ballistic Protection Market 2026: Strategic Imperatives for Defense, Law Enforcement and Critical Infrastructure Operators
PW Consulting’s latest Ballistic Protection Market report—anchored to a 2025 base year and projecting through 2032—delivers a decision-grade view designed to shape procurement, R&D, manufacturing and M&A choices in 2026. The global market, measured at approximately USD 15.48 billion in 2025, is forecast to expand at a compound annual growth rate (CAGR) of about 6.35% over the 2026–2032 horizon, reaching roughly USD 23.82 billion by 2032. Those headline metrics underscore both the steady growth dynamics and structural shifts that will define supplier advantage and buyer risk in the next strategic cycle.
Ballistic Protection Market
Why this report matters for 2026 decision-makers
-
Timing matters: 2026 is the year many defense and civilian procurement programs transition from legacy configurations to systems that must meet updated certification and interoperability requirements. The updated NIJ 0101.07 standard and recent NATO survivability revisions are creating a pronounced upgrade cycle across multiple buyer segments.
Ballistic Protection Market -
Technology-material inflection: Material substitution and lightweighting—driven by UHMWPE developments and next-gen unidirectional laminates—are redefining performance-per-kilogram and enabling new platform-level trade-offs, from soldier load reduction to lighter vehicle kits.
Ballistic Protection Market -
Supply-side stressors: Elevated aramid feedstock costs and concentrated production nodes for key ballistic materials heighten short-to-medium-term sourcing risk, making supply assurance and dual-sourcing strategies a board-level concern.
-
Commercial consolidation and fragmentation: The market displays a moderate level of concentration at the top, creating windows for nimble specialists to scale via technology licensing, strategic partnerships or tuck-in M&A.
Macro trajectory and strategic implications
The market’s projected trajectory—mid-single-digit CAGR across 2026–2032—reflects a blend of steady defense modernization spending, increasing law-enforcement and civilian protection demand, and accelerating uptake of lightweight materials. For corporate strategists, this macro picture supports a dual-pronged approach: protect core revenue streams tied to legacy systems while selectively investing in high-margin, high-growth product adjacencies (e.g., ultra-light plates, modular helmet systems, and integrated survivability kits).
Market concentration metrics indicate that the top three firms collectively control a meaningful share of global revenues, and the top five increase that grip substantially. This structure favors incumbents that can combine scale, certification expertise, and vertical integration, but it also enables boutique innovators to capture premium niches—especially where material science or ergonomic differentiation deliver clear buyer value.
What the PW Consulting report delivers (practical, practitioner-focused)
-
Executive decision memos tailored for C-suite and procurement leads—summarizing priority actions for 2026.
-
Validated market sizing and topline forecasts (2020–2032) with scenario-modeled pathways and sensitivity to raw-material shocks and certification-driven replacements.
-
Regulatory impact matrix: a practical planner showing how NIJ and NATO standard changes translate into procurement cycles, retrofit windows, and compliance timelines.
-
Materials and technology landscape: comparative TCO and performance profiles for ceramics, composites, aramids, UHMWPE, metals and ballistic glass—plus a supplier-risk heatmap.
-
Supply-chain playbook: procurement templates, dual-sourcing models, inventory staging plans, and contract clauses to mitigate feedstock price volatility and capacity constraints.
-
Competitive benchmarking: strategic positioning, product roadmaps, and capability gaps for incumbent leaders and challengers, enabling rapid assessment of potential partners or acquisition targets.
-
M&A and partnership scorecards: prioritized lists based on strategic fit, technology defensibility, and integration complexity (data tables and red-teaming scenarios included).
-
Certification and product launch checklist aligned to NIJ 0101.07 and major military standards, including templates for performance validation and user trials.
-
Practical case studies and buyer personas—illustrating procurement decision flows for national defense agencies, law enforcement procurement groups, commercial security buyers, and OEM integrators.
Competitive landscape: who to watch and what they signal
The market’s competitive map includes integrated defense primes, specialized body-armor manufacturers, advanced-materials suppliers, and nimble systems integrators. Each player type brings different strategic leverage.
-
BAE Systems plc – As an integrated defense prime, its strengths lie in platform-level survivability and systems integration. BAE’s armor modules and vehicle protection solutions position it to win large-scale modernization contracts where scale and full-system certification matter most.
-
Rheinmetall AG – Focused on vehicle armor and survivability modules, Rheinmetall benefits from strong program-level relationships with defense ministries and an engineering-first approach to up-armor solutions.
-
Point Blank Enterprises and Safariland – These U.S.-based tactical and personal protection specialists maintain strong law-enforcement and military small-quantity award pipelines; they remain attractive partners for rapid fielding and platform-level customization.
-
DuPont, Teijin, Honeywell and Avient (Dyneema) – Material suppliers are the strategic fulcrum. Recent launches—such as Dyneema’s newer unidirectional hard ballistic materials—illustrate how upstream innovation can yield 30–50% system-level weight reductions, re-shaping product roadmaps across OEMs and integrators.
-
Avon Protection, MKU, NP Aerospace, Morgan Advanced Materials and TenCate – These firms occupy the mid-market space for helmets, ceramics, and composite modules. Their technical depth and niche specialization make them preferred suppliers for performance-sensitive programs and rapid-certification efforts.
-
Galvion and ArmorSource – Emerging helmet and head-protection innovators are advancing modularity, integration of comms and power, and improved ergonomics—areas that yield clear differentiation for dismounted soldier systems.
Recent market moves reinforce these strategic dynamics: product launches and new unidirectional materials introduced in 2024–2025 have accelerated weight-performance trade-offs; several firms announced capacity expansions and certification-focused showcases in early 2026; and targeted contract awards in 2025 highlight continuing importance of regionally responsive supply chains. Taken together, these developments amplify upside for material innovators and certified integrators while increasing pressure on legacy producers to modernize.
Practical strategic recommendations for 2026
-
Prioritize certification readiness: Align product roadmaps and testing calendars to NIJ 0101.07 and relevant military standards now—3–12 month lead times for validation and field trials should be budgeted into 2026 programs.
-
Diversify material exposure: Hedge aramid price risk with selective increases in UHMWPE and hybrid laminates; negotiate capacity commitments or off-take agreements with key fibers suppliers.
-
Invest in lightweight, modular platforms: Focus R&D and early commercial launches on solutions that deliver demonstrable weight savings or platform-level integration (e.g., modular plates, helmet ecosystems).
-
Build supply-resilient footprints: Consider regional manufacturing or assembly hubs to shorten lead times for critical procurement markets and to meet contractual offset/industrial participation requirements.
-
Pursue targeted M&A: Seek tuck-in technologies that close material, certification or ergonomic gaps rather than scale-driven buys; boutique innovators with validated performance offer faster commercialization pathways.
-
Operationalize scenario planning: Run stress tests for raw-material shocks, certification delays, and rapid demand spikes—embed contingencies into procurement contracts and inventory strategies.
-
Differentiate on lifecycle services: Offer integrated support—maintenance, retrofit kits, ballistic testing updates—and digital tracking for armor life and performance to create recurring revenue streams.
Where to go from here
This report is intentionally structured as a practitioner’s toolkit—built to reduce sourcing risk, accelerate certification-to-field timelines, and reveal pockets of strategic advantage in a consolidating market. To preserve competitive sensitivity and to encourage direct engagement, we have presented macro sizing, trajectory and concentration metrics in this overview while reserving detailed segment-level splits and supplier-level revenue tables for the full report and interactive dashboards on the PW Consulting portal.
For a tailored briefing that translates these insights into a one-page action plan for your organization—or to request the full dataset, scenario models and sector-specific playbooks—contact PW Consulting. Our advisory teams will walk you through the data, validate strategic options against your operating model, and co-design rapid implementation pathways for 2026 priorities.
For detailed analysis of this topic, please visit the official page: Ballistic Protection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com