

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Low Voltage Motor Control Center Market to Hit USD 8,681.44 Million by 2032 at a 6.1% CAGR — Asia Pacific Leads with USD 2,208.32 Million

PW Consulting Releases Strategic Briefing: Low Voltage Motor Control Center Market Set for Steady Expansion — Critical 2026 Decisions Require Data-Driven, Modular Strategies
Today PW Consulting publishes an executive briefing that previews our forthcoming in-depth market study on the Low Voltage (LV) Motor Control Center (MCC) market. Built from a rigorous base-year assessment (2025) and a seven‑year forecast window (2026–2032), the report synthesizes quantitative trend analysis and practical playbooks to help executives make higher-confidence decisions in 2026 and beyond.
Low Voltage Motor Control Center Market
Why this briefing matters for 2026 decision-making
-
Market momentum: Our modelling shows the LV MCC market has grown from a multi-billion-dollar base in 2020 to a materially larger industry by 2025, and is projected to continue expanding through 2032 at a compound annual growth rate (CAGR) of 6.1% (forecast period 2026–2032). This trajectory signals persistent replacement and upgrade cycles tied to automation, energy efficiency mandates and safety compliance.
Low Voltage Motor Control Center Market -
Timing is strategic: Suppliers, corporate buyers, and plant owners who align project pipelines, procurement strategies and R&D roadmaps in 2026 will capture outsized benefit from the market’s structural growth between 2026 and 2032.
Low Voltage Motor Control Center Market -
Actionable intelligence: The briefing focuses on operational levers — modular design choices, lifecycle cost optimisation, digital retrofit strategies, and supplier negotiation tactics — enabling decision-makers to translate macro trends into measurable outcomes this year.
Market trajectory and what the numbers tell us
Our historical review reveals a steady climb in total market value over the 2020–2025 period, reflecting a combination of greenfield industrial investment, replacements of legacy switchgear, and an increasing share of intelligent MCC deployments. The market size assessed for 2025 establishes the operational baseline used across our scenarios. Under a central case, the market grows through 2026 and continues to 2032, reaching a significantly higher valuation by the end of the forecast window. This baseline growth, captured by a 6.1% CAGR during 2026–2032, is robust enough to justify strategic investments in modular product platforms, digital services, and aftermarket capabilities.
Core demand drivers and regulatory overlay
-
Energy and efficiency mandates: Stricter energy performance standards and corporate decarbonisation objectives push industrial operators toward MCC solutions that integrate variable frequency drives (VFDs), energy monitoring and smarter motor management.
-
Safety and compliance: International standards for low‑voltage switchgear (notably IEC 61439 series) and growing insurer and workplace-safety expectations are accelerating adoption of arc‑resistant constructions and features such as optical arc detection and zone selective interlocking.
-
Automation and IIoT: Demand for predictive maintenance and uptime improvements is driving integrated IoT capabilities, enabling remote diagnostics, condition-based maintenance and new service revenue streams for suppliers.
-
Supply-side pressures: Elevated raw-material costs — for example, steel used in enclosures — and sporadic volatility in 2025 have raised procurement and product-cost management to the top of supplier and buyer agendas.
Competitive landscape — strategic positions and differentiators
The LV MCC market is moderately concentrated. Our concentration analysis indicates that the three largest suppliers capture a meaningful share of the market, and the top five command just over half, creating pockets of influence by established global players while leaving room for regional specialists and OEM partners. This structure has three strategic implications: scale advantages matter for integrated electrification projects; niche and customization capabilities remain commercially relevant; and consolidation or partnering will continue to be an M&A theme.
-
Large global electrification vendors: Companies such as ABB, Schneider Electric, Eaton, and Siemens are competing on integrated portfolios — combining arc-resistant hardware, digital platforms, and energy‑management features — to offer end‑to‑end solutions for large industrial customers.
-
Automation-first suppliers: Rockwell Automation and similar players differentiate on control-layer integration, real‑time diagnostics and modular architectures that shorten commissioning cycles and reduce lifecycle costs.
-
Regional and specialist OEMs: Firms such as Powell Industries, Tesco Controls and RESA Power focus on customization, retrofits and remanufacturing — a valuable route-to-market for industrial users with legacy assets or atypical specifications.
-
New product activity to watch: Recent product introductions and trade show presentations underscore the market’s innovation cadence. Notably, a major automation vendor launched a next‑generation IEC MCC family with enhanced real‑time telemetry and modular design showcased at Hanover/industrial events, while other manufacturers highlighted energy‑transition pathways at leading trade shows.
What the PW Consulting report delivers — operational and strategic components
Our full study combines proprietary market sizing with practical tools designed to change outcomes for buyers, OEMs and investors. Highlights include:
-
Methodology and assumptions: Transparent documentation of data sources, model structure and scenario boundaries (base year 2025; forecast 2026–2032), enabling clients to stress‑test assumptions against their own exposure.
-
Scenario modelling: Three forward-looking scenarios (conservative, central, and accelerated) showing demand sensitivity to variables such as steel pricing, automation uptake rates, and regulatory tightening.
-
Supplier benchmarking: Qualitative and quantitative supplier profiles that evaluate product portfolios, digital capabilities, global footprint and aftermarket services — structured to inform vendor shortlists and RFPs.
-
Commercial playbooks: Practical templates for procurement negotiations, lifecycle cost comparisons (CapEx vs. OpEx tradeoffs), and O&M optimisation for both greenfield and brownfield projects.
-
Technology adoption frameworks: Guidance on when to standardise on intelligent MCC architectures (VFDs, integrated energy meters, IoT gateways) versus when to prioritise tried-and-tested conventional panels, framed by ROI thresholds and uptime targets.
-
Compliance and risk matrices: Checklists and decision trees aligned to IEC standards, arc-resistant design options, and insurance/contractual considerations to reduce project friction and downtime risk.
-
Investment thesis and M&A radar: A strategy module for corporate development teams that identifies attractive targets, partnership models and integration pitfalls given the market’s medium concentration profile.
Practical recommendations for 2026 — prioritized actions
-
For industrial end-users: Conduct a 90‑day MCC portfolio review to classify assets by criticality and retrofit readiness; prioritise upgrades that deliver measurable energy savings and reduced maintenance costs within a 24–36 month payback horizon.
-
For OEMs and system integrators: Double down on modular, serviceable designs and invest in pre‑configured digital packages that lower implementation friction; accelerate partnerships with IIoT platform providers to capture aftermarket service revenues.
-
For procurement and finance teams: Embed scenario-based escalation clauses in multi-year sourcing agreements to mitigate raw material and logistics volatility, and design scorecards that weight lifecycle costs and digital readiness over headline price.
-
For investors and corporate development: Use the report’s supplier benchmarking and concentration analysis to identify roll-up candidates and adjacencies where scale and digital services can materially improve margins.
Risk considerations and watchlist for 2026
-
Commodity risk: Persistent but manageable steel-price volatility can compress supplier margins and shift total cost of ownership profiles; stress-test procurement models against plausible price paths.
-
Standards and insurance: Accelerating safety standards and insurer requirements for arc-resistant installations could force accelerated capex in certain industrial segments — a wildcard that should be modelled in any multi-year plan.
-
Technology fragmentation: Divergent IIoT protocols and inconsistent digital maturity across plants can limit immediate gains from predictive maintenance; prioritise interoperability in procurement specifications.
About PW Consulting’s research approach
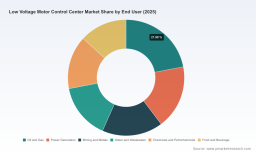
Our study is built on a hybrid methodology combining bottom‑up shipments and pricing analysis with top‑down macro demand modelling. We triangulate public financials, supplier disclosures, trade show intelligence, and primary interviews with OEMs, system integrators and end-users. The result is a market framework that is both reproducible and directly actionable for strategy teams. To preserve commercial value and maintain a concise executive briefing, detailed segment-level data and granular regional/application splits are reserved for the full report and interactive datasets available via our report portal.
Conclusion — why leaders should act now
The LV MCC market’s growth profile through 2032, driven by energy efficiency mandates, automation and safety compliance, creates a clear imperative for action in 2026. Companies that align procurement, product strategy and digital service models to the market’s structural drivers will secure lower lifecycle costs and new revenue streams. PW Consulting’s full report equips decision-makers with the quantitative detail and operational playbooks necessary to turn market growth into competitive advantage.
For access to the complete dataset, granular segmentation, and supplier scorecards, visit our report page to download the full study and the custom briefing options designed for C-suite and operational leaders.
For detailed analysis of this topic, please visit the official page: Low Voltage Motor Control Center Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com