

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Mechanical Dust Collector Market Hits USD 648.16 Million in 2025; Forecast to Grow at a 4.8% CAGR Through 2032

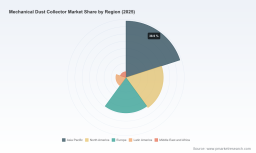
Mechanical Dust Collector Market: Strategic Imperatives for 2026 — PW Consulting Executive Brief
PW Consulting’s latest Mechanical Dust Collector Market report (base year 2025; forecast 2026–2032) provides senior leaders with the actionable intelligence required to make decisive capital allocation, procurement, and regulatory-compliance decisions in 2026. Our top-line model shows the global market stabilizing near USD 648.2 Million in 2025 and expanding at a compound annual growth rate of 4.8% through 2032, approaching roughly USD 900 Million by the end of the forecast horizon. Those headline figures frame a market that is mature, compliance-driven, and ripe for selective consolidation and product-technology disruption.
Mechanical Dust Collector Market
Why 2026 Is a Strategic Inflection Point
- Regulatory acceleration: New emissions and safety mandates are changing capex priorities. Notably, tightening national standards for hazardous air pollutants and combustible dust directives have shifted projects from discretionary to compliance-critical, forcing boards and plant managers to accelerate upgrade timelines.
- Cost pressure from inputs and labor: Fabrication cost inflation and rising maintenance labor rates are increasing installed and life-cycle costs. Procurement teams must now balance first-cost vs. total-cost-of-ownership with greater discipline.
- Technology and aftermarket opportunity: Advances in filter media, cleaning regimes, and digital monitoring are raising the performance bar for new systems while creating attractive aftermarket revenue pools for service-led providers.
Collectively, these forces are reshaping competitive dynamics and buyer behavior. The 4.8% CAGR is modest but masks an important structural change: growth is increasingly concentrated in retrofit, upgrade, and high-efficiency fine-dust use cases rather than greenfield installs, which alters unit economics, channel strategy, and partner requirements for original equipment manufacturers (OEMs) and system integrators.
Mechanical Dust Collector Market
What the Report Delivers — Practical, Board-Level to Operational Guidance
PW Consulting designed this study as a practical playbook for executives and functional leaders. The report combines market forecasting with decision-grade tools that remove ambiguity from capital-intensive choices:
Mechanical Dust Collector Market
- Proprietary top-down and bottom-up market sizing with scenario-based sensitivity analysis to stress-test budgets and M&A models.
- Regulatory compliance playbook that translates new emissions and combustible-dust rules into prioritized project lists by risk class and payback window.
- Technology and solution roadmap comparing filtration technologies, cleaning systems, and energy-performance trade-offs across common industrial use cases.
- Procurement templates and a vendor scorecard methodology to standardize RFP evaluation on lifecycle cost, emissions performance, energy use, and service capability.
- Retrofit decision matrices and case studies demonstrating when to retrofit vs. replace, including O&M cost benchmarks and downtime minimization tactics.
- Investment and M&A filters to identify attractive targets in a fragmented vendor landscape, with integration roadmaps and revenue-synergy estimates.
To preserve the strategic value of the study for clients and stakeholders, the report intentionally reserves granular regional and application splits for subscribers and tailored briefings. High-level dynamics and tactical implications are included here so leaders can act; specific segment tables and node-level forecasts are available in the full deliverable.
Market Dynamics That Will Drive Boardroom Decisions
- Compliance-driven capex prioritization: With emissions thresholds and safety directives tightening, procurement timelines are compressing. Projects that once fell into three-to-five-year plans are being moved forward to avoid regulatory noncompliance and associated penalties.
- Retrofit-first strategies: Many operators will opt for targeted retrofits (filter-media upgrades, pulse-jet enhancements, upgraded controls) rather than full plant replacements to achieve required efficiencies with lower capital and shorter outage windows.
- Aftermarket services as a profit lever: The growing installed base combined with higher maintenance labor rates makes long-term service contracts and predictive-maintenance offerings high-margin, recurring-revenue opportunities.
- Supply-chain resilience and cost management: Fabrication-cost inflation and supply constraints mean procurement teams must build hedging strategies and supplier partnerships to protect margins on new deployments.
Competitive Landscape — Who’s Moving and Why It Matters
The market remains fragmented (low three- and five-firm concentration), providing room for both niche specialists and scale-oriented players. Our analysis of leading OEMs and system providers highlights differentiated positioning and near-term strategic moves:
- Donaldson Company, Inc. (Torit products) — A legacy player with strong presence across woodworking, metalworking, and cement. Recent trade-show activity demonstrates continued investment in higher-performance filter media for metal fabrication. Strategic strength: broad channel reach and brand trust in heavy-industrial filtration.
- Camfil APC — Focused on cartridge and bag technologies for high-spec applications such as pharmaceuticals and food processing. The company’s recent product launch emphasizing higher fine-dust capture efficiency positions it strongly in markets where regulatory thresholds are most severe. Strategic strength: high-efficiency cartridges and cleanroom-adjacent credibility.
- Nederman — Emphasizes energy-efficient cyclonic and pulse-jet systems tailored to fume and bulk powder handling. Trade-show visibility underscores an R&D focus on lower-energy operation. Strategic strength: product breadth for industrial fume and welding applications.
- RoboVent — A specialist focused on automotive and aerospace applications where high-efficiency particulate removal and modular footprints matter. Strategic strength: engineering-led, high-performance niche systems with digital monitoring integration.
- Wheelabrator (Archetype) — Strong in abrasive-blasting and surface-prep applications with reverse-pulse baghouse expertise. Strategic strength: deep domain knowledge in heavy surface-prep markets and aftermarket consumable economics.
- Ceco Environmental (Peerless) — Supplies high-temperature fabric filters for cement, steel, and power. Strategic strength: capabilities in high-spec and extreme-condition installations.
- Schust Engineering & Aget Manufacturing — Both excel as custom and sector-focused players for food, chemical, agricultural, and woodworking clients, competing on tailored design and rapid field support.
Recent product and trade-show announcements from multiple vendors reflect two clear themes: (1) competition is now as much about filter media and system integration as it is about steel fabrication; and (2) product launches and show-floor activity are validating a trend toward higher capture efficiency coupled with lower energy-per-cfm operation.
Strategic Playbook — Five Tactical Recommendations for 2026
- Prioritize compliance triage: Segment your asset base by regulatory risk and implement a fast-track retrofit program for top-tier noncompliant assets to avoid fines and production disruption.
- Buy on total cost of ownership: Shift procurement criteria from purchase price to life-cycle cost, factoring in energy consumption, filter replacement cadence, and downtime risk.
- Negotiate integrated service contracts: Secure multi-year O&M agreements with performance SLAs and remote monitoring to reduce internal maintenance exposure and stabilize costs.
- Pilot digital monitoring: Start with small-scale predictive-maintenance pilots tied to measurable KPIs (capture efficiency, differential pressure, downtime) before scaling enterprise-wide.
- Hedge supply risk: Lock in fabrication and critical-material supply with tier-one suppliers or multi-sourcing strategies to blunt single-source disruptions and price shocks.
How Corporate Leaders Should Use This Report in 2026
This report was written to be usable directly in board-level briefing decks, procurement RFP attachments, and M&A diligence processes. Executives will find immediately actionable outputs — from compliance-driven project prioritization lists to vendor evaluation templates — that translate market forecasts into operational decisions. For buyers and investors, the proprietary scenario models and vendor scorecards provide the evidence base necessary to justify budgets and acquisition targets.
PW Consulting intentionally omits detailed regional and application-level splits from this public summary to preserve the investigative and forecasting value of the full report. Subscribers receive downloadable spreadsheets containing granular node-level forecasts, vendor financial proxies, and customizable scenario tools that map directly to plant- and portfolio-level decision-making.
Next Steps
- For a tailored briefing that maps these findings to your asset base or investment thesis, request a private executive session with the PW Consulting mechanical filtration team.
- Access the full report to obtain detailed regional and application splits, supplier scorecards, and downloadable financial models to support procurement, capital planning, and M&A diligence.
In constrained budgets and tightening regulatory regimes, the best decisions in 2026 will be those grounded in both compliance pragmatism and rigorous lifecycle economics. PW Consulting’s Mechanical Dust Collector Market report equips leaders to make those decisions with clarity and confidence.
For detailed analysis of this topic, please visit the official page: Mechanical Dust Collector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com