

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
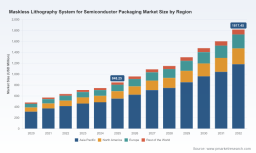
PW Consulting Forecast: Maskless Lithography for Semiconductor Packaging to Grow at 11.48% CAGR, Reach USD 1,817.45 Million by 2032 as Asia Pacific Leads with USD 551.5M (2025)

Maskless Lithography System for Semiconductor Packaging Market — Strategic Insights for 2026 Decision-Makers
PW Consulting’s new market intelligence brief on Maskless Lithography Systems for Semiconductor Packaging synthesizes five years of historical dynamics with a forward-looking, practical playbook designed specifically for executives making capital, partnership, and roadmap decisions in 2026. The market we modelled grew rapidly between 2020 and 2025, reaching an estimated USD 848.25 million in 2025, and is forecast to expand at a compound annual growth rate (CAGR) of 11.48% through our 2026–2032 projection horizon, crossing the USD 1.8 billion threshold by 2032. These headline metrics reflect a technology transition from niche prototyping to scalable production-enabling equipment across wafer- and panel-level advanced packaging lines.
Maskless Lithography System For Semiconductor Packaging Market
Why 2026 Is a Pivotal Decision Year
Three converging forces make 2026 a decision inflection point for semiconductor packaging stakeholders.
Maskless Lithography System For Semiconductor Packaging Market
- Technology readiness and commercialization: Suppliers are releasing production-grade maskless tools with sub‑2 µm and even 1.0 µm capability while addressing classical barriers such as die shift, substrate warpage, and large‑format projection — moving maskless from lab demos into factory floors.
- Demand dynamics driven by heterogenous integration: Chiplet architectures and high‑performance compute stacks require flexible, low‑NRE lithography solutions to support variable designs and iterative prototyping at scale.
- Consolidation and competitive structure: The market exhibits meaningful concentration among a small group of technology leaders, creating both opportunity and supplier risk for adopters. Our analysis of market concentration highlights how the top vendors collectively shape ecosystem incentives, standards, and after‑sales frameworks.
What PW Consulting’s Report Delivers — Practical and Actionable
This study emphasizes operationalizable outputs for procurement, engineering, and corporate strategy teams. Key components include:
Maskless Lithography System For Semiconductor Packaging Market
- Validated market model (historical 2020–2025, base year 2025) and a detailed forecast through 2032, with scenario sensitivity to throughput, yield improvements, and adoption velocity.
- Vendor evaluation framework and scorecards that translate technical specs into buyer-relevant KPIs: throughput per shift, pattern fidelity vs. substrate warpage, die‑shift compensation accuracy, and integration effort into existing back‑end lines.
- CapEx planning templates and ROI calculators calibrated to maskless-specific inputs (tool lifecycle, maskless-specific maintenance, SLM/solid‑state light‑source depreciation, and yield delta assumptions).
- Go‑to‑market and co‑development playbooks for IDMs, OSATs, and substrate suppliers — including pilot plan checklists, qualification test matrices, and supplier risk mitigation strategies.
- Supply chain and regulatory intelligence: export control considerations, localized service coverage analysis, and supplier diversification scenarios for 2026–2028 procurement windows.
- Hands‑on process integration guidance spanning metrology, stitch‑free patterning verification, and hybrid bonding interface timing to shorten ramp‑to‑volume.
Competitive Landscape — Strategic Implications for Buyers and Investors
The competitive arena is populated by legacy lithography specialists, established back‑end vendors, and regional direct‑write players. Our report profiles each core supplier with practical takeaways for selection and partnership strategies.
- Heidelberg Instruments (Germany): Their MLA series is positioned for mid‑ to high‑volume wafer‑level packaging with strong die‑shift compensation and design customization capabilities. Strategic implication: ideal for firms prioritizing flexible, iterative NPI cycles without photomask inventory.
- EV Group (Austria): EVG’s LITHOSCALE platform has been showcased as a high‑throughput maskless exposure option targeted at heterogeneous integration and probe‑card markets. Strategic implication: EVG is a candidate for players aiming to scale maskless into high‑volume manufacturing, especially where stitch‑free full‑wafer patterning matters.
- Nikon Corporation (Japan): The DSP‑100 introduces maskless direct projection with very fine line/space capability and warpage correction. Strategic implication: for high‑precision, large‑substrate applications — particularly customers pursuing the most demanding L/S resolutions — Nikon warrants early technical qualification.
- SCREEN Holdings & SÜSS MicroTec: Both suppliers bring proven LDI and projection expertise and are strong options where throughput and robust service frameworks are required for advanced packaging lanes.
- In‑Vision, Applied Materials (with Ushio), and others: Digital light engines and DLT approaches target large glass/package substrates and panel‑level flows. Strategic implication: these solutions can materially reduce NRE and photomask dependency for large‑format package architectures when coupled with appropriate yield engineering.
- Regional and emerging suppliers (China, Japan, Europe): Several smaller suppliers offer competitive direct‑write systems and localized support. Strategic implication: low‑cost alternatives exist, but buyers must evaluate lifecycle support, roadmaps, and interoperability before volume commitments.
Recent vendor moves underline the market’s maturation: Nikon began accepting orders for its DSP‑100 in mid‑2025; EVG highlighted LITHOSCALE XT at major trade events in late 2025 and early 2026; Heidelberg published application updates demonstrating maskless advantages for AI/HPC packaging in late 2025. These developments are direct evidence of suppliers shifting from demonstration to commercialization — a critical signal to procurement and roadmap teams.
Technology & Manufacturing Dynamics — What Changes in the Fab
Maskless lithography is not a single monolithic technology but a family of complementary approaches (SLM/DLT, laser direct imaging, digital micromirror arrays, etc.). Key manufacturing dynamics we document:
- Performance tradeoffs: resolution, stitch handling, and throughput form the trilemma. Recent tool generations have shifted the envelope, enabling sub‑2 µm L/S and, in some offerings, 1.0 µm performance without masks.
- Operational advantages: maskless systems reduce photomask lead times and NRE, enabling more design iterations and faster time‑to‑market for chiplet and heterogeneous designs.
- Sustainability and cost structure: adoption of solid‑state light sources and reduced mask fabrication lowers recurring costs and environmental footprint, impacting total cost of ownership and corporate ESG narratives.
- Integration imperatives: success hinges on close integration with metrology, die‑shift compensation, and warpage correction loops — tools must be evaluated within the broader process ecosystem, not in isolation.
Strategic Recommendations for 2026 Procurement & Roadmaps
PW Consulting’s advisory guidance is designed to be executable within 6–12 months. Our top recommendations:
- Run parallel pilot streams with at least two technology families (e.g., DLT/SLM and LDI) to de‑risk adoption and measure yield impact across representative substrates.
- Negotiate phased CapEx and performance milestones tied to throughput, yield uplift, and support KPIs rather than price alone.
- Invest in qualification instrumentation and process control for stitch verification and warpage compensation early in the pilot phase to reduce scale‑up surprises.
- Include supplier concentration and geopolitical scenarios in procurement decisions; diversify service contracts and spare parts sources where possible.
- Leverage co‑development agreements with vendors when targeting novel packages (chiplets, 2.5D/3D) to accelerate patterning recipe maturity and secure priority engineering resources.
Use Cases and Commercial Impact
Maskless lithography’s ROI is most compelling where design variety, low mask NRE, and rapid iteration are strategic advantages. Representative use cases covered in the report include AI/HPC interposers, 5G front‑end modules, advanced MEMS packaging, and high‑mix OSAT lines. In each instance we map expected ramp timelines, qualification gates, and realistic throughput assumptions so decision‑makers can translate forecasts into capital requests and product timelines.
Why PW Consulting’s Report Is Distinctive
This is not an academic market overview. Our deliverable is a decision‑grade toolkit combining:
- Transparent market forecasting with scenario stress tests calibrated to tool performance and adoption cycles.
- Vendor scorecards and red/green qualification checklists tailored to packaging engineering and procurement needs.
- Operational playbooks for pilot‑to‑volume transitions, including test recipes and metrology integration blueprints.
- Commercial negotiation templates and lifecycle cost models specific to maskless lithography procurement.
Next Steps
For teams facing 2026 capital allocation, supplier selection, or product roadmap choices, the timing for decisive action is now. PW Consulting’s full report contains the proprietary segmentation, vendor benchmarking matrices, and downloadable CapEx/ROI models that underpin the executive recommendations summarized here. To access the deeper datasets, scenario files, and actionable templates referenced in this release, please visit the report page and request the full brief.
For detailed analysis of this topic, please visit the official page: Maskless Lithography System For Semiconductor Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com