

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Rapid Growth — Environmentally Friendly Carbonization Furnace Market to Expand at a 10.25% CAGR During 2026–2032

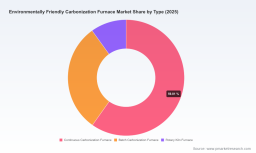
Environmentally Friendly Carbonization Furnace Market — Strategic Outlook for 2026 Decisions
PW Consulting’s latest market research on the Environmentally Friendly Carbonization Furnace market delivers a focused, decision-ready intelligence package for executives planning capital allocation, partnership strategies, and technology roadmaps in 2026. Built from a rigorous review of historical performance (2020–2025), regulatory developments, supplier capability maps, and primary interviews, the report synthesizes macro momentum and operational levers into a practical playbook. This press release summarizes the strategic highlights and competitive dynamics while preserving the granular regional and application-level splits for report subscribers.
Environmentally Friendly Carbonization Furnace Market
Snapshot: market trajectory and what it means for corporate strategy
The carbonization furnace market has moved from niche to mainstream industrial relevance. PW Consulting estimates the market reached approximately USD 276.4 Million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of roughly 10.25% through the 2026–2032 forecast window, reaching an anticipated market scale in excess of half a billion dollars by the end of the period. That pace signals sustained commercialisation of low-emission, enclosed carbonization systems—driven by demand for biochar, charcoal, and large-scale biomass waste processing—and creates a defined runway for differentiated suppliers and adopters to capture value.
Environmentally Friendly Carbonization Furnace Market
Market concentration remains moderate. The top three players account for under one-third of the market, and the top five for a plurality but not a majority—an environment that favors both incumbent expansion and targeted new-entrant strategies. For 2026 corporate planning, this combination of growth and fragmentation creates opportunities for selective M&A, strategic alliances, and rapid regional scaling where feedstock availability, regulatory stringency, and offtake partnerships align.
Environmentally Friendly Carbonization Furnace Market
Why 2026 is an inflection year
- Regulatory momentum : Heightened emissions standards in key markets and an increasing focus on carbon sequestration as a verifiable climate tool make enclosed, low-emission carbonization furnaces the de facto technical choice for commercial projects.
- Feedstock economics : Abundant agricultural and forestry residues in major production regions reduce raw material costs and enable both centralized and distributed processing models—supporting varied business models from equipment sales to contract processing and feedstock-to-carbon value chains.
- Product and process innovation : Recent upgrades in process automation, thermal control, and integration with downstream biocarbon handling are improving yield consistency and lowering O&M costs, narrowing the technology performance gap between continuous and batch systems.
- Commercial validation : New high-temperature pyrolysis pilots targeted at difficult waste streams and environmental remediation (for example, PFAS destruction) are demonstrating technical versatility, thereby expanding the addressable market beyond traditional soil amendment and fuel uses.
What the report contains — practical modules for 2026 action
PW Consulting designed this research to be operationally useful to CFOs, heads of technology, and business development leads. The full report (subscriber access) includes:
- Market sizing and an aggregated growth model that translates CAGR into capex and revenue scenarios under three adoption pathways.
- An emissions and compliance matrix mapping typical furnace configurations to major jurisdictional standards—useful for procurement specifications and permitting risk assessment.
- Techno-economic templates for continuous vs batch system selection, integrating feedstock variability, energy integration opportunities, and maintenance profile forecasting.
- Investment decision tools, including a discounted cash flow (DCF) starter model and a staged-capex approach to derisk pilot-to-scale rollouts.
- Supply chain risk heatmaps and procurement checklists that account for critical components, spare-part logistics, and export controls.
- Practical case studies and vendor selection criteria, illustrated by anonymized project economics and lessons learned from recent commercial deployments.
To preserve competitive value for subscribers, the report provides a full breakdown of regional and application-level market splits and vendor-level share analysis; these detailed tables and model inputs are intentionally not reproduced in this press release.
Competitive landscape — capabilities, recent moves, and strategic implications
The market is characterized by a mix of specialized niche manufacturers, broader equipment suppliers, and vertically integrated technology firms. Several vendors stand out for their product differentiation, recent strategic moves, and geographic footprints:
- GreenPower LTD (Europe, production facilities in multiple countries) has continued to push product evolution in 2026, rebranding and upgrading its continuous line to emphasize enhanced automation and thermal control. This move signals a shift toward higher-margin, system-integrated offerings that address operator-consistency and regulatory reporting needs.
- Beston Group (China) remains a volume-focused supplier with proven continuous operation track records. Its emphasis on multi-feedstock endurance and export-ready systems makes it a pragmatic partner for projects prioritizing uptime and cost efficiency.
- Wilson Biochar (USA) targets decentralized, on-site biochar production with simple, robust kilns designed for carbon sequestration and soil applications—an attractive option for agricultural and municipal clients seeking local processing solutions.
- CHAR Technologies (Canada) has executed strategic asset accumulation and project launches that indicate a move from technology provider toward vertically integrated biocarbon production. Notably, recent asset acquisitions and high-temperature pyrolysis pilots broaden its addressable market into specialized feedstock remediation and premium biocarbon segments.
- Several China-based OEMs (Zhengzhou and Tianjin firms) continue to compete on system customization and price-to-performance, supplying configurations optimized for common regional feedstocks and industrial charcoal production.
Collectively, these dynamics reveal two durable strategic postures for market players: product-centric differentiation (automation, emissions control, integration with downstream processes) and scale-centric approaches (cost leadership and wide distribution). For buyers and investors, supplier selection will increasingly hinge on validated emissions performance, integration capabilities, and long-term service commitments rather than initial equipment cost alone.
Recent developments to watch (strategic takeaways)
- Product upgrades that emphasize automation and process repeatability reduce operational risk and support premium pricing for equipment plus service contracts—favorable for vendors who can demonstrate field-proven thermal control and quality consistency.
- Asset and capability acquisitions by technology firms create pathways to vertically integrated models that capture more margin but require stronger project development and offtake capabilities—presenting partnership opportunities for equipment suppliers and financiers.
- Pilot projects targeting contaminant destruction and high-temperature pyrolysis broaden the market’s use cases and can justify public-private funding when environmental remediation objectives align.
Strategic implications for 2026 decision-makers
- Capex planning : Use staged investment approaches—start with pilot-scale continuous or batch systems tied to defined offtake or service contracts, then expand capacity tied to feedstock aggregation milestones.
- Vendor selection : Prioritize suppliers that can demonstrate emissions compliance, thermal process control, and long-term service capability. Factor in automation upgrades and control-system roadmaps when negotiating contracts.
- M&A and partnerships : The market’s moderate concentration makes targeted acquisitions viable routes to scale. Look for bolt-on opportunities that add feedstock access, offtake agreements, or IP in process automation and emissions monitoring.
- Market entry : For new entrants, focus on niche applications—such as PFAS remediation or premium biocarbon markets—where higher margins can offset initial development risks.
- Policy and permitting : Build regulatory compliance into project economics; enclosed, low-emission systems materially reduce permitting cycle time in regulated jurisdictions and can improve access to sustainability-linked financing.
- Offtake and product strategy : Differentiate by integrating downstream services (e.g., pelletizing, certification for carbon credits, soil amendment blending) to capture additional value across the chain.
How PW Consulting helps
PW Consulting provides tailored support to executive teams looking to act in 2026. Our advisory services include:
- Due diligence on vendor technology claims and field performance;
- Project economics modelling with sensitivity analysis across feedstock, yield, and regulatory scenarios;
- Deal structuring for strategic partnerships, offtake agreements, and staged-capex models;
- Regulatory navigation and emissions permitting support; and
- Integration roadmaps for combining carbonization systems with waste management, energy recovery, and biocarbon value chains.
PW Consulting’s full report translates the headline growth figures and competitive signals into the models and decision tools that 2026 leaders need. The summary above highlights the shapes of opportunity and risk; the complete publication contains the granular regional and application splits, vendor share tables, and downloadable financial templates that teams must have to finalize budgets and contracts. Those proprietary tables and interactive tools are available in the subscriber edition.
For organizations preparing 2026 capital plans or evaluating strategic entry into biochar, charcoal, and biomass waste processing markets, the window to act is now. The combination of sustained market growth, regulatory encouragement for low-emission systems, and active supplier innovation means early movers who align technology choices with compliance and offtake strategies will secure outsized value as the market scales.
For detailed analysis of this topic, please visit the official page: Environmentally Friendly Carbonization Furnace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com