

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global K–12 Education Furniture Market Poised to Reach USD 7.44 Billion by 2032, Expanding at a 5.25% CAGR (2026–2032)

K–12 Education Furniture Market 2026: Strategic Playbook for Procurement, Design and Growth
PW Consulting’s latest market research—the K–12 Education Furniture Market Report (base year 2025, forecast 2026–2032)—translates industry complexity into actionable guidance for school system leaders, district procurement teams, manufacturers and private investors preparing decisions in 2026. The K–12 furniture sector is no longer a commodity market of identical desks and chairs; it is converging design science, supply‑chain strategy and regulatory compliance into purchasing cycles that will define learning spaces for the next decade.
K 12 Education Furniture Market
Headline market dynamics you need to know
- Scale and trajectory: the global K–12 education furniture market reached approximately USD 5.2 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of about 5.25% across the 2026–2032 forecast. Our baseline scenario drives the market toward roughly USD 7.4 billion by 2032.
- Market structure: concentration metrics indicate a moderately fragmented sector — leading vendors capture a material but not dominant share of overall demand, creating space for regional specialists, innovative entrants and value-focused suppliers to influence procurement decisions.
- Demand drivers: district-level capital planning, classroom modernization programs, and pedagogical shifts toward active and inclusive learning underpin steady replacement and new‑build demand; meanwhile, cost pressures and supply constraints will shape how spend is allocated across product families and services.
Why this report matters for 2026 decision cycles
2026 is a pivotal planning year for many stakeholders: multi‑year capital budgets will be approved, supplier panels re‑negotiated, and specification frameworks updated to reflect post‑pandemic pedagogy and new safety standards. Our report is deliberately practical—designed to be used at the procurement table, in boardrooms, and on factory floors. It converts macro forecasts into tactical inputs: three procurement playbooks, vendor scorecards, a TCO (total cost of ownership) model tuned to K–12 lifecycles, and scenario maps that stress‑test decisions against price shocks and regulatory moves.
K 12 Education Furniture Market
Strategic implications — procurement and CapEx
- Procurement timing and bundling: With steady mid‑single digit growth expected, districts must move from ad hoc replacement to multi‑year bundle strategies that optimize delivery windows, installation labor and warranty coverage. Our model shows how shifting 12–24 month delivery windows can materially reduce lifecycle costs without cutting design quality.
- RFP design and supplier segmentation: The marketplace supports both national incumbents and regional manufacturers. We provide templated RFP language and evaluation rubrics that weigh durability, lifecycle service, and as‑delivered ergonomics ahead of unit price alone—an imperative in a market where short‑term savings often generate longer‑term replacement costs.
- CapEx scenario planning: Our scenario suite simulates steel and softwood price shocks, tariff escalations and logistic constraints to help finance teams size contingency reserves and determine the optimal amortization horizon for furniture investments.
Manufacturing footprint and sourcing decisions
Escalating input costs and trade policy volatility are major tactical considerations. Section 232 tariffs and elevated duties on steel and aluminum, combined with rising duties on softwood lumber and related products, have increased upstream cost volatility. Manufacturers and large buyers must rework supplier contracts to include clear escalation clauses, dual‑sourcing provisions and local content strategies where feasible. Our supply‑chain risk maps highlight pragmatic mitigations—nearshoring options by component, inventory buffer strategies calibrated to capital budgets, and lean manufacturing investments that lower exposure to raw‑material swings.
K 12 Education Furniture Market
Product and design strategy for competitive advantage
- Flexible and inclusive design is now table stakes: furniture that supports active learning, easy reconfiguration and universal access is driving specification changes across districts. The best commercial opportunities sit at the intersection of modularity, durability and easy maintenance.
- Sustainability and compliance: buyers must ensure conformance to low‑VOC material standards, structural integrity, ergonomics and fire safety codes. The report includes a compliance checklist and certification pathways that reduce time to acceptance during bid evaluation.
- Service as a differentiator: extended warranties, on‑site maintenance packages and retrofit services create recurring revenue opportunities for manufacturers and reduce lifecycle costs for schools. We quantify service premiums buyers can expect and show how to structure service SLAs in procurement contracts.
Competitive landscape — what incumbents and challengers are doing
The competitive field blends long‑standing American manufacturers with design‑led global players. Our competitive analysis synthesizes company strategies, capability maps and recent business developments to identify where market share will be contested in 2026.
- Established classroom specialists continue to capitalize on reputation for durability and national distribution networks. Expect these firms to double down on product line extensions that support active learning and to offer deeper warranty and installation packages.
- Design‑centric brands are positioning around research‑based solutions for collaborative learning, investing in seating innovations and modular table systems that reduce classroom reconfiguration time and labor costs.
- Recent company moves are signals of strategic intent: notable facility expansions and new product launches indicate rising demand and a push to capture higher value segments. Trade show engagement and thought‑leadership releases also point to intensifying competition around design credentials and specification influence at the district level.
Risk map — tariffs, materials and compliance
- Tariff exposure: high tariffs on steel, aluminum and some wood products have raised the effective cost base for many furniture components. Buyers should model tariff scenarios when comparing domestic versus imported bids.
- Raw material and logistics: scheduled duties and softwood tariff increases are likely to influence lead times and price steps for wooden components. Our procurement playbooks include contract language and inventory triggers to protect bidders and buyers alike.
- Regulatory compliance: safety and material standards remain non‑negotiable. The report’s compliance toolbox helps legal and design teams close acceptance gaps that otherwise delay installations and increase project costs.
What the report delivers — practical assets included
This is a decision‑ready report. Highlights of the deliverables:
- Interactive market forecast model (2026–2032) with scenario toggles for price shocks, CapEx shifts and pedagogy adoption rates.
- Procurement playbooks for small, medium and large districts—each containing RFP templates, scoring rubrics and sample contract clauses.
- Vendor benchmarking dashboards that compare capability sets (manufacturing footprint, warranty, retrofit services, sustainability certifications) without revealing proprietary client metrics.
- Supply‑chain risk maps and supplier diversification strategies tailored to component categories.
- Case studies and implementation roadmaps from recent district programs—covering specification, installation, teacher training and maintenance planning.
How to use the report in 2026 planning cycles
- For district leaders: use the TCO model to align furniture replacement cycles with bond timelines and maintenance budgets; leverage the RFP templates to move away from lowest‑price procurements.
- For manufacturers and suppliers: apply the competitor capability maps to identify whitespace—product families where modularity, service and sustainability create premium opportunities.
- For investors and consultants: the interactive forecast and concentration metrics reveal where consolidation or vertical integration could improve margins in a moderately fragmented market.
What we intentionally withhold — and why
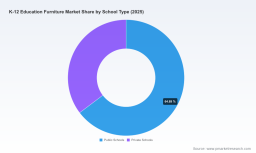
To preserve the strategic value of the full dataset, this release intentionally omits the granular segmentation numbers and detailed regional/application splits. The full report contains proprietary breakdowns by product family, region and school type, along with supplier‑level scorecards and downloadable datasets that power the interactive models referenced here. Those details are available through the PW Consulting report portal and are essential for transaction‑level decision making.
Next steps
PW Consulting’s K–12 Education Furniture Market Report is purpose‑built for 2026: it translates growth forecasts, concentration metrics and industry noise into procurement tools, risk mitigants and product strategies you can implement this fiscal year. For teams preparing budgets, re‑negotiating supplier contracts, or evaluating new manufacturing investments, the report reduces uncertainty and accelerates faster, better decisions.
To access the full dataset, interactive models, and vendor scorecards — and to schedule a briefing with our education‑sector analysts — visit our report page or contact PW Consulting’s K–12 practice. Our briefings are structured to convert these insights into an operational roadmap that your procurement, facilities and finance teams can act on immediately.
For detailed analysis of this topic, please visit the official page: K 12 Education Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com