

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Anti‑Acne Skin Patches Market to Grow at 8.5% CAGR, Rising from USD 750.6 Million in 2025 to About USD 1.33 Billion by 2032

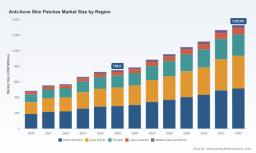
Anti-Acne Skin Patches Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting’s latest market study on Anti-Acne Skin Patches delivers a forward-looking, action-oriented roadmap for executives planning product, commercial, or M&A decisions in 2026. The global market — measured on a manufacturer/wholesale basis — reached an estimated USD 750.6 Million in our 2025 base year and is projected to expand at a compound annual growth rate (CAGR) of 8.5% through the 2026–2032 forecast window, reaching roughly USD 1.33 Billion by 2032. That pace signals not only sustained consumer demand but also a rapidly evolving competitive and regulatory landscape that will materially affect go-to-market choices over the next 18–36 months.
Anti Acne Skin Patches Market
Why this matters for 2026 corporate strategies
- Growth trajectory: An ~8.5% CAGR translates to a larger, more commercially attractive market by 2028–2030. Companies that position now around distinct product, supply and channel advantages will capture disproportionate share as adoption widens beyond early adopters.
- Product evolution: The category is maturing from basic hydrocolloid spot patches to differentiated propositions — medicated formulations, salicylic acid variants, and microneedle platforms designed for deeper cystic lesions. Each technology brings distinct regulatory, manufacturing and go-to-market consequences.
- Channel bifurcation: E-commerce-led launches continue to accelerate innovation adoption and brand discovery; traditional retail still underpins scale and margin stability. A deliberate omnichannel playbook is therefore essential.
- Concentration and consolidation potential: The category exhibits moderate concentration (CR3 ≈ 38.5%; CR5 ≈ 52.3%), suggesting opportunities for both challenger brands seeking carve-out growth and strategic buyers targeting manufacturing or private-label consolidation.
What the PW Consulting report includes (practical deliverables)
- Market sizing and trend maps (2020–2025 historical; 2026–2032 forecast) with scenario overlays for innovation, pricing and regulatory shocks.
- Go-to-market playbooks calibrated to three archetypes — incumbent CPG, digital-native skin-care brands, and contract manufacturers/OEMs — with prioritized tactical roadmaps for 12, 24 and 36 months.
- Commercial diagnostics: pricing architecture, SKU rationalization, channel margin waterfalls, and e-commerce funnel benchmarks to accelerate customer acquisition cost (CAC) payback.
- Competitive benchmarking and supplier matrix covering finished-product brands, private-label specialists and medical-grade hydrocolloid CMOs — with capability heatmaps on formulation, scale, regulatory certifications and lead times.
- Regulatory decision tree and compliance checklist for different product formulations (non-medicated hydrocolloid, salicylic acid OTC variants, and active microneedle products) aligned to US FDA and common international frameworks.
- Due-diligence templates for M&A and contract-manufacturing agreements, including recommended warranty and quality clauses tied to ISO and FDA expectations.
- Financial models and sensitivity tables that allow rapid scenario testing (pricing shocks, raw material disruption, accelerated adoption curves) to quantify valuation impact.
Note: This preview intentionally highlights the practical utility of the study while withholding detailed segment tables and raw datasets — those complete inputs and models are available with the full report.
Anti Acne Skin Patches Market
Competitive dynamics — who matters and why
- Hero Cosmetics, COSRX, Rael, Starface and Peace Out represent the most visible consumer-facing incumbents. Their strengths are brand equity, product-market fit, and repeatability of DTC/e-commerce execution.
- ZitSticka and other specialist innovators have moved the category toward clinically oriented micro-technology (micropoint/microneedle systems) aimed at tougher cystic acne cases — a technically differentiated but more capital- and data-intensive route to premiumization.
- Large consumer and healthcare groups (e.g., Church & Dwight, 3M) provide distribution scale and regulatory experience; their participation supports market legitimization but also increases competitive pressure on price and channel access.
- Contract manufacturers and OEM/ODM players (Amparo Medical, Hi‑Tech, ZenPro, DERMATECH, Taiki, Lessonia, Guangzhou Dunxin and similar material specialists) are central to value creation. They determine formulation feasibility, lead times, compliance cost, private-label economics and, ultimately, the margin profile for finished brands.
- Regional manufacturers and specialty materials producers (e.g., BenQ Materials) add technical differentiation in hydrocolloid substrates and active-delivery systems; control of higher-grade raw materials will be a competitively material advantage as quality and sustainability claims multiply.
Regulatory and technical context that will shape 2026 plays
- Regulation is a gating factor. Non-medicated hydrocolloid patches in the US are commonly regulated as Class I medical devices (product code KMF); patches containing salicylic acid within specified concentrations can fall under the OTC Monograph (21 CFR Part 333). Patches carrying active pharmaceutical claims or higher actives may trigger drug pathways and require establishment registration, listing and GMP adherence.
- Manufacturers with ISO 13485:2016, ISO 9001:2015 certifications and FDA registrations start with a structural advantage for B2B partnerships and cross-border launches.
- Hydrocolloid is the foundational raw material — its medical-grade specification, supply stability and sustainability profile are critical. Firms that secure diversified, audited sources of hydrocolloid will be better positioned on quality claims and margin stability.
- Reimbursement is not a near-term lever; anti-acne patches remain primarily over-the-counter consumer products with no recent CPT/DRG changes identified. Commercial models should therefore focus on retail and direct-to-consumer monetization rather than insurance channels.
2026 strategic playbook — prioritized recommendations
- For consumer brands seeking scale: prioritize a two-speed portfolio. Launch an e-commerce-first innovation (medicated or microneedle where clinically justified) to prove premium ASPs and consumer willingness-to-pay, while retaining a value-access hydrocolloid SKU for retail penetration and margin stability.
- For private-label and CMOs: invest in ISO/FDA readiness and analytic capability (format-specific stability data, in-vitro absorption metrics). These are the differentiators that secure high-margin OEM contracts and longer-term co-development mandates.
- For incumbents and strategic buyers: evaluate bolt-on M&A focused on either technical IP (microneedle delivery, active-formulation patents) or manufacturing scale in strategic geographies. Given the current moderate concentration, carefully targeted acquisitions can meaningfully lift share and improve channel control.
- Supply-chain resilience: dual-source medical-grade hydrocolloid, implement traceability for sustainability claims, and negotiate long-term fixed-price windows for polymer inputs to cushion margin volatility.
- Regulatory and evidence strategy: if introducing actives (e.g., salicylic acid), predefine the regulatory pathway (OTC monograph vs. drug submission), and invest in minimal but credible clinical or in-use wear studies to underpin marketing claims and reduce regulatory friction.
- Commercial activation: optimize the DTC funnel with subscription and replenishment mechanics for recurring usage patterns; use retail as discovery and fulfillment anchor. Tailor creative to audience cohorts — Gen Z prefers visible, 'fun' formats in social channels, while older cohorts value evidence and discretion.
Three rapid scenarios for 2026 boardrooms
- Consolidation scenario: Acquire a specialized CMO or microneedle IP to accelerate technical differentiation and secure manufacturing capacity — fast-track premiumization and margin expansion.
- Digital-first scenario: Lean into DTC, test higher-ASP medicated variants with limited distribution, and use data-driven CAC optimization to fund wider retail rollout in year two.
- Risk-managed scaling: Prioritize private-label contracts across multiple geographies, invest in ISO/FDA readiness, and use standardized formulations to scale EBITDA through volume while limiting R&D risk.
Each scenario is modeled in the full PW Consulting dataset with P&L, cash flow and ROI timelines tailored to company size and risk appetite. These models demonstrate how small differences in ASP, cost of goods and channel mix compound materially over the 2026–2030 horizon.
Anti Acne Skin Patches Market
Recent industry signals
- Private-label and manufacturing developments: Multiple manufacturers highlighted catalog expansion and capacity investments during 2025, indicating supply-side readiness to support both brand launches and higher-volume private-label programs.
- Product innovation: European and Asian manufacturers have publicly detailed next-generation hydrocolloid and delivery formats, accelerating differentiation and private-label options for brands seeking ‘market-ready’ premium SKUs.
- Market intelligence updates: Industry guides published in late 2025 emphasize vegan formulations and private-label capabilities as near-term procurement priorities for brand teams.
Next steps — how PW Consulting can help in 2026
- Custom commercial due diligence: accelerated 6–8 week DD for M&A targets or long-listing CMOs, including quality audits and margin reconciliation.
- Regulatory readiness audits: gap assessments and remediation plans for ISO/FDA alignment and OTC monograph strategy.
- Go-to-market sprints: 90-day playbooks for DTC launches, retail listings and subscription monetization with KPI scorecards.
For executives who want the complete datasets, supplier scorecards, model workbooks and the tactical playbooks referenced above, PW Consulting’s full Anti-Acne Skin Patches Market report contains the granular segment tables, region-by-region forecasts and executable annexes. This preview is intended to convey the strategic depth and decision-usefulness of the study while preserving the full analytical payload for report subscribers.
To procure the full report, request a briefing or commission a tailored engagement, visit our report page or contact PW Consulting’s industry team. Our models are built to be plugged directly into corporate planning exercises to accelerate 2026 decisions with clarity and confidence.
For detailed analysis of this topic, please visit the official page: Anti Acne Skin Patches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com