

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Global Fluid Management System Market Poised for 6.69% CAGR in 2026–2032, PW Consulting Finds

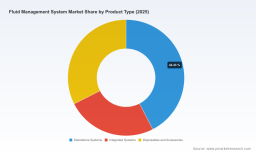
Fluid Management System Market — Strategic Imperatives for 2026 Decision-Makers
Executive summary
PW Consulting’s latest industry brief on the Fluid Management System market synthesizes a forward-looking viewpoint for senior executives planning capital allocation, portfolio reshaping, or M&A activity in 2026. Our baseline analysis — with 2025 as the base year and a forecast horizon through 2032 — shows the market expanding at a compound annual growth rate (CAGR) of roughly 6.7%. By our modeling, total industry revenue grows from the 2025 base to a materially larger market by 2032, underscoring a multi-year window of opportunity for differentiated products, consumable-driven revenue models, and digital service offerings.
Fluid Management System Market
Why 2026 is an inflection point
-
Clinical and procedural trends are accelerating structural demand. Continued migration toward minimally invasive procedures, higher procedure volumes in targeted specialties, and tighter integration between visualization and fluid control create product requirements that favor smarter, more precise fluid management platforms.
Fluid Management System Market -
Regulatory and reimbursement dynamics are tightening the bar for safety and performance. Recent clearances for novel urologic and irrigation platforms have shortened commercialization timelines for well-positioned incumbents while raising the certification hurdle for late entrants.
Fluid Management System Market -
Digitalization and service-enabled models are changing economics. Wireless telemetry, usage tracking, and consumable-recognition platforms are enabling subscription and lifecycle service revenues that materially improve unit economics for manufacturers and service providers.
-
Supply chain and materials considerations are now strategic constraints. Medical-grade polymers and precision tubing remain critical inputs; suppliers’ lead times and qualification processes can become gating factors for product launches and scale-up.
-
Market structure shows a moderate concentration: the top three firms account for a meaningful share, with the top five providing a majority of reported revenue. This balance creates both defensive and acquisitive strategies for mid-market firms seeking scale.
What the PW Consulting report delivers — practical, decision-ready content
-
Proprietary market model: a bottom-up, revenue-by-product and service model, stress-tested against alternative adoption curves and practice mix scenarios for the 2026–2032 forecast period.
-
Go-to-market playbooks: segmented commercial strategies for high-opportunity specialties, including consumables economics, hospital procurement tactics, and service/maintenance contracting templates.
-
Competitive intelligence and capability mapping: vendor scorecards covering product breadth, channel strength, innovation pipeline, and regulatory posture.
-
M&A and JV due-diligence templates: a checklist and valuation sensitivity framework tailored to fluid-management targets, including harmonization of consumable revenue, install base attrition, and cross-selling potential.
-
Supply-chain resilience playbook: raw-material risk matrices, qualification timelines for medical polymers and tubing, and contingency sourcing strategies.
-
Regulatory tracker and scenario planning: modeled impacts of likely regulatory developments on time-to-market, labeling constraints, and capital requirements for clinical studies or special clearances.
Competitive landscape — tactical implications for market players
The competitive field blends traditional surgical-device incumbents, specialist renal and critical-care suppliers, and industrial players applying digital field-fluid solutions to healthcare-adjacent use cases. Key strategic positions we highlight in the report include:
-
Stryker Corporation (Kalamazoo, Michigan): Strong in urology and arthroscopy with a strategy that couples advanced endoscopes and complementary fluid-control platforms. Recent product introductions emphasize integrated platform thinking — an important defensive play against modular competitors.
-
Boston Scientific Corporation (Marlborough, Massachusetts): Recently obtained regulatory clearance for a new urologic irrigation/distention platform, reinforcing an aggressive clinical and regulatory playbook aimed at expanding procedure-specific solutions.
-
Medtronic plc (Dublin): Focused on gynecology and hysteroscopy fluid systems, leveraging scale and procurement relationships in hospital systems to drive adoption of new devices.
-
Baxter International (Deerfield): Brings monitoring and critical-care fluid-management expertise to hospital workflows; plays to strengths in clinical monitoring integration rather than procedure-specific disposables.
-
Fresenius Medical Care (Bad Homburg): Dominant in renal dialysis platforms — a distinct but adjacent fluid-management ecosystem requiring different regulatory and service models.
-
CONMED, Hologic, Olympus, Karl Storz, Smith & Nephew, B. Braun, Cardinal Health, Ecolab, and others: Each occupies differentiated niches — arthroscopy, hysteroscopy, endoscopy visualization, irrigation pumps, or consumable/waste management — and collectively create a competitive matrix in which platform depth, consumable economics, and service coverage determine share shifts.
-
Graco Inc. (Minneapolis): Represents a notable cross-industry dynamic with its Pulse Mobile digital fluid management system for field operations, illustrating how industrial digitalization models can be adapted to healthcare service environments for inventory and dispensation control.
Recent developments shaping near-term tactics
-
Regulatory momentum: A recent 510(k) clearance for a major urology irrigation/distention device underscores that well-resourced manufacturers can accelerate clinical adoption by synchronizing clinical evidence and regulatory engagements early.
-
Platform launches: Product rollouts that combine visualization and fluid control — or pair disposables with digital telemetry — are setting new expectations among procurement committees for interoperability and total cost of ownership.
-
Material and supply realities: Market players report persistent qualification requirements for medical polymers and tubing; firms that lock down qualified suppliers and dual-source critical components will materially reduce launch risk and service disruptions.
Top strategic recommendations for 2026
-
Prioritize modular platforms with consumable annuity economics. Design product roadmaps that make it easy to upsell disposables, software licenses, and service contracts — these recurring revenues improve lifetime value and investor returns.
-
Invest in interoperability and data services. Hospitals are placing a premium on devices that integrate with visualization and EMR systems; telemetry-enabled fluid systems that provide usage analytics will command pricing premiums.
-
Secure supply-chain visibility for critical polymers and tubing. Create supplier qualification playbooks and strategic safety stocks for mission-critical components to avoid launch and replenishment delays.
-
Run portfolio stress tests with three adoption scenarios. Use our demand model to quantify how changes in minimally invasive procedure growth rates, reimbursed procedure volumes, or consumable attachment rates affect unit economics and break-even timing.
-
Be opportunistic in M&A: target niche firms that provide consumable lock-ins or unique integration capabilities. Smaller targets with strong physician adoption can be accretive without requiring broad manufacturing scale.
-
Strengthen regulatory and clinical evidence pathways early. A clear plan for evidence generation and regulatory submission shortens commercialization timelines and reduces probability of costly rework.
How PW Consulting’s report helps executives make 2026 decisions
-
Scenario-ready financial models calibrated to our 2026 baseline and 2032 forecast horizon, allowing CFOs to run sensitivity analyses on pricing, attachment rates, and service yields.
-
Commercial playbooks tailored for hospitals, ASCs, and field-service environments — with contracting language templates and KPIs for bundle offers.
-
Vendor scorecards and an M&A diligence checklist that compress weeks of competitive research into decision-ready insights for corporate development teams.
-
Supply-chain heatmaps and qualification timelines that highlight single points of failure and propose mitigation actions to maintain continuity during product scale-up.
Closing perspective
For leaders preparing budgets and strategic plans in 2026, the choice is clear: act to capture recurring revenue and data-enabled differentiation, or risk commoditization as incumbents deepen service linkages and new entrants apply cross-industry digital models. The Fluid Management System market is expanding at a mid-single-digit CAGR and will present multiple inflection points across product, service, and regulatory domains between now and 2032. Firms that align product architecture, supplier strategy, and go-to-market execution in 2026 will secure disproportionate returns over the forecast period.
Next step
PW Consulting’s full report contains the granular market sizing by segment, regional and application splits, vendor market shares, and downloadable financial models referenced above. For access to the complete datasets, vendor profiles, and model templates that underpin these insights, please visit our report page to request the full Fluid Management System Market dossier and executive briefing.
For detailed analysis of this topic, please visit the official page: Fluid Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com