

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 18.52% CAGR for Production of Lentiviral Vectors Market, Projecting USD 4,403.11 Million by 2032

Production of Lentiviral Vectors Market: Strategic Briefing for 2026 Decision-Makers
Executive summary
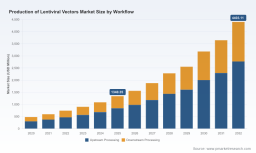
PW Consulting’s latest market study on the Production of Lentiviral Vectors provides a strategic playbook for organizations making manufacturing, partnership, and investment decisions in 2026. The global market has transitioned from a high-growth, fragmented opportunity to a capital-intensive, consolidation-prone industry. Our model shows the market expanding from USD 480.5 Million in 2020 to roughly USD 1.34 Billion in 2025, with a forecast trajectory that accelerates into the next decade — reaching approximately USD 4.40 Billion by 2032, underpinned by a compound annual growth rate of 18.52% across the 2026–2032 forecast window. Market concentration is meaningful but far from monopolistic: the top three players account for just under half of the market, while the top five approach six in ten market share, indicating sustained opportunity for focused CDMOs, technology providers and vertically integrated developers.
Production Of Lentiviral Vectors Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a pivotal year — commercialization contracts and new GMP capacity coming online will shift supply dynamics. Recent commercial supply agreements and facility acquisitions are beginning to unlock meaningful commercial-scale throughput, altering how sponsors evaluate supplier risk and timing for pivotal launches.
Production Of Lentiviral Vectors Market -
Regulatory inflection: Recent guidance and regulatory signals in late 2025 and early 2026 introduce greater flexibility for early‑phase manufacturing controls, while simultaneously raising the bar for analytical readiness at IND filing. This dual trend creates both tactical openings (faster path to clinic) and operational obligations (fit‑for‑purpose assays and scalable analytics).
Production Of Lentiviral Vectors Market -
Cost and input pressure: Raw material profiles — notably the outsized share of GMP-grade plasmids in upstream cost structures and the dominant contribution of vector-related materials to overall production cost — force a re-evaluation of transient transfection economics versus stable cell line strategies. Sponsors and CDMOs must weigh near-term speed against long-term cost predictability.
What the report delivers (actionable content)
-
Proprietary market model and scenario engine: A dynamic, downloadable financial model projecting total addressable market value across 2026–2032 under multiple adoption and pricing scenarios. The model is designed to be molded to sponsor-specific inputs (target indications, anticipated lot sizes, and scale-up timelines).
-
Decision frameworks for sourcing and capacity: Step-by-step guidance for build vs buy decisions, including a supplier selection scorecard, time-to-clinic versus cost-to-commerciality trade-offs, and a decision tree for when to invest in internal manufacturing or secure long-term CDMO capacity.
-
Technology and process playbook: Comparative assessment of upstream strategies (transient four‑plasmid HEK293 workflows versus emerging stable producer lines), downstream capture and purification approaches, and practical levers to improve yield and reduce cost-per-dose.
-
Regulatory readiness checklist: Practical CMC requirements derived from recent FDA guidance and industry best practice, with explicit checkpoints for IND initiation, analytical method qualification, and facility readiness for later-phase trials and commercial supply.
-
Commercialization and contracting templates: Structuring term sheets and manufacturing agreements to mitigate supply-chain concentration risk, including pricing escalators, technical transfer milestones, and contingency capacity clauses.
-
Provider benchmarking and capability map: Qualitative and semi-quantitative profiles of leading CDMOs and specialist providers, showing capability clusters, geographic strengths, and strategic moves. (Note: full, granular supplier scorecards and segmented market shares are available in the licensed dataset.)
Market dynamics and strategic implications
Our analysis shows three concurrent dynamics shaping near-term strategy. First, commercialization is transitioning from one-off clinical campaigns to repeatable, scalable supply arrangements: a wave of commercial supply agreements and new GMP sites will meaningfully de-risk supply chains for first movers. Second, the cost structure remains dominated by a small set of expensive inputs — particularly plasmids and vector-related consumables — which means process innovations that reduce plasmid dependence or materially improve upstream yield can change the unit economics of cell and gene therapy programs. Third, regulatory policy is evolving to enable innovation while insisting on methodological rigor: regulators are signalling greater flexibility on manufacturing expectations for early‑phase studies, but will require that analytical approaches are demonstrably fit‑for‑purpose as programs move toward pivotal phases.
Competitive landscape: what to watch in 2026
The competitive map blends large, diversified CDMOs with specialized niche players. Large integrators offer end-to-end services and can internalize scale-up risk; specialized providers focus on speed, flexibility and deep technical know-how in lentiviral processes. Recent market activity illustrates distinct positioning strategies we expect to intensify in 2026:
-
Integrated CDMOs (e.g., global biomanufacturing players): These firms compete on scale, regulatory track record and geographic reach. Their playbook centers on capturing late‑stage and commercial programs that require multi-site, multi-modal supply chains and rigorous quality systems.
-
Specialist lentiviral CDMOs: Boutique providers that concentrate on lentiviral-specific process expertise and facility designs can often offer faster technical transfer and bespoke process development. Their value proposition is higher touch and quicker iteration, which is attractive to early‑phase programs and academic spin-outs.
-
New capacity entrants: New facilities coming online — whether expansions by established CDMOs or greenfield centers — will redistribute negotiating leverage. Sponsors should model the effect of new capacity on lead times and pricing in their 2026 procurement cycles.
Company signals and recent developments
-
Strategic commercial supply agreements and facility acquisitions are altering the supply map. Multi-year manufacturing agreements for commercial CAR‑T supply and targeted acquisitions of FDA‑approved facilities are examples of near-term moves that will tighten the availability of commercial-scale slots for late-stage programs.
-
Flagship facility launches and capacity ramp schedules — including large-scale Centers of Excellence coming online in 2025–2026 — will create pockets of available supply, but also heighten competition for skilled process development talent and specialized raw materials.
-
Collaborations between CDMOs and research institutes are translating into earlier access to clinical-grade vector production for investigator-led trials, while also building pipelines that can scale with a commercial partner.
Operational imperatives for 2026
-
Inventory and supply‑chain resilience: Sponsors must secure strategic raw‑material agreements, especially for GMP plasmids and critical reagents. Given the high cost share of plasmids and the prominence of transient transfection workflows, options such as staged procurement, vendor qualification, and exploration of stable platform investments should be on all procurement roadmaps.
-
Analytics-first approach: Early investment in fit‑for‑purpose assays will speed regulatory interactions and reduce downstream risks. Analytical development scaled to clinical and commercial needs is no longer a downstream cost — it’s a strategic enabler of product comparability and release strategy.
-
Contract design aligned to commercialization: Manufacturing agreements should include clear technical transfer milestones, capacity reservation terms for commercial launch, and contingency plans for supply disruptions. Flexibility in release criteria for early trials must be matched to robust late‑phase comparability plans.
How to use this report
Executives and technical leaders will find immediately actionable outputs including a licensing-ready market model, supplier scorecards, build-vs-buy frameworks, and a regulatory checklist calibrated to recent FDA guidance. For procurement and business development teams, the report provides negotiation levers and scenario-tested pathways for securing capacity through 2028 and beyond. For R&D and process teams, the technology playbook identifies where to prioritize yield improvements, analytics, and cost reduction without compromising regulatory readiness.
Next steps and availability
PW Consulting’s Production of Lentiviral Vectors Market report is designed as both an analytical atlas and a practical toolkit for organizations navigating 2026’s shifting landscape. The publicly available brief presents high-level findings; licensed access unlocks the full market model, granular segment dashboards, provider benchmarking datasets, and downloadable contracting templates. Organizations planning strategic moves in 2026 — whether capacity commitments, internal build decisions, or M&A — will find the licensed dataset essential for evidence-based negotiation and capital planning.
To explore the complete dataset, supplier scorecards, and scenario model, please visit the PW Consulting report page or contact our commercial team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Production Of Lentiviral Vectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com