

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 8.75% CAGR for Automotive Occupant Sensing Systems and Whiplash Protection Market (2026–2032)

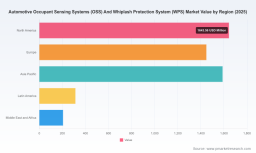
Automotive Occupant Sensing Systems (OSS) and Whiplash Protection Systems (WPS): Strategic Intelligence for 2026 Decision-Making
As OEMs accelerate cockpit electrification, advanced driver assistance system (ADAS) rollouts, and regulatory compliance programs, occupant sensing and whiplash protection technologies have shifted from optional differentiators to core safety and liability-management systems. PW Consulting’s latest market study — the Automotive Occupant Sensing Systems (OSS) and Whiplash Protection System (WPS) Market Report (base year 2025, forecast 2026–2032) — synthesizes proprietary datasets, regulatory mapping, and scenario-led forecasts to equip executives with the practical insight they need to make high-stakes 2026 investment decisions.
Automotive Occupant Sensing Systems Oss And Whiplash Protection System Wps Market
Why 2026 is a Pivotal Year
-
Macro momentum: The OSS & WPS market has expanded materially over the past half-decade, moving from roughly USD 3.12 billion in 2020 to USD 5.20 billion in 2025. Our forecasts, built on bottom-up OEM program analysis and validated by supplier interviews, anticipate the market will approach approximately USD 9.36 billion by 2032, reflecting a compound annual growth rate (CAGR) of 8.75% over the forecast horizon.
Automotive Occupant Sensing Systems Oss And Whiplash Protection System Wps Market -
Regulatory inflection points: New test protocols and safety regulations — notably Euro NCAP’s 2026 protocols calling for smarter, occupant-aware restraint systems and IIHS’s updated whiplash evaluation introduced in late 2025 — are re-shaping product requirements. Meanwhile, EU General Safety Regulation timelines for driver drowsiness and distraction detection are accelerating interior sensing adoption across vehicle segments.
Automotive Occupant Sensing Systems Oss And Whiplash Protection System Wps Market -
Technology convergence: Advances in sensor fusion (camera, radar, pressure mats, strain sensors), onboard AI/ML, and seat-integrated restraint actuation are creating new product architectures and value pools. For suppliers and OEMs, the question is no longer whether to invest, but how to architect scalable sensing platforms that satisfy safety, privacy, and cost constraints simultaneously.
What the Report Delivers — Practical, Executable Intelligence
The PW Consulting report is designed as an operational playbook for commercial, product and M&A leaders. It goes beyond high-level market sizing to provide:
-
Transparent market-sizing methodology and time-series datasets (2020–2025 historical; 2026–2032 forecast) that allow you to run alternate scenarios against your program win/loss assumptions.
-
Regulatory and testing impact maps that translate Euro NCAP, IIHS, and EU GSR changes into tangible BOM, validation, and program-timing implications for Tier‑1s and OEMs.
-
Technology roadmaps and technology-risk matrices covering sensor classes (pressure mats, strain gauges, camera-based systems, active head restraints, plus sensor fusion approaches), software/firmware dependencies, and semiconductor supply sensitivities.
-
Commercial playbooks: module-level pricing sensitivity analyses, margin-pressure scenarios under component-cost inflation, and contract-model recommendations for Tier‑1/OEM negotiations.
-
Competitive benchmarking and capability heatmaps for leading suppliers, with suggested partnership and M&A archetypes for incumbents and challengers.
-
Test cases and validation checklists, including templates to align engineering, regulatory, and procurement teams on certification timelines and liability testing needs.
-
An annex of interview transcripts, primary-sourced program wins, and a buyer’s checklist for selecting sensing system partners.
Market Structure and Competitive Dynamics
The OSS & WPS market is neither a pure commodity space nor a closed oligopoly; it exhibits moderate concentration with clear leadership pockets. Our concentration analysis shows the top-three suppliers together control near half of market revenues, while the top-five capture roughly three-fifths — a dynamic that creates meaningful scale advantages for incumbents while leaving accessible niches for focused challengers.
Key strategic implications for competitors:
-
Scale matters for platform-level investments. Firms with breadth across restraint systems and cabin electronics can amortize software and sensor platforms across multiple OEM programs.
-
Specialists can win by owning high-margin niches (e.g., child presence detection, premium seat-integrated systems, or validated whiplash solutions) and by partnering with system integrators for cross-sell.
-
M&A and partnerships are effective fast tracks to OEM qualification: consolidating sensing stacks or securing exclusive sensor or algorithm IP can materially shorten OEM timelines.
Company Positioning — Who’s Doing What
Our competitive chapter profiles incumbent strategies and tactical plays. Highlights include:
-
Autoliv Inc. (Stockholm) — continues to leverage its legacy in passive safety to position integrated occupant sensing and restraint architectures as risk-management platforms. Its recent exhibition of a holistic occupant-protection concept underscores a system-level approach combining pelvis, thorax and head restraint innovations.
-
Robert Bosch GmbH (Gerlingen) — strong in electronics and control units; Bosch is focusing on interior sensing modules (camera/radar) and integration excellence with vehicle safety ECUs.
-
Continental AG (Hanover) — emphasizing cabin camera and radar sensing, with software stacks tailored to occupant monitoring and airbag deployment optimization.
-
Magna International (Aurora) — rapidly scaling integrated interior sensing systems and in 2025 announced several production awards across OEM programs, signaling traction in camera/radar fusion for child presence and occupant monitoring.
-
ZF Friedrichshafen, Lear Corporation, Hyundai Mobis, Joyson Safety Systems, and Grammer — each brings differentiated strengths (seat systems, OEM supplier relationships, IR sensing algorithms, head restraint mechanics) and are executing a mix of organic and partnership plays to capture adjacent value.
Technology and Product Trends to Watch in 2026
-
Sensor fusion as the new baseline: Single-sensor approaches are declining in attractiveness for safety-critical functions. Effective OSS/WPS architectures will combine multiple sensor modalities with edge AI for robust classification and false-positive control.
-
Software-defined safety: Increasing reliance on algorithmic occupant classification and posture estimation shifts validation effort from hardware testing to continuous software-in-the-loop verification and over-the-air (OTA) update governance.
-
Seat-integrated intelligence: OEMs are re-evaluating the trade-off between overhead camera solutions and seat-embedded sensors (pressure mats, strain gauges) to balance privacy concerns, field-of-view issues, and cost.
-
Whiplash mitigation as test-driven productization: The IIHS whiplash protocol update and Euro NCAP requirements are accelerating adoption of dynamic head restraint solutions and seat structures that perform in standardized rear-impact tests; suppliers should align product development milestones to the updated protocols.
Strategic Playbook — Recommended Moves for 2026
-
For Tier‑1 Leaders: Double down on platform modularity and secure multi-year OEM programs. Prioritize sensor-signal-stack commonality to reduce variation and leverage CR3/CR5 scale to negotiate component costs.
-
For Fast Followers and Startups: Focus on IP-rich niches (proprietary occupant-classification algorithms, child presence detection sensors) and aim for co-development agreements with seat or restraint OEMs to accelerate validation cycles.
-
For OEMs: Specify sensor fusion and updateable software architectures in procurement RFPs to preserve future upgrade paths and to meet evolving regulatory requirements without costly hardware recalls.
-
For Investors and M&A Teams: Seek targets that offer either unique algorithmic assets or that close gaps in sensor modality coverage; prioritize companies with validated OEM launches or IIHS/Euro NCAP-relevant certifications.
Risks, Uncertainties, and Monitoring Triggers
-
Regulatory divergence: While some regions are tightening test regimes, differences in timing and test focus can create program synchronization risks. Maintain a regulatory watchlist and build flexible certification timelines into program plans.
-
Supply-chain volatility: Semiconductor and specialized-sensor availability remain potential choke points for ramping production. Long-lead procurement strategies and multiple-sourcing options are advisable.
-
Privacy and acceptance: In-cabin camera systems face privacy scrutiny. Companies must invest in privacy-by-design architectures and transparent data governance to secure OEM and consumer trust.
-
Liability and validation exposure: As algorithms influence safety-critical decisions, rigorous validation, traceability and OTA governance will be essential to mitigate product liability exposure.
How to Use the Report in 2026 Planning
This study is formatted for integration into enterprise decision processes. Typical use cases include:
-
Product roadmap alignment: Map your R&D milestones to IIHS/Euro NCAP certification timelines and the forecasted adoption waves in key vehicle programs.
-
Commercial negotiations: Use the pricing and margin templates to benchmark bids and structure long-term supply agreements with OEMs that include performance-based incentives tied to regulatory outcomes.
-
M&A diligence: Leverage the vendor deep dives and technology-risk assessments to validate target assumptions and to size integration synergies.
Concluding Perspective
The OSS & WPS market is at an inflection where regulatory mandates, real-world safety testing, and technological maturity are aligning to create sustained growth opportunities. For decision-makers planning 2026 investments, the strategic question is not whether to engage, but how to position: become the platform integrator, the algorithmic enabler, or the niche innovator. Each path requires a clear view of regulatory timelines, OEM program windows, and the competitive landgrab that has already become visible among the market’s leaders.
PW Consulting’s full report contains the granular segmentation, OEM program-level forecasts, company-level revenue modelling, and downloadable datasets that underpin the scenarios summarized here. To access the detailed tables, supplier scorecards, and executable playbooks — including the data inputs that informed the market sizing and the full list of references — visit the PW Consulting report page to download the complete study.
For detailed analysis of this topic, please visit the official page: Automotive Occupant Sensing Systems Oss And Whiplash Protection System Wps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com