

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
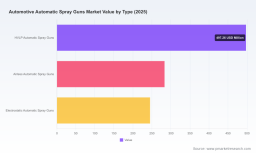
PW Consulting: Automotive Automatic Spray Guns Market to Reach USD 1,527.35 Million by 2032 at a 5.85% CAGR — HVLP (USD 497.26M) and OEM Coatings (USD 617.13M) Lead

PW Consulting Strategic Brief: Automotive Automatic Spray Guns Market — A 2026 Playbook
PW Consulting today publishes a strategic preview of our comprehensive Automotive Automatic Spray Guns Market report (base year 2025, forecast 2026–2032). The global market has moved decisively past the USD 1 billion threshold in 2025 and — driven by regulatory push, automation in vehicle finishing, and technology upgrades across OEM and refinishing channels — is forecast to expand at a compound annual growth rate (CAGR) of 5.85% through 2032. Under a central scenario this study projects the market rising from roughly USD 1.07 billion in 2026 to approximately USD 1.53 billion by 2032.
Automotive Automatic Spray Guns Market
Why this briefing matters to 2026 decision-makers
-
Timing matters: suppliers, OEMs, and investors must sequence product launches, capital investments, and regulatory compliance strategies over the 2026–2028 window to capture outsized returns as fleet- and plant-level upgrades accelerate.
Automotive Automatic Spray Guns Market -
Regulatory alignment is no longer optional: increasingly stringent VOC and overspray controls are reshaping procurement specs across major markets, creating near‑term demand for high-transfer-efficiency automatic systems and retrofits.
Automotive Automatic Spray Guns Market -
Margin pressure and opportunity coexist: raw-material inflation for critical nozzle alloys is squeezing manufacturing margins even as systems that offer measurable material savings (through reduced overspray and higher transfer efficiency) command price premiums.
-
Consolidation dynamics: the market exhibits moderate concentration among established global players while regional and niche manufacturers compete on cost, customization, and service — creating differentiated M&A, partnership, and go‑to‑market opportunities.
What the full report delivers (practical, executable content)
-
Robust market sizing and validated forecast model (2020–2032) with scenario analyses that stress-test demand under alternative regulatory and input-cost assumptions.
-
Technology deep dives across HVLP, airless, and electrostatic platforms: functional trade-offs, lifecycle cost models, robotic integration considerations, and retrofit economics.
-
End-user decision frameworks for OEM paint shops and the refinishing channel — capital expenditure templates, payback calculators for equipment upgrades, and vendor evaluation scorecards.
-
Competitive benchmarking and go‑to‑market playbooks: vendor capability matrices, channel strategies, pricing archetypes, and partnership templates for system integrators and paint chemistry suppliers.
-
Regulatory timeline and compliance impact assessment (notably North American and EU frameworks) mapping phased deadlines to equipment and process upgrades.
-
Primary research appendices: executive interviews with OEM maintenance leads, procurement teams, leading paint line integrators, and service network operators; supplier cost‑build models; and a downloadable dataset for financial planning.
Note: In keeping with this release’s “preview” purpose, we have intentionally withheld granular regional and application-level tables from this briefing. The full report contains the detailed splits, historic series, and downloadable models needed to drive procurement, R&D, and M&A decisions.
Competitive landscape: positioning and implications
-
Graco Inc. — With solutions that emphasize high transfer efficiency and robotic integration, Graco’s lineup is positioned for large OEM paint shop modernization projects and automated finishing cells. Their strength lies in systems integration, service networks, and product breadth for high-throughput lines.
-
SATA GmbH & Co. KG — Renowned for precision atomization and ergonomics, SATA drives adoption in environments where finish quality and reproducibility are mission-critical. Recent product previews underscore an emphasis on premium, precision‑engineered offerings.
-
Anest Iwata Corporation — A technology‑led supplier with a strong OEM pedigree, Anest Iwata’s updated portfolios aim to support both OEM process engineers and refinishing professionals seeking consistent atomization at scale.
-
Nordson Corporation — A leader in electrostatic and powder application systems, Nordson’s advantage is in high-volume, high-precision liquid and powder paint cells where transfer efficiency and minimal waste are primary KPIs.
-
EXEL Industries (Sames) — Sames focuses on modularity and adaptable application technologies across assembly lines, emphasizing ease of integration into existing paint shops and conveyorized systems.
-
Carlisle Fluid Technologies (DeVilbiss, Binks) — Their heritage brands deliver solutions optimized for transfer efficiency and serviceable designs that appeal to both OEMs and bodyshop networks, with aftermarket service as a margin lever.
-
Ningbo Lis Industrial and Zhejiang Rongpeng — These manufacturers are competitive on customization and price, targeting regional OEMs and refinishing channels with flexible supply arrangements and rapid product turnarounds.
Market concentration metrics reveal a moderate consolidation: the top three players account for a material share of the market while the top five capture a majority position. This structure supports both scale-driven advantage for system-level incumbents and profitable niches for specialized or low‑cost suppliers. For strategic buyers, the implication is clear — pursue bolt-on acquisitions to close capability gaps, or partner with regional manufacturers to secure price‑competitive supply while preserving margin on integration and service offerings.
Regulatory and input‑cost dynamics shaping 2026 playbooks
-
Regulatory drivers: North American and EU rules are accelerating replacement and retrofit cycles for spray equipment. Rules that mandate HVLP or equivalent technologies, and phased VOC restrictions extending through 2028, are catalyzing near-term procurement activity among OEMs and large refinish networks.
-
Material cost pressure: escalating prices for stainless steel and specialty nozzle alloys are increasing BOM costs for premium guns, compressing margins unless manufacturers optimize design or shift sourcing strategies.
-
Coatings evolution: widespread transition to waterborne chemistries and low‑VOC formulations increases the premium placed on atomization control and electrostatic adhesion efficiency — creating product differentiation opportunities for vendors who can validate material savings and finish quality.
Strategic playbook — priority actions for suppliers, OEMs, and investors in 2026
-
Prioritize modular electrostatic and HVLP product roadmaps that balance capital cost and lifecycle savings: buyers are seeking demonstrated paybacks within 24–36 months for high-efficiency equipment.
-
Embed robotic-compatibility and digital monitoring: suppliers that offer plug-and-play robotic interfaces and condition monitoring (consumable forecasts, nozzle wear analytics) will capture higher share in new build and retrofit opportunities.
-
Hedge raw-material exposure and redesign where possible: pursue alternative alloys, coating processes for internal parts, or volume contracts with key suppliers to stabilize COGS.
-
Develop service and consumable revenue streams: certified maintenance programs, consumable subscriptions, and on-site refurbishment can protect margins as hardware commoditization increases.
-
Use targeted M&A and partnerships to close capability gaps: for system integrators, acquiring nozzle-tech specialists, robotics control partners, or regional manufacturing footprints accelerates entry into new channels.
-
Prepare compliance-as-a-service offerings: as OEMs and bodyshops confront complex emissions rules, vendors that bundle equipment with compliance reporting and process consulting will strengthen buyer relationships.
-
Invest in pilot programs with training institutions and large refinish networks: institutional partnerships accelerate adoption and create demonstrable case studies (a recent supplier partnership with collision-repair training networks illustrates this pathway).
How to use the full PW Consulting report
The detailed PW Consulting report contains the granular regional and application splits, vendor scorecards, downloadable Excel models, and sensitivity analyses required to translate strategic intent into executable plans. If you are planning capital investments, revising product roadmaps, evaluating acquisition targets, or recalibrating sourcing strategies for 2026, the full dataset and expert recommendations will materially shorten your decision cycle and reduce execution risk.
About PW Consulting
PW Consulting is a strategic advisory and market intelligence firm serving industrial manufacturers, OEMs, and private investors. Our Automotive Automatic Spray Guns Market study blends proprietary supplier and end‑user interviews, supply‑chain cost modeling, and regulatory impact assessment to deliver actionable insight for executives charting a path through a rapidly evolving finishing ecosystem.
To request the full report, vendor scorecards, or a brief workshop to align 2026 investment priorities with your commercial roadmap, contact PW Consulting’s Automotive Practice. The full report includes the detailed splits intentionally omitted from this preview.
For detailed analysis of this topic, please visit the official page: Automotive Automatic Spray Guns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com