

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Portable Keratometer Market to Grow from USD 73.15 Million in 2025 to USD 115.5 Million by 2032 at a 6.75% CAGR — Handhelds Command 58.4% Share

Portable Keratometer Market: Strategic Imperatives for 2026 — PW Consulting Market Preview
Executive summary
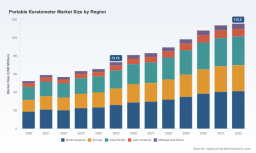
The portable keratometer market is entering a phase of steady maturation. After recovering from short-term volatility in the early 2020s, the global market expanded from a base of USD 52.35 Million in 2020 to USD 73.15 Million in our 2025 base year. PW Consulting’s forecast projects continued expansion through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 6.75%, reaching an estimated USD 115.5 Million by 2032. This preview frames why 2026 will be a pivotal year for product strategy, regulatory positioning, and channel development across OEMs, investors, and large purchasers.
Portable Keratometer Market
Why this preview matters for 2026 decisions
- Capital allocation and portfolio prioritization: With predictable growth and an identifiable set of incumbent and challenger suppliers, companies must choose where to allocate R&D and commercial spend to capture the highest-margin subsegments.
- Regulatory timing: Classification and conformity requirements in core markets create a narrow window in 2026 for product updates and filings to align with jurisdictional changes and sustain market entry momentum.
- Field deployment and channel design: The rise of mobile screening initiatives and mission deployments requires tight integration between device ergonomics, software ecosystems, and low-friction service models.
- Partnership and M&A targets: Mid-market consolidation and platform plays make a focused approach to bolt-on acquisitions and distribution partnerships an effective route to scale.
Market trajectory and what the numbers mean
The market’s historical performance through 2025 shows resilience and a return to growth after uneven years. Key takeaways from the top-line trajectory:
Portable Keratometer Market
- The market recovered and expanded meaningfully through 2023–2025, reflecting renewed capital investment and renewed adoption across both clinical and outreach use cases.
- Our forecast assumes a structurally higher baseline for portable keratometry driven by two durable trends: growing demand for decentralized eye care and ongoing miniaturization/algorithms that improve measurement fidelity in non-clinic settings.
- At the industry level the market concentration indicates a moderately consolidated supplier landscape — dominant players hold significant collective share while mid-tier vendors remain relevant through specialization and regional strength.
What PW Consulting’s full report delivers (practical scope)
The full PW Consulting market study is built as an executable playbook for 2026 decision-makers. It synthesizes quantitative forecasting with operational guidance across the product lifecycle. Core deliverables include:
Portable Keratometer Market
- Actionable demand forecasts (2026–2032) by product architecture and application use case, with sensitivity scenarios tied to supply chain and regulatory risk factors.
- Go-to-market matrices that map channel economics, pricing levers, and service model trade-offs for private practice, hospital procurement, outreach programs, and humanitarian deployments.
- Technology and product roadmaps translating incremental feature investments (e.g., wavefront-based keratometry, app integration, battery life improvements) into expected adoption curves and margin impact.
- Regulatory and reimbursement playbooks: step-by-step runs for 510(k) strategies in the U.S., CE/MDR pathways in Europe, and market-entry checklists for key APAC jurisdictions.
- Commercial diligence packages and a proprietary vendor scorecard for supplier selection or M&A screening, including risk-adjusted valuation inputs for deal teams.
- Field validation frameworks: KPIs, clinical validation protocols, and post-market surveillance templates that can be repurposed for pilots and rollouts.
Competitive landscape: positioning and implications
The portable keratometer space is populated by a mix of specialty innovators, established ophthalmic OEMs, and cost-focused regional manufacturers. PW Consulting’s competitive review focuses on capability vectors — portability, measurement fidelity, integration with biometry/refraction ecosystems, and field durability — rather than raw market share alone. Highlights for 2026 strategic planning:
- Micro Medical Devices (United States): Known for solutions such as the PalmScan PRO and K2000 portable probe, the firm demonstrates strength in biometry integration and mission-focused deployments. Their recent documented mission use underscores a proven fieldability proposition — an asset for public-health contracts and NGOs.
- PlenOptika (United States): As a leader in wavefront-based handheld refraction and keratometry, PlenOptika’s QuickSee Free Pro is positioned where clinical-quality measurement meets portability. Their 2025 Companion App update emphasizes the strategic importance of software-platform plays that extend clinical value and enable telemedicine workflows.
- NIDEK (Japan): With a history in ophthalmic instrumentation and a portable ARK offering, NIDEK is an example of an incumbent using brand trust and distribution depth to expand into mobile use cases — a defensive posture that well-resourced OEMs can replicate.
- Marco (United States): Marco’s portable ARK offerings illustrate how traditional refraction vendors can translate bench-top competencies into mobile devices. Their presence reinforces the competitive pressure on price-performance ratios in clinical segments.
- Devine Meditech (India): Regional manufacturers such as Devine Meditech compete on cost and application-specific usability. For global entrants, they are both potential acquisition targets and formidable price competitors in emerging markets.
- Reichert (AMETEK) and Huvitz: These firms represent broader ophthalmic portfolios where portable keratometers are strategic add-ons to an existing channel and servicing infrastructure — a critical consideration for buyers who value lifecycle support.
Recent developments that matter
- Early 2025 software upgrades from a leading handheld vendor underscore the accelerating role of companion mobile apps and analytics in converting device sales into recurring service relationships.
- Documented mission deployments in late 2025 show that field-validated device ecosystems have a competitive advantage in procurement by NGOs and mission-based programs; this drives demand for ruggedization and low-maintenance designs.
- Regulatory and standards activity is tightening: portable auto-keratometers are subject to Class II controls under U.S. regulation and face Class IIa conformity assessment in the EU, while ISO 15004-1:2020 remains a defining standard for non-invasive ophthalmic devices. These forces increase the cost and lead time of product introductions, favoring firms with established regulatory infrastructure.
Strategic playbook for 2026 (how to move)
- Regulatory-first product roadmaps: Build 510(k)/MDR timelines into development sprints. Early engagement with notified bodies and leveraging recognized standards accelerate approvals.
- Software as differentiation: Prioritize companion apps, cloud-based dashboards, and telehealth integrations that can convert one-time device sales into subscription revenue and lock-in clinical workflows.
- Field validation and evidence generation: Invest in pragmatic clinical trials and operational pilots in diverse settings — hospitals, outreach clinics, and supine-use scenarios — to substantiate claims and reduce buyer resistance.
- Channel segmentation: Tailor commercial models by customer cohort: direct sales and service bundles for large hospital groups; distributor partnerships and consumable bundles for smaller clinics and outreach programs.
- M&A and partnership criteria: Target assets that close gaps in software, regulatory dossiers, or field-service capabilities. Near-term inorganic moves should be evaluated with a 24-month integration plan focused on keeping the installed base operational.
- Cost-to-serve optimization: Design modular service offerings and remote diagnostics to lower after-sales costs, particularly important where devices are deployed in low-resource environments.
What we withhold in this preview — and why
In keeping with PW Consulting’s “preview” approach, we are intentionally not publishing detailed breakdowns by region, product-type shares, or application-level figures in this press release. These segmentation granularity and the underlying unit economics are central to the full report’s commercial value and are provided to subscribers and licenced clients who require precise, source-validated inputs for procurement models, investor diligence, and bid preparation.
Who should read the full report
- Strategic product leaders at ophthalmic OEMs evaluating next-generation portable platforms.
- Corporate development and private equity teams assessing acquisition targets or roll-up strategies in eye-care instrumentation.
- Procurement teams at hospital groups and public health agencies planning device rollouts in 2026 and beyond.
- NGOs and mission operators designing screening programs that rely on portable measurement accuracy and low support overhead.
- Regulatory and clinical teams building submission pathways and evidence plans to accelerate time-to-market.
Closing — actionable perspective for 2026
As the portable keratometer market moves from early adoption to broader clinical normalization, 2026 will reward organizations that combine product robustness with software-enabled workflows and regulatory rigor. PW Consulting’s full study supplies the operational blueprints, financial models, and vendor evaluations needed to convert market momentum into defensible business outcomes. For leaders planning capital deployment, product launches, or market entries in 2026, the difference between a competitive win and a costly delay will be in how these strategic vectors are sequenced and executed.
To access the comprehensive dataset, proprietary segmentation, and executable playbooks referenced in this preview, PW Consulting invites decision-makers to review the full Portable Keratometer Market report and accompanying advisory services.
For detailed analysis of this topic, please visit the official page: Portable Keratometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com