

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Industrial Centrifuge Machines Market Reaches USD 9.53 Billion in 2025, Set to Expand at a 5.12% CAGR Through 2026–2032

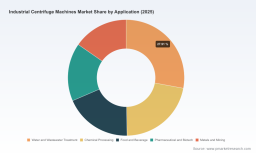
Industrial Centrifuge Machines Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As the industrial centrifuge market moves from steady recovery into the next phase of structural growth, procurement leaders, OEM strategists and private-equity sponsors face a narrowing window to convert market momentum into durable competitive advantage. PW Consulting’s new Industrial Centrifuge Machines Market report (base year 2025; forecast 2026–2032) synthesizes seven years of historical patterns and a seven-year forecast horizon to deliver the pragmatic intelligence organizations need for decisive action in 2026.
Industrial Centrifuge Machines Market
Snapshot: Where the market stands and where it is headed
Our analysis shows the market expanding from approximately USD 7.12 billion in 2020 to USD 9.53 billion in 2025, with an expected continuation of growth through the forecast window to reach roughly USD 13.47 billion by 2032. Underpinning this trajectory is a compound annual growth rate of about 5.12% across the 2026–2032 forecast period. Market concentration is moderate: the top three players account for roughly 32.4% of market revenue, while the top five collectively approach 48.7%, a structure that creates both scale advantages for incumbents and opening space for focused challengers.
Industrial Centrifuge Machines Market
Why this report matters for 2026 decision-makers
- Timing for procurement and CAPEX planning: With component and raw-material pressures persisting into 2026 — including firm hot-rolled coil steel pricing and volatility in specialty steels and nickel — total cost of ownership (TCO) assumptions embedded in long-cycle capex projects must be revisited now. Our report provides scenario-adjusted TCO templates that tie material-cost volatility to realistic procurement timelines.
- M&A and portfolio carve-outs: Moderate concentration and uneven product innovation between OEMs create differentiated acquisition opportunities. The report’s M&A playbook evaluates strategic targets by technology adjacency, service-backlog quality and aftermarket margin potential, helping sponsors avoid overpaying into commodity segments.
- Service and aftermarket monetization: As equipment lifecycles extend, aftermarket services become primary margin drivers. We map the service revenue levers — remote diagnostics, spares strategies, modular retrofit kits — and show how to structure service-level agreements that protect margins amid component-cost inflation.
- Technology transition and product roadmaps: From high-speed separators for bioprocessing to large decanter units for oil recovery, technology bets influence customer lifetime value. The report offers a practical framework to prioritize R&D investment, evaluate retrofit vs. replacement economics, and assess go-to-market sequencing for new models.
- Supply-chain resilience: Geopolitical drivers such as continued U.S. steel tariffs and shifting nickel supply affect lead times and component availability. We provide supplier-risk heatmaps, dual-sourcing templates and inventory strategies calibrated to realistic lead-time distributions.
What practitioners will find inside (practical, operational, and prescriptive)
This is not a high-level market narrative. The PW Consulting report is organized around deployable workstreams for commercial and operations teams:
Industrial Centrifuge Machines Market
- Actionable procurement playbooks with bid-evaluation scorecards, supplier negotiation scripts and indexed material-cost clauses designed for heavy-equipment frameworks.
- Unit-level TCO models allowing side-by-side comparison of sedimentation decanters, filtering/clarifier solutions and high-speed separators — with configurable inputs for throughput, solids loading, energy costs and spare-parts regimes.
- Manufacturing-cost build-ups and factory footprint decision matrices that quantify savings from regional sourcing, modular assembly and strategic outsourcing.
- Technology adoption roadmaps that grade innovations by maturity, margin impact and retrofit feasibility (including digital sensors and automation retrofits for predictive maintenance).
- Commercial playbooks: channel strategies, aftermarket pricing models, trial-pilot templates and OEM-to-end-customer case studies that show how to convert proof-of-concept into signed, repeatable contracts.
- Scenario-based demand forecasts that stress-test strategies across energy-market cycles, regulation changes and raw-material shocks.
Competitive landscape: tactical read on the players you need to watch
The market is populated by a blend of global system integrators, specialised centrifuge manufacturers and legacy family-owned players. Our competitive assessment emphasizes capability clusters rather than an index of share-of-wallet alone — the clearest differentiators are technology breadth, aftermarket footprint and domain-focused R&D.
- Alfa Laval AB (Lund, Sweden) — Deep product breadth across decanters and high-speed separators; recent launches such as next‑generation high-speed separators and fermentation-optimized models signal a play to dominate bioprocessing and alternative-protein segments. Expect continued investment in hermetic designs and application-specific packages.
- GEA Group AG (Düsseldorf, Germany) — A strong presence in food, dairy and pharma separations with recent strategic expansion into smart sensor solutions via an acquisition that augments its decanter and water-treatment portfolio. GEA’s integration of sensors and digital services is a template for protecting aftermarket margin.
- ANDRITZ AG (Graz, Austria) — Positioned strongly in heavy industries (mining, chemicals) with proven solid-liquid separation systems. ANDRITZ competes on engineered solutions and lifecycle services for capital-intensive customers.
- Flottweg SE (Vilsbiburg, Germany) — Specialized high-performance decanters and separators; the opening of a new process center in 2026 demonstrates explicit emphasis on application-driven process development and customer co-innovation.
- Regional specialists and heritage manufacturers — Companies such as Western States Machine Company, Mitsubishi Kakoki Kaisha, FLSmidth, Hiller, Thomas Broadbent, Pieralisi, HAUS and Ferrum maintain strong domain credibility in specific verticals (chemicals, sugar, marine, mining and pharma). Their strengths are often localized service networks and niche product variants that command premium pricing in complex process applications.
These firms are not monolithic. The more successful competitors are those that layer digital services and targeted application know-how over core mechanical IP, thereby increasing customer switching costs and building recurring revenue streams.
Macro headwinds and operational “noise” that will shape 2026 outcomes
- Raw-material inflation: Sustained firmness in hot-rolled coil steel prices and volatility in specialty steels and nickel are elevating cost bases for stainless- and corrosion-resistant components. Manufacturers and buyers must incorporate these dynamics into contract indexation and hedging strategies.
- Trade policy and tariffs: Elevated steel tariffs and changing import exemptions are reshaping localization economics in several markets. This has direct consequences for sourcing decisions, lead times and the economics of regional assembly.
- Shift toward higher-value applications: High-growth pockets — notably biopharma/bioprocessing and certain wastewater-treatment subsegments — are driving demand for high-speed separators and hermetic designs, increasing the importance of domain expertise versus pure mechanical scale.
- Digitization and sensors: Strategic plays such as the integration of smart-sensor solutions into decanter systems are increasingly determining aftermarket potential. Proven remote monitoring capability can reduce mean-time-to-repair and transform spare-parts strategies.
Five pragmatic strategic moves for 2026
- Re-price and re-contract with indexation: Include material-cost index clauses and shorter re-bid windows for long lead-time components to protect margins against steel and specialty-metal swings.
- Prioritise service-led growth: Shift commercial focus to bundled equipment + service contracts, standardized retrofit kits and predictive-maintenance subscriptions that raise lifetime value.
- Pursue tuck-ins, not trophies: Identify acquisition targets that bring immediate aftermarket capability, vertical-market penetration or sensor-enabled retrofits rather than headline-grabbing scale alone.
- Modularize manufacturing: Break product families into modular subsystems that can be assembled regionally to avoid full localization costs while reducing exposure to tariffs and freight volatility.
- Operationalize digital pilots: Run two time-boxed pilots to validate remote-monitoring ROI and service-uptake economics before scaling across installed bases.
What the full PW Consulting report unlocks (exclusive to subscribers)
The public brief is designed to give leaders the diagnostic clarity they need. The full report includes the proprietary models and data tables necessary to operationalize the recommendations above: vendor-level benchmarking, downloadable TCO spreadsheets, detailed procurement RFP templates, country- and application-level demand scenarios, and unit economics for replacement vs. retrofit decisions. It also contains a granular competitive matrix that maps product portfolios to validated performance metrics and after-sales capabilities.
We intentionally withhold detailed segment-by-segment figures and some proprietary scenario outputs in this press brief to provide clients with a compelling reason to access the complete dataset and modeling suite. That level of granularity is essential for contract-level negotiations, M&A valuation workstreams and precise CAPEX planning.
Final thought
2026 is a pivotal year: incremental growth will reward those who move quickly to protect margins and capture aftermarket share, while strategic missteps in sourcing or product prioritization risk eroding returns. PW Consulting’s Industrial Centrifuge Machines Market report equips leaders with the evidence-based templates, competitive insights and scenario tools required to make those calls with confidence.
To access the full dataset, models and playbooks that underpin these conclusions, please visit PW Consulting’s Industrial Equipment research page or contact our Industrial Systems practice for a briefing and data access options.
For detailed analysis of this topic, please visit the official page: Industrial Centrifuge Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com