

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Robust 5.82% CAGR for the Multi-Parameter Monitoring Equipment Market Through 2032

Multi-Parameter Monitoring Equipment Market — 2026 Strategic Preview for Executives
Executive summary
PW Consulting’s forthcoming Multi Parameter Monitoring Equipment Market report distills five years of historical performance and a seven-year forecast into a practical decision-making tool for 2026. The market has demonstrated steady expansion across the 2020–2025 window and is projected to continue growing into the next decade. Our base-year analysis (2025) establishes a clear starting point for scenario-building, while the report’s forecast horizon (2026–2032) quantifies momentum and inflection points that will matter for capital allocation, procurements, product roadmaps, and M&A strategies.
Multi Parameter Monitoring Equipment Market
Market trajectory and macro view
After a recovery and consolidation phase through the early 2020s, the global multi-parameter monitoring market entered 2025 on a stronger footing. Our baseline indicates the market reached a significant industry milestone in 2025, and we project a mid-single-digit compound annual growth rate (CAGR) of approximately 5.8% through the 2026–2032 forecast period. Under current underlying assumptions—ongoing hospital modernization programs, expanded ambulatory and homecare monitoring adoption, and steady regulatory clarity—this trajectory yields meaningful upside for vendors, integrators, and systems purchasers over the medium term.
Multi Parameter Monitoring Equipment Market
Two implications follow immediately for 2026 planning. First, capital planners should prepare for a sustained procurement cycle that favors modular, interoperable systems that can be scaled across acuity tiers. Second, investors and product leaders must prioritize feature differentiation that addresses mobility, non-invasive parameter expansion, AI-driven early warning and ease-of-use for stretched clinical teams.
Multi Parameter Monitoring Equipment Market
Why this report matters for 2026 decisions
- Actionable revenue and demand scenarios: We translate top-line growth into procurement demand curves and capital replacement rhythms so CFOs can align CAPEX with clinical needs without overcommitting to legacy architectures.
- Vendor-selection frameworks: The report provides a structured rubric—weighted scoring and risk overlays—to evaluate partners across performance, regulatory standing, service footprint, and total cost of ownership.
- Product and R&D prioritization: R&D leaders will find near-term feature roadmaps that matter (e.g., wearable continuous monitors, AI early-warning integrations, and MRI-compatibility strategies) and where to stage investments to maximize adoption.
- M&A and partnership playbooks: For corporate development teams, we identify target archetypes—technology enablers, regional scale players, disposables suppliers—and model valuation sensitivities in a 2026 market context.
Competitive landscape — what leaders are doing
The competitive field is shaped by legacy medical device incumbents, nimble regional OEMs, and software-centric entrants. Rather than enumerate market shares here, the report synthesizes qualitative and transactional signals to map where competitive advantage exists today and where it will matter in 2026.
- Philips (Amsterdam) — A platform-led incumbent leveraging its IntelliVue franchise and recent software updates that embed AI-driven early warning scoring. Strategic posture: deepen system-level installations and drive lifecycle service revenue through software-enabled features. For buyers: prioritize interoperability clauses and software assurance in procurement.
- GE Healthcare (Chicago) — Focused on modular critical-care monitors and recent mobility innovations (wearable continuous monitors). Strategic posture: push mobility and modularity to capture in-hospital transport and step-down care. For hospitals: test wearable pilots against integration costs and nursing workflow impacts before scale rollout.
- Dräger (Lübeck) — Strong in acute care with ventilation integration and recently cleared regulatory extensions for advanced monitors. Strategic posture: capitalize on OR/ICU integrations. Recommendation: prioritize legacy pull-through opportunities in ventilator-heavy units.
- Mindray (Shenzhen) — Competes on value and scale, evidenced by large public-sector deployment wins. Strategic posture: accelerate affordability at scale across emerging markets. Procurement teams should quantify lifecycle support tradeoffs when assessing lower-cost entrants.
- Nihon Kohden (Tokyo) — Differentiates via high-acuity waveform analytics and extended physiologic monitoring. Strategic posture: focus on tertiary hospitals and neuromonitoring use cases. Clinical leaders should align vendor selection to specialty service lines that demand premium monitoring fidelity.
- Masimo (Irvine) — Advances non-invasive multi-parameter technologies and sensor innovation. Strategic posture: target perioperative and sedation monitoring markets where non-invasive measurements reduce procedural burden.
- Baxter/Hillrom (Deerfield) — Integrates monitoring with intelligent bed systems—an attractive proposition for value-based-care programs seeking operational efficiencies.
- Others (Spacelabs, Schiller, Zoll, Contec, Edan) — Each occupies focused niches (ambulatory, MRI-compatible, EMS transport, cost-effective clinics, wireless connectivity). Strategic posture: partners for OEM integration, regional scale, or specialized clinical segments.
Recent market moves support a bifurcated future: incumbents are layering software and services onto installed bases, while lower-cost vendors and point-solution innovators are capturing greenfield deployments and peripheral care settings. The full report includes a vendor matrix with go-to-market vectors, recent milestones, and scenario-tested vendor risk scores for procurement committees.
Regulatory, standards and operational dynamics to watch
- Regulatory baseline: Multi-parameter monitors are regulated as medium-risk devices in key markets and typically require formal premarket pathways. Regulatory timelines materially influence launch sequencing—an essential variable for 2026 go-to-market plans.
- Standards compliance: Conformance to medical device performance and pulse oximetry standards remains a gating factor for hospital acceptance, particularly in critical-care environments.
- Reimbursement and care-delivery incentives: Critical-care and remote-monitoring reimbursement pathways shape hospital prioritization. Understanding the coding and billing levers for monitoring time and telemonitoring is a near-term advantage.
- Supply-chain pressures: Recent commodity cost inflation for medical-grade materials and intermittent component constraints make multi-sourcing and design for manufacturability non-negotiable elements of commercial planning.
- Legacy risk and recalls: Historical product issues have long tails; buyers should factor remediation history and spare-parts availability into vendor assessments.
Report contents — practical and operational deliverables
Our report is structured to convert market intelligence into executable plans. Highlights include:
- Executive dashboards that translate the macro CAGR into hospital-level demand scenarios and procurement timelines;
- Vendor-selection templates with weighted scoring, contract negotiation playbooks, and service-level agreement (SLA) exemplars tailored to monitor lifecycles;
- R&D and product prioritization matrices that rank feature investments by adoption velocity and revenue uplift potential;
- Supply-chain resilience checklists and alternate-sourcing maps to mitigate material-cost and lead-time risk;
- M&A and partnership scouting lists with financial multipliers and integration risk assessments for 2026 deal cadence;
- Regulatory path templates for common product extensions and a compliance checklist mapped to major markets.
Strategic recommendations for 2026
- Procurement: Shift from single-vendor consolidation to hybrid sourcing—secure core platform continuity with incumbents while running competitive tenders for modular and peripheral devices to capture cost efficiency and innovation.
- Clinical adoption: Start with clinically focused pilots—mobility and wearable monitoring—structured with pre-agreed metrics (nurse time, alarm fatigue, transfers avoided). Use these pilots to build adoption playbooks for scale.
- Product/R&D: Prioritize interoperability (open APIs and standards compliance), AI-enabled early-warning features, and sensor innovation that reduce consumable dependency.
- Commercial: Monetize software and services—bundle predictive analytics and uptime guarantees into managed-service contracts to stabilize recurring revenue.
- M&A: Target bolt-on acquisitions that provide connectivity stacks or specialized sensors rather than expensive platform migrations; emphasize cultural fit and installation-service capability.
- Risk management: Protect against material-cost spikes with dual-sourcing clauses and design adjustments for alternative polymers and elastomers that meet regulatory standards.
What we intentionally omit here — and why
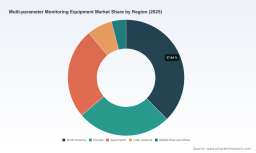
To preserve the report’s value as a subscription-grade, actionable asset, this preview deliberately omits granular segment and regional revenue breakdowns, specific market-share percentages, and certain scenario tables that quantify micro-market dynamics. Those data sets are included in the full report along with downloadable models and vendor scorecards which purchasers can use directly in procurement and capital planning processes.
Next steps and how to use the full report
For executive teams preparing 2026 budgets and strategic initiatives, the full PW Consulting report offers the necessary depth to convert market trends into operational plans. It is designed to be read across functions—clinical engineering, procurement, product, and corporate development—so each can extract role-specific actions. We recommend the following immediate steps upon accessing the report:
- Run the included scenario model against your hospital system’s bed mix to estimate replacement windows and CAPEX timing;
- Apply the vendor-selection rubric to your current suppliers and short-list two alternative providers for trial deployments;
- Use the R&D prioritization matrix to realign next-12-month product roadmaps to high-adoption feature sets;
- Map supply-chain recommendations against your current contracts and initiate contingency sourcing where single-source risk exists.
Methodology note
The analysis synthesizes historical shipment and revenue data, primary interviews with hospital procurement and clinical engineering leaders, publicly disclosed vendor financials and press releases, and regulatory timelines. Forecasts apply scenario-based demand modeling that accounts for capital replacement cycles, technology-led adoption in ambulatory settings, and macroeconomic sensitivity to material-cost inflation and reimbursement drivers.
Closing
For leaders who need both the high-level strategic view and the executable instruments to act in 2026, PW Consulting’s Multi Parameter Monitoring Equipment Market report is built as a playbook—not just an analysis. It balances market-scale perspective with purchase-ready tools. To access the granular datasets, vendor scorecards, and the interactive forecast model, please visit the PW Consulting report page to obtain the full document and supplemental assets.
For detailed analysis of this topic, please visit the official page: Multi Parameter Monitoring Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com