

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Patient Record Management Market Poised to Expand at a Robust 6.41% CAGR Through 2032

Patient Record Management Market: Strategic Outlook and Action Plan for 2026
As healthcare organizations move from episodic digitization to continuous digital transformation, patient record management is changing from an operational necessity to a strategic asset. PW Consulting’s latest market study — with a base year of 2025 and a forecast horizon through 2032 — quantifies that transition: global patient record management revenues rose from USD 31,450.2 Million in 2020 to USD 41,691.72 Million in 2025, and our forecast points to a market that will approach USD 64,362.93 Million by 2032, growing at a compound annual growth rate (CAGR) of 6.41% over the forecast period. This research is designed to help executive teams convert that macro momentum into defensible 2026 decisions without getting lost in vendor noise or isolated feature comparisons.
Patient Record Management Market
Why this report matters for 2026 strategic planning
-
Timing: Capital allocation and program launches in 2026 will determine who captures scale advantages through the end of the decade. Market growth is steady and predictable at the macro level, but winners will be those who align architecture, procurement, and clinical workflows concurrently.
Patient Record Management Market -
Risk vs. reward: Compliance, data portability, and patient expectations mean that tactical decisions (e.g., a migration path, a contract term) carry strategic consequences. Our analysis highlights where short-term cost savings create long-term operational debt.
Patient Record Management Market -
Competitive positioning: The top vendors remain influential, but the market structure leaves room for differentiated entrants and consolidation plays. Understanding concentration metrics and capability clusters is central to partnership and M&A playbooks.
High-level market dynamics that should drive 2026 decisions
-
Interoperability is now table stakes. Regulatory and standards momentum — from HITECH/HIPAA enforcement through ONC’s information-blocking rules and the near-universal adoption of HL7 FHIR APIs — is forcing architecture-first decisions. Organizations that standardize on API-centric exchange and enforce FHIR-based interfaces will reduce integration costs and downstream lock-in.
-
Cloud-first deployments accelerate value capture. Our fieldwork and vendor intelligence show cloud-based delivery models outpacing legacy on-premise refreshes for new implementations, driven by total cost-of-ownership, speed of feature delivery, and managed security offerings.
-
AI and analytics are shifting from pilot to production. Vendors and health systems are embedding AI for summarization, coding assistance, and population health signals. However, productionizing these capabilities requires disciplined data governance and validated clinical workflows to avoid liability and clinician burnout.
-
Regulatory and reimbursement levers influence buyer economics. Programs that reward certified use of EHRs, plus specific incentives and penalties, materially change adoption curves in certain provider segments. Compliance frameworks such as GDPR’s constraints on health data must be embedded in cross-border strategies.
Competitive landscape — strategic takeaways
The market shows a moderate level of concentration. The top three vendors account for a meaningful share of industry revenue, and the top five together represent a clear majority, but the remainder of the market remains fragmented — a situation that yields both strategic risk and opportunity for buyers and investors. Our report’s vendor maps and scorecards synthesize capability, scale, specialty focus, and partnership depth to help decision-makers prioritize engagement models.
-
Epic Systems Corporation — A dominant force among integrated health systems, Epic’s platform emphasizes deep clinical workflows, extensive interoperability via FHIR, and patient engagement tools. Recent product enhancements center on AI-enabled summarization and cross-institutional continuity.
-
Oracle Cerner — Known for its enterprise-scale EHR suite, Cerner is advancing analytics and machine learning through cloud partnerships and integration with wearables and remote monitoring. Strategic cloud alliances are reshaping its value proposition for large health systems.
-
Allscripts Healthcare Solutions — Focused on ambulatory and mixed environments, Allscripts combines EHR capabilities with patient portals and revenue-cycle features; it remains a competitive option for organizations balancing clinical and financial workflow integration.
-
NextGen Healthcare — Strong in specialty and ambulatory segments, NextGen brings population health tooling and mobile access that appeal to mid-market specialty providers who require configurable clinical workflows.
-
Athenahealth — A cloud-native platform with integrated practice management and certified EHR functionality; athenaOne’s certification posture and cloud-first model reduce barriers for practices seeking rapid deployment.
-
eClinicalWorks — A competitive choice for ambulatory care and mid-market practices, notable for patient engagement tools and telehealth integration.
-
GE HealthCare — Strong where imaging and diagnostics must integrate tightly with the EHR; its enterprise solutions target hospitals seeking AI-enhanced workflows in diagnostic contexts.
Recent vendor moves illustrate where product and partnership momentum is concentrated: Epic’s October 2025 enhancements focused on AI-powered summarization and interoperability; Oracle Cerner’s partnership with a major cloud provider in late 2025 underscores the race to combine enterprise EHR scale with cloud analytics; and Athenahealth’s mid-2025 certification highlights the continuing importance of regulatory alignment for buyer confidence. PW Consulting’s vendor scorecards synthesize these events into procurement-grade intelligence.
What the PW Consulting report delivers (practical, implementation-focused)
-
Transparent market sizing and scenario forecasts: historical series (2020–2025) and forward-looking scenarios through 2032 with sensitivity to macroeconomic, regulatory, and technology adoption assumptions.
-
Go-to-market playbooks for provider systems and vendors: sequence of capability investments, recommended timelines, and a prioritized feature roadmap keyed to payer and regulatory incentives.
-
Procurement and contracting toolkit: RFP templates, SLAs, data portability clauses, and negotiation levers that reduce total cost of ownership while preserving clinical flexibility.
-
Integration and implementation playbooks: a phased approach for migration (hybrid coexistence, cutover strategies, rollback planning) and clinical adoption playbooks that tie training to measurable operational KPIs.
-
Regulatory compliance matrix: a practical checklist mapping ONC rules, HITECH obligations, CMS incentives, and EU data protection requirements to implementation milestones.
-
Vendor scorecards and shortlists: objective scoring across functional, technical, commercial, and strategic axes to accelerate vendor selection without sacrificing due diligence.
-
Case studies and ROI models: validated examples showing time-to-value, productivity impacts, and how to calculate a conservative financial case for investment approval.
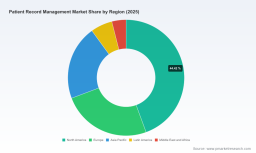
Note: To preserve strategic value for report subscribers and partners, PW Consulting intentionally withholds granular regional and application-split figures from this public release. The full dataset, including detailed segmentation, market share by deployment and end-user type, and downloadable forecast tables, is available in the complete report and accompanying data appendices.
Operational risks and mitigation — what to watch in 2026
-
Data migration and legacy lock-in: Avoid “rip-and-replace” decisions driven purely by short-term incentives. Instead, prioritize interoperability layers and phased data migration validated with reconciliation tests.
-
AI governance gaps: Implement model validation pipelines and clinician-in-the-loop controls before scaling automated summarization or decision support.
-
Compliance drift: Maintain a living compliance audit tied to versioned consent artifacts, especially for cross-border data flows subject to GDPR-like constraints.
-
Supplier concentration risk: Use contract structures that preserve portability — escrow for critical binaries and open, standardized APIs to reduce switching costs.
Recommended next steps for executives in 2026
-
Define an “interoperability-first” architecture mandate that requires FHIR-based APIs for any new procurement and a documented data map for legacy systems.
-
Prioritize a cloud migration decision tree: which capabilities to move, which to retain on-premise, and which to adopt in a SaaS-first model to realize the fastest operational ROI.
-
Run a short-listing workshop using PW Consulting’s vendor scorecards to reduce vendor evaluation time and ensure alignment with clinical leaders, CIOs, and compliance officers.
-
Pilot AI-enabled summarization or coding-assist features in a controlled environment and measure impact on clinician time, documentation quality, and billing accuracy before broad roll-out.
-
Leverage available incentives and regulatory alignment programs to offset deployment costs and accelerate adoption where eligible.
How to use this insight
For board members, this report provides the market context and risk framework needed to approve multi-year digital health investments. For CIOs and CMIOs, it offers the procurement tools and implementation playbooks required to deliver projects on time and within budget. For investors and corporate strategists, the report’s combination of concentration metrics, vendor momentum signals, and scenario forecasts identifies acquisition targets and partnership opportunities.
PW Consulting’s Patient Record Management Market report is intentionally practical — it gives you the forecast and a set of executable choices without substituting for the local clinical judgment and compliance counsel your organization needs. For the complete datasets, vendor-by-vendor scorecards, and the full suite of implementation templates, download the full report from PW Consulting’s Research Center.
For detailed analysis of this topic, please visit the official page: Patient Record Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com